Aerospace Plastics Market Trends Reshaping Modern Aircraft Design

The global aerospace plastics market size was estimated at USD 8.15 billion in 2024 and is expected to reach USD 13.88 billion by 2030, growing at a CAGR of 9.6% from 2025 to 2030. The rising utilization of plastics across various aerospace applications—such as cabin interiors, structural components, electrical electronics & control panels, windows, windshields, and canopies—is projected to fuel market growth over the coming years.

Reducing the overall aircraft weight has a direct impact on operational efficiency and performance. Notably, even a 1-kilogram (kg) reduction in weight can offset the lifetime fuel-related operating costs of a commercial aircraft. Owing to their lightweight and durable nature, plastics are increasingly being adopted as alternatives to aluminum and steel components, thereby boosting their share in the total aircraft structure.
According to the International Trade Administration, U.S. Department of Commerce, the United States remains a leading player in the global aerospace industry. The country is home to major aircraft manufacturers such as Boeing, Lockheed Martin Corporation, Gulfstream Aerospace Corporation, and Airbus Helicopters, Inc., which contribute significantly to industry growth. Moreover, initiatives like the Continuous Lower Energy, Emissions and Noise (CLEEN) Program, launched in 2010, empower the Federal Aviation Administration (FAA) to reduce aviation noise and emissions while improving fuel efficiency by 20%. Such sustainability-driven efforts are fostering demand for advanced substitute materials like plastics, substantially supporting the growth of the U.S. aerospace plastics market.

Key Market Trends & Insights

  • North America led the market, accounting for 56.90% of total revenue in 2024.
  • By product, the polyetheretherketone (PEEK) segment held the largest share with 61.62% of revenue in 2024.
  • By process, injection molding dominated with a 36.95% revenue share in 2024.
  • By application, structural components accounted for 29.70% of revenue in 2024.
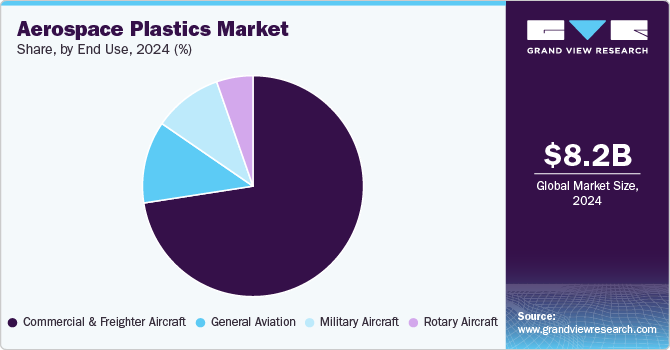
  • By end-use, the commercial & freighter aircraft segment led the market with a 72.56% share in 2024.

Download a free sample PDF of the Aerospace Plastics Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 8.15 Billion
  • 2030 Projected Market Size: USD 13.88 Billion
  • CAGR (2025–2030): 9.6%
  • North America: Largest market in 2024

Competitive Landscape

The aerospace plastics market is highly competitive, with numerous prominent players shaping industry trends. Companies are investing significantly in research and development (R&D) to enhance performance, cost efficiency, and sustainability. This competition continues to drive innovation and market expansion.

Recent Developments

  • August 2024: Pexco acquired Precise Aerospace Manufacturing to strengthen its aerospace capabilities. The acquisition expands Pexco’s product range and improves its customer service offerings, leveraging Precise Aerospace’s technical expertise to enhance market positioning.
  • August 2024: Trelleborg Group acquired Magee Plastics, a U.S.-based manufacturer specializing in high-performance thermoplastics and composites for aerospace. The acquisition bolsters Trelleborg’s Sealing Solutions division and reinforces its presence within the aerospace materials segment.

Key Companies Profiled

  • Victrex plc
  • Ensinger
  • SABIC
  • Solvay
  • BASF SE
  • Evonik Industries AG
  • Toray Advanced Composites
  • Saint Gobain Aerospace
  • DuPont

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global aerospace plastics market continues to experience robust growth driven by weight reduction initiatives, increased aircraft production, and a strong shift toward sustainable and fuel-efficient materials. The expanding adoption of high-performance plastics in critical aerospace applications positions the industry for substantial progress through 2030.

Extracorporeal Membrane Oxygenation Machine Market Key Growth Drivers

The global extracorporeal membrane oxygenation machine market was valued at USD 307.9 million in 2023 and is projected to reach USD 445.7 million by 2030, expanding at a CAGR of 5.5% from 2024 to 2030. Market growth is primarily driven by the rising incidence of cardiopulmonary diseases and respiratory failures.

According to the Centers for Disease Control and Prevention (CDC), a person dies every 37 seconds from cardiovascular disease in the U.S., emphasizing the growing demand for advanced life-support technologies like ECMO systems. Additionally, chronic obstructive pulmonary disease (COPD), one of the leading causes of death in the U.S., continues to fuel market demand. As per the American Lung Association (2022), approximately 4.6% of adults, or 11.7 million people, reported a COPD diagnosis, highlighting the rising burden of respiratory conditions. In response, technological advancements have led to the development of hollow pumps, high-efficiency oxygenators, and heparin-coated cannulas, significantly improving ECMO system performance and versatility in surgical and critical care settings.

The increasing adoption of ECMO systems in hospitals and the expansion of awareness programs have been pivotal in driving market growth. Over the past 3–5 years, more than 100 new ECMO programs have been established in the U.S., bringing the total to around 300–400. This surge reflects growing clinical acceptance and broader access to ECMO therapy. In July 2022, Inspira Technologies OXY B.H.N. Ltd. launched the “Liby” System, a next-generation life support solution for patients suffering from severe heart and lung failure — marking a key milestone in ECMO innovation.

Technological progress has also led to the introduction of portable and compact ECMO machines, making them more adaptable across clinical settings and improving patient transport capabilities. The integration of miniaturized circuits and portable adapters has further expanded ECMO’s applications, especially for critical care transfers and emergency procedures.

Key Market Trends & Insights

  • North America dominated the market in 2023, holding a 39.5% revenue share.
  • The U.S. represented the largest share within North America.
  • By component, the oxygenators segment held the largest share at 34.61% in 2023 and is projected to register the fastest CAGR during the forecast period.
  • By modality, the veno-arterial segment accounted for the highest revenue share of 42.2% in 2023.
  • By application, the respiratory segment led the market with a 44.10% share in 2023.

Download a free sample PDF of the Extracorporeal Membrane Oxygenation Machine Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2023 Market Size: USD 307.9 Million
  • 2030 Projected Market Size: USD 445.7 Million
  • CAGR (2024–2030): 5.5%
  • North America: Largest market in 2023
  • Asia Pacific: Fastest-growing market

Competitive Landscape

The ECMO machine market is characterized by a competitive mix of established players and emerging innovators. Leading companies are focusing on technological innovation, global expansion, and AI integration to enhance patient outcomes and broaden clinical applications. The demand for portable, smart, and telemedicine-integrated ECMO systems is shaping the next phase of market evolution. Established firms are also expanding into emerging regions to meet the growing demand for advanced life support solutions.

Recent Developments

  • July 2023: BreathMo, an ECMO system based on maglev technology, was unveiled at the ASAIO Conference, marking a breakthrough in China’s domestic medical innovation.
  • April 2023: Abbott received two new FDA clearances for its CentriMag Blood Pump, expanding its use for long-term ECMO support in adults with heart and lung complications.
  • November 2022: LivaNova PLC secured FDA 510(k) clearance for its LifeSPARC circulatory support system, enabling broader clinical use in the U.S. market.
  • July 2022: Inspira Technologies OXY B.H.N. Ltd. launched the “Liby” System, an advanced ECMO platform for patients with severe cardiopulmonary failure.
  • July 2021: Xenios AG, a subsidiary of Fresenius Medical Care, received NMPA approval in China for its Xenios Console and patient kits, marking a key regulatory milestone in Asia.

Key Companies Profiled

  • Medtronic Plc
  • Maquet Holding
  • MicroPort Scientific Corporation
  • Terumo Cardiovascular System Corporation
  • Medos Medizintechnik
  • Nipro Medical Corporation
  • LivaNova PLC
  • CytoSorbents Corporation
  • EUROSETS S.R.L

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The extracorporeal membrane oxygenation (ECMO) machine market is poised for steady growth, driven by rising cardiopulmonary disease prevalence, expanding hospital adoption, and continuous technological innovation. The development of compact, portable, and AI-enhanced ECMO systems is expected to revolutionize critical care, improve patient outcomes, and fuel market expansion through 2030.

How Smart Insulin Delivery Systems Are Reshaping the Diabetes Devices Market

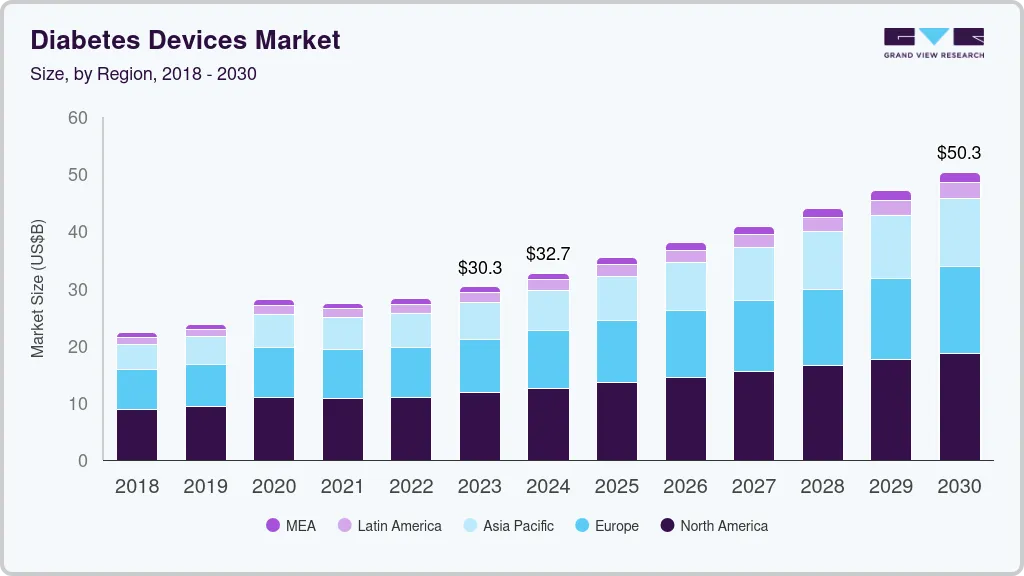
The global diabetes devices market size was valued at USD 30.31 billion in 2023 and is projected to reach USD 50.33 billion by 2030, expanding at a CAGR of 7.45% from 2024 to 2030. The market growth is fueled by the rising prevalence of diabetes, advancements in medical technology, increasing adoption of insulin delivery devices, and the growing obesity rates worldwide.

Leading manufacturers are emphasizing technological advancements and the development of innovative products to strengthen their market presence. For instance, in February 2023, Insulet Corporation acquired assets from Automated Glucose Control LLC (AGC), a California-based company specializing in automated insulin delivery systems. The global rise in diabetes prevalence continues to boost demand for such devices. According to the Institute for Health Metrics and Evaluation (June 2023), more than 500 million people globally live with diabetes, making it one of the top 10 causes of death and disability. The current global prevalence rate of 6.1% is expected to increase, with North Africa and the Middle East showing the highest rate at 9.3%, projected to reach 16.8% by 2050, while Latin America and the Caribbean are expected to rise to 11.3%.

The growing demand for diabetes devices stems from their ability to reduce hospital stays and mortality rates among diabetic patients. These devices enable continuous glucose monitoring and improved disease management, allowing patients to take proactive measures to prevent complications. Through real-time data and timely treatment adjustments, diabetes devices significantly enhance patient outcomes and quality of life, underlining their critical role in modern diabetes care.

Key Market Trends & Insights

  • The North American diabetes devices market held the largest revenue share of 38.66% in 2023.
  • The U.S. market is anticipated to register the fastest CAGR during the forecast period.
  • By type, the insulin delivery devices segment dominated the market, accounting for the largest share in 2023, and is projected to record the fastest CAGR of 7.89% through 2030.
  • By distribution channel, the hospital pharmacies segment led with 54.13% market share in 2023.
  • By end-use, the hospital segment accounted for the largest share at 40.80% in 2023.

Download a free sample PDF of the Diabetes Devices Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2023 Market Size: USD 30.31 Billion
  • 2030 Projected Market Size: USD 50.33 Billion
  • CAGR (2024–2030): 7.45%
  • North America: Largest market in 2023
  • Asia Pacific: Fastest-growing market

Competitive Landscape

Key players in the global diabetes devices market include Medtronic plc, Abbott Laboratories, F. Hoffmann-La Roche Ltd., Bayer AG, Lifescan, Inc., B. Braun Melsungen AG, and others. These companies focus on product innovation, strategic collaborations, and M&A activities to expand their market footprint. Emerging participants such as Companion Medical, Sanofi, Valeritas Holding Inc., Novo Nordisk, and Arkray, Inc. are also contributing to the competitive landscape through new product introductions and technological advancements.

Recent Developments

  • May 2023: Medtronic announced its agreement to acquire EOFlow, a maker of insulin delivery systems. The integration of EOFlow’s solutions with Medtronic’s Meal Detection Technology and CGM systems aims to enhance diabetes management capabilities.
  • April 2023: Undbio revealed plans to invest USD 100 million in building an insulin manufacturing plant in West Virginia, U.S., to expand domestic insulin production.
  • July 2023: CharmHealth and Bioverge jointly invested in My Diabetes Tutor, a startup focused on improving diabetes care and patient education.

Key Companies Profiled

  • Medtronic plc
  • Abbott Laboratories
  • F. Hoffmann-La Roche Ltd.
  • Bayer AG
  • Lifescan, Inc.
  • B. Braun Melsungen AG
  • Dexcom Inc.
  • Insulet Corporation

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The diabetes devices market is set for sustained growth, driven by rising diabetes prevalence, technological innovations, and growing demand for efficient monitoring and delivery systems. Continuous advancements in digital health and insulin management are expected to transform patient outcomes and accelerate global market expansion through 2030.

Exploring Growth Drivers Transforming the Cyber Security Market

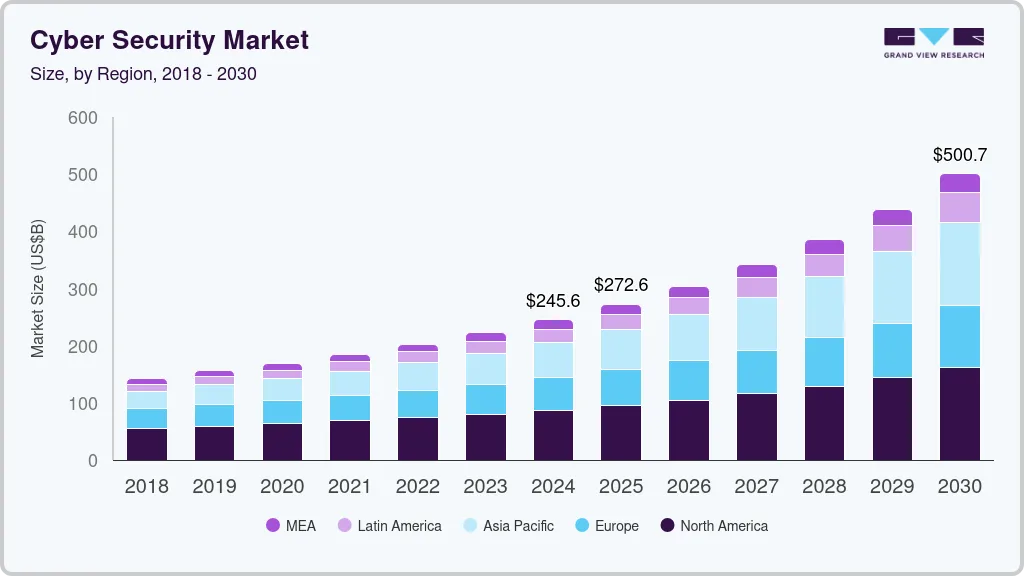
The global cyber security market size was estimated at USD 245.62 billion in 2024 and is projected to reach USD 500.70 billion by 2030, growing at a CAGR of 12.9% from 2025 to 2030. The market growth is primarily driven by the rising incidence of cyberattacks fueled by the expansion of e-commerce platforms, smart devices, and cloud deployment.

The increasing adoption of Internet of Things (IoT) and intelligent technologies has heightened vulnerability to cyber threats, prompting organizations to adopt advanced cyber security solutions to mitigate risks. Furthermore, the widespread shift toward remote working models, along with Bring Your Own Device (BYOD) and Choose Your Own Device (CYOD) policies, has expanded the attack surface for cybercriminals, necessitating stronger digital protection measures.

Traditional security frameworks are often inadequate against Advanced Persistent Threats (APT) and sophisticated malware, leading to a growing demand for AI-driven and automated cyber defense systems. Additionally, the cybersecurity training market is witnessing rapid growth as companies emphasize workforce education to prevent data breaches and mitigate security risks.

Key Market Trends & Insights

  • North America dominated the market with a revenue share of over 34% in 2024.
  • The U.S. cyber security market is expected to experience substantial growth.
  • By security type, the infrastructure protection segment held the largest revenue share in 2024.
  • By organization size, the large enterprises segment accounted for the largest share in 2024.
  • By solution, the Identity and Access Management (IAM) segment led the market in 2024.

Download a free sample PDF of the Cyber Security Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 245.62 Billion
  • 2030 Projected Market Size: USD 500.70 Billion
  • CAGR (2025–2030): 12.9%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest-growing market

Competitive Landscape

Some of the key players operating in the cyber security industry include IBM Corporation, Microsoft, Broadcom, Inc., and Fortinet, Inc.

  • IBM Corporation is a global leader offering a comprehensive portfolio of cybersecurity solutions and services designed to combat evolving digital threats. With expertise in AI, automation, and hybrid cloud security, IBM provides cutting-edge tools for threat management, data protection, and identity access management. Its flagship IBM Security QRadar platform offers advanced threat detection and response capabilities, while its Zero Trust Architecture and X-Force Threat Intelligence initiatives strengthen enterprise resilience against emerging risks.
  • Microsoft leverages its vast ecosystem to deliver end-to-end cybersecurity solutions across cloud and hybrid environments. Its products, including Microsoft Defender, Azure Security Center, and Microsoft Sentinel, provide real-time threat detection, compliance management, and proactive defense. The company’s Zero Trust security framework and AI-driven analytics empower organizations to protect assets against sophisticated cyberattacks, reinforcing Microsoft’s leadership in the global cybersecurity landscape.

Key Companies Profiled

  • Fortinet, Inc.
  • IBM Corporation
  • Microsoft
  • BAE Systems Plc
  • Broadcom, Inc.
  • Centrify Corporation
  • Check Point Software Technology Ltd.
  • Palo Alto Networks, Inc.
  • Proofpoint, Inc.
  • Sophos Ltd.

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global cyber security market continues to evolve rapidly as organizations adopt digital transformation and cloud-first strategies. Rising cyber threats, increased IoT penetration, and remote work models are fueling the need for robust, AI-driven security frameworks. Ongoing innovation by leading players, coupled with growing awareness around data protection and regulatory compliance, will drive sustained market expansion. As enterprises prioritize Zero Trust architecture and cyber resilience, the market is expected to maintain strong momentum through the coming years.

Cosmetics Market Trends Redefining the Global Beauty and Personal Care Industry

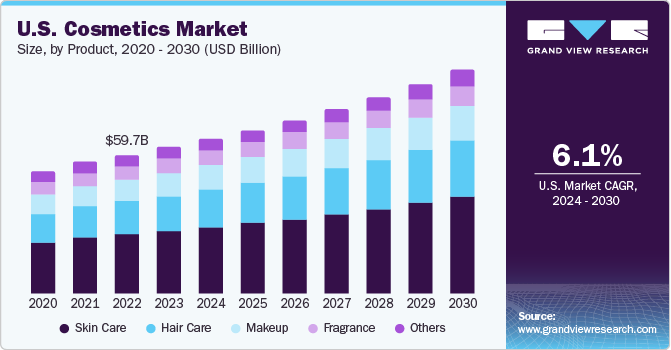
The global cosmetics market size was estimated at USD 295.95 billion in 2023 and is projected to reach USD 445.98 billion by 2030, expanding at a CAGR of 6.1% from 2024 to 2030. A key factor driving this growth is the increasing consumer focus on enhancing personal appearance and grooming standards.

Among millennials, products related to skincare, color cosmetics, and hair care have become essential components of daily routines. The growing demand for natural, non-toxic, and organic ingredients in cosmetic formulations is further propelling market expansion, as consumers increasingly prioritize clean beauty and sustainability.

Personal care products (PCPs)—used for hygiene, grooming, cleaning, and appearance enhancement—span a broad range of categories, including hair and skincare products, UV protection creams, facial cleansers, insect repellents, fragrances, perfumes, soaps, detergents, shampoos, conditioners, and toothpaste.

Soap continues to play a vital role in skincare, serving as an essential tool for maintaining cleanliness and overall skin health. According to Consumer Reports, consumer preferences regarding skincare and haircare are increasingly influenced by environmental awareness, sustainability, and ingredient transparency.

Key Market Trends & Insights

  • Asia Pacific held the largest market share of 45% in 2023.
  • The U.S. market is expected to grow at a CAGR of 6.1% from 2024 to 2030.
  • By product, the skincare cosmetics segment accounted for 43.3% of revenue share in 2023.
  • By end user, the women’s cosmetics segment held a 62.9% revenue share in 2023.
  • By distribution channel, offline sales accounted for 72.2% of total market revenue in 2023.

Download a free sample PDF of the Cosmetics Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2023 Market Size: USD 295.95 Billion
  • 2030 Projected Market Size: USD 445.98 Billion
  • CAGR (2024–2030): 6.1%
  • Asia Pacific: Largest market in 2023

Competitive Landscape

The cosmetics market features a mix of established global brands and emerging players, all competing through product innovation, differentiation, and sustainable design. Leading companies leverage their extensive global distribution networks to effectively reach diverse consumer bases and penetrate emerging markets.

Recent Developments

  • January 2024 – L’Oréal Group: Its venture capital arm, BOLD (Business Opportunities for L’Oréal Development), invested in Timeline, a consumer health company specializing in aging and longevity. Timeline integrates its proprietary Mitopure technology into skincare products and supplements to support its expansion across the beauty, food, and health sectors.
  • December 2023 – Estée Lauder: Partnered with the Stanford Center for a three-year initiative supporting the Program on Aesthetics & Culture, funding research projects such as the New Map of Life post-doctoral fellowships to explore perceptions of longevity and vitality.

Key Companies Profiled

  • Coty Inc.
  • L’Oréal Group
  • Estée Lauder Companies, Inc.
  • Revlon Consumer Products LLC
  • Avon Products, Inc.
  • Unilever
  • Company 7
  • Godrej Group
  • Procter & Gamble

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global cosmetics market is set for robust growth through 2030, fueled by rising consumer awareness, preference for clean and sustainable beauty products, and continuous innovation by leading brands. Growing demand across emerging economies, coupled with technological advancements in formulation and distribution, will continue to redefine the market landscape. With strong contributions from the skincare and women’s cosmetics segments, and increasing adoption of natural and organic products, the industry is positioned to maintain steady momentum in the coming years.

Construction Equipment Rental Market Trends Transforming the Building Industry

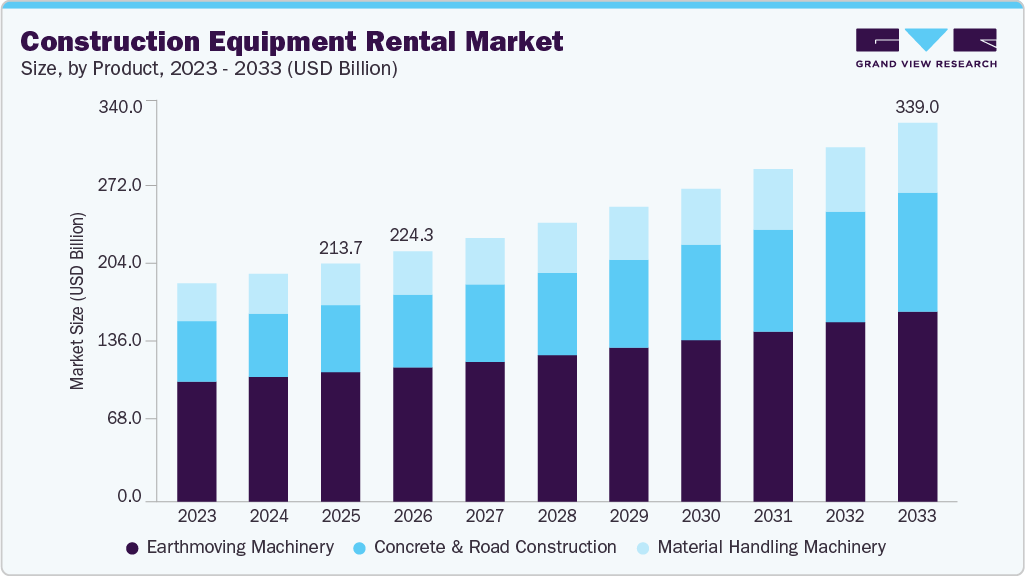
The global construction equipment rental market size was estimated at USD 204.06 billion in 2024 and is anticipated to reach USD 280.13 billion by 2030, growing at a CAGR of 5.6% from 2025 to 2030. The market’s growth is primarily driven by increasing government investments in public infrastructure projects, which have accelerated mining and construction activities across developing nations, fueling demand for construction equipment.

Rising costs of new machinery are making equipment rental an increasingly attractive option for contractors and construction firms. The integration of cutting-edge technologies and automation is further propelling market expansion. One key trend shaping the industry is the growing adoption of telematics systems, which enable rental companies to remotely monitor equipment usage, performance, and location. These advanced systems significantly enhance fleet management and preventive maintenance practices, improving operational efficiency.

The adoption of IoT-enabled devices and sensors in rental equipment has also surged, providing real-time insights into fuel consumption, equipment health, and operator safety. These innovations allow companies to optimize performance, minimize downtime, and improve asset utilization.

Additionally, online platforms and mobile applications are transforming the equipment rental landscape by streamlining rental operations and expanding access for both owners and renters. Such platforms enable equipment owners—particularly small and mid-sized businesses—to showcase their inventory to a wider audience, secure more rental agreements, and generate additional revenue. This digital transformation is fostering a more transparent, competitive, and customer-focused rental ecosystem, offering enhanced convenience and service quality.

Key Market Trends & Insights

  • The Asia Pacific market accounted for 49.7% of the overall market share in 2024.
  • The U.S. construction equipment rental industry maintained a dominant position in 2024.
  • By product, earthmoving machinery led the market with a 54.7% share in 2024.
  • By drive type, the ICE segment accounted for the largest market revenue share in 2024.

Download a free sample PDF of the Construction Equipment Rental Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 204.06 Billion
  • 2030 Projected Market Size: USD 280.13 Billion
  • CAGR (2025–2030): 5.6%
  • Asia Pacific: Largest market in 2024

Competitive Landscape

The construction equipment rental market features several leading global players focused on expanding their rental fleets, strengthening regional presence, and integrating advanced telematics technologies.

Key players include Caterpillar Inc., Deere & Company, Komatsu Ltd., Liebherr-International AG, and United Rentals, Inc.

  • Liebherr-International AG, along with its subsidiaries, manufactures and supplies a broad range of construction machinery and equipment. Its product portfolio includes mobile and crawler cranes, concrete technology, deep foundation machines, maritime cranes, and port equipment, as well as aerospace systems, refrigeration solutions, and automation components.
  • United Rentals, Inc., based in the U.S., is one of the largest equipment rental providers globally, operating over 1,400 branches across North America and Europe. The company’s extensive network includes 1,345 rental locations in North America and 11 in Europe, with a strong presence across the U.S., Canada, Europe, and Asia Pacific.

Key Companies Profiled

  • Ahern Rentals Inc.
  • AKTIO Corporation
  • Caterpillar Inc.
  • Byrne Equipment Rental
  • Cramo Plc
  • Finning International Inc.
  • Liebherr-International AG
  • Kanamoto Co., Ltd.
  • Maxim Crane Works, L.P.
  • United Rentals, Inc.

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global construction equipment rental market is poised for steady growth through 2030, driven by infrastructure investments, digitalization, and technological integration in equipment management. Rising equipment costs and the growing adoption of telematics and IoT-based solutions are making rental services more efficient and cost-effective. Supported by strong demand from construction, mining, and industrial sectors, the market is expected to experience sustained momentum, led by key players such as Caterpillar, Liebherr, and United Rentals.

Collaborative Robot Market Growth Driven by AI and Machine Learning Integration

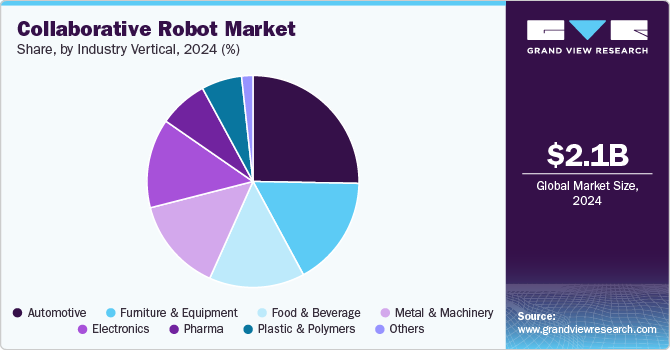
The global collaborative robot market size was estimated at USD 2.14 billion in 2024 and is projected to reach USD 11.64 billion by 2030, growing at a CAGR of 31.6% from 2025 to 2030. Market growth is primarily driven by the rising demand for automation across industries such as manufacturing, healthcare, automotive, and logistics.

Companies are increasingly seeking cost-effective and flexible automation solutions to enhance productivity and minimize human errors. Collaborative robots, or cobots, provide a significant advantage by working safely alongside humans—enhancing efficiency without requiring costly safety enclosures. This feature is fostering broader adoption of cobots across industries, further propelling market expansion in the coming years.

The growing emphasis on workplace safety is another key factor driving cobot deployment. Designed with integrated safety features, cobots can operate in close proximity to human workers without extensive safety barriers. This not only enhances worker safety but also improves ergonomics by handling repetitive or physically demanding tasks, thereby reducing the risk of injuries and increasing overall workforce productivity. This trend is expected to continue supporting market growth over the forecast period.

Furthermore, the market is experiencing increased adoption across diverse sectors such as automotive, electronics, healthcare, and food processing. Each of these industries recognizes the operational advantages of integrating cobots—whether it’s boosting assembly line efficiency in automotive manufacturing or enhancing quality control in electronics production. The wide applicability and flexibility of cobots are driving their demand as companies pursue tailored automation solutions that align with their specific operational needs.

Key Market Trends & Insights

  • The Asia Pacific collaborative robot market accounted for the largest revenue share of over 38% in 2024.
  • The U.S. dominated the North American collaborative robot market in 2024.
  • By payload capacity, the up to 5 kg segment captured the largest market share of over 43% in 2024.
  • By application, the assembly segment held the largest share in 2024.
  • By industry vertical, the automotive segment led the market in 2024, driven by extensive automation adoption.

Download a free sample PDF of the Collaborative Robot Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 2.14 Billion
  • 2030 Projected Market Size: USD 11.64 Billion
  • CAGR (2025–2030): 31.6%
  • Asia Pacific: Largest market in 2024

Competitive Landscape

The global collaborative robot market features a mix of established leaders and emerging players pursuing innovation, partnerships, and technological advancement to strengthen their market positions.

ABB Group and KUKA AG are among the key players shaping the competitive landscape.

  • ABB Group operates across power, robotics, and automation technologies with four major divisions: electrification products, discrete automation and motion, process automation, and power grids. Its product portfolio includes collaborative robots such as YuMi, GoFa, and SWIFTI, supported by a strong global presence across North America, South America, Asia Pacific, Europe, and the Middle East & Africa.
  • KUKA AG, headquartered in Germany, is a leading provider of intelligent automation solutions. The company focuses on the development, production, and sale of industrial robots, controllers, and software, serving industries such as manufacturing and logistics. Its main business units include KUKA Industries, KUKA Robotics, KUKA Systems, and Swisslog.

Emerging participants such as Energid Technologies Corporation and Fanuc Corporation are also contributing to market innovation.

  • Energid Technologies Corporation (acquired by Teradyne, Inc.) develops advanced robotic systems and software, serving industries including aerospace, agriculture, defense, transportation, and healthcare. Its patented software platform, Actin, is designed for commercial, industrial, and mission-oriented robotics applications.
  • Fanuc Corporation is a prominent provider of automation products and services, including robots, robotic machines, CNC systems, servo motors, and laser products. The company focuses on large-scale production and global distribution of robotic and CNC solutions.

Key Companies Profiled

  • ABB Group
  • DENSO Corporation
  • Epson America Inc.
  • AUBO (BEIJING) ROBOTICS TECHNOLOGY CO., LTD
  • Comau S.p.A.
  • Energid Technologies Corporation
  • Fanuc Corporation
  • KUKA AG

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global collaborative robot market is experiencing rapid growth, fueled by the increasing demand for intelligent and flexible automation across industries. With rising focus on workplace safety, cost efficiency, and operational productivity, cobots are becoming a crucial component of modern industrial systems. Their ability to work safely alongside humans while improving efficiency positions them as a key driver of the next wave of industrial automation. Supported by strong adoption in automotive and manufacturing sectors, and led by technological innovation from global players like ABB, KUKA, and Fanuc, the collaborative robot market is set to achieve remarkable growth through 2030.


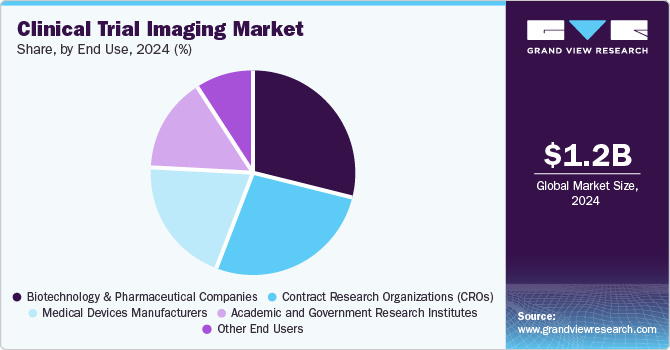
Clinical Trial Imaging Market Poised for Expansion with AI and Automation Advances

The global clinical trial imaging market size was estimated at USD 1.23 billion in 2024 and is projected to reach USD 1.91 billion by 2030, growing at a CAGR of 7.8% from 2025 to 2030. Market growth is primarily driven by the expansion of the biotechnology and pharmaceutical sectors, along with rising investments in research and development aimed at developing novel therapeutics for diverse diseases.

Medical imaging continues to play a vital role in the advancement of innovative life science products. Despite the dynamic and evolving nature of the imaging industry, the biopharmaceutical and medical device sectors are experiencing sustained growth, supported by substantial investments and strategic mergers and acquisitions. These M&A activities increasingly focus on integrating advanced imaging technologies to enhance the efficiency and precision of the clinical trial process.

The clinical trial imaging market is witnessing steady expansion, fueled by growing R&D activities in new drug and therapy development. With more than 400,000 registered clinical trials globally, the demand for robust imaging solutions has surged—particularly across oncology, cardiology, and neurology applications. The integration of AI-powered image analysis and advanced imaging modalities is expected to improve data accuracy and streamline clinical assessments. Furthermore, the COVID-19 pandemic accelerated the adoption of virtual imaging trials, with approximately 30% of clinical trials employing virtual methodologies by 2021, showcasing the sector’s adaptability and resilience during global disruptions.

Key Market Trends & Insights

  • North America accounted for the largest share of the global clinical trial imaging market at 47.93% in 2024.
  • Asia Pacific is projected to record the fastest growth rate of 8.4% during the forecast period.
  • By modality, the computed tomography (CT) scan segment held the largest share at 25.87% in 2024.
  • Based on therapeutic area, oncology dominated the market with a 23.63% share in 2024.
  • By services, the reading and analytical services segment led the market with a 30.95% share in 2024 and is expected to grow at a CAGR of 8.4% from 2025 to 2030.

Download a free sample PDF of the Clinical Trial Imaging Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 1.23 Billion
  • 2030 Projected Market Size: USD 1.91 Billion
  • CAGR (2025–2030): 7.8%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Competitive Landscape

Leading market players are expanding their global presence through partnerships, collaborations, and acquisitions to enter new markets and strengthen technological capabilities. Collaborations with academic medical centers and research institutions, such as the Mayo Clinic, are becoming increasingly common as companies seek access to clinical expertise and real-world validation for their imaging technologies.

For example, in September 2023, GE HealthCare announced a strategic collaboration with the Mayo Clinic to drive innovation in medical imaging and theragnostics. This partnership aims to advance the development of new technologies and solutions that can enhance diagnostics, precision imaging, and patient care.

Recent Developments

  • March 2023: Clario introduced a cloud-based image viewer designed specifically for clinical trials to improve medical image accessibility and streamline analysis workflows.
  • May 2023: Cleerly partnered with ProScan Imaging to deliver personalized cardiac health solutions leveraging Cleerly’s AI-powered platform for analyzing coronary CT angiography (CCTA) images, supporting more precise cardiovascular diagnostics.

Key Companies Profiled

  • IXICO plc
  • Navitas Life Sciences
  • Resonance Health
  • ProScan Imaging
  • Radiant Sage LLC
  • Medpace
  • Biomedical Systems Corp
  • Cardiovascular Imaging Technologies
  • Intrinsic Imaging
  • BioTelemetry

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global clinical trial imaging market is poised for steady expansion, supported by the growth of the biopharmaceutical sector, the integration of advanced imaging technologies, and the increasing adoption of AI-driven analytical tools. Rising global clinical trial volumes and the adoption of virtual imaging solutions are enhancing trial efficiency and accuracy. Strategic collaborations among key players and research institutions are further driving innovation and enabling improved clinical outcomes. With North America maintaining dominance and Asia Pacific emerging as a high-growth region, the market is set to achieve sustained momentum through 2030.


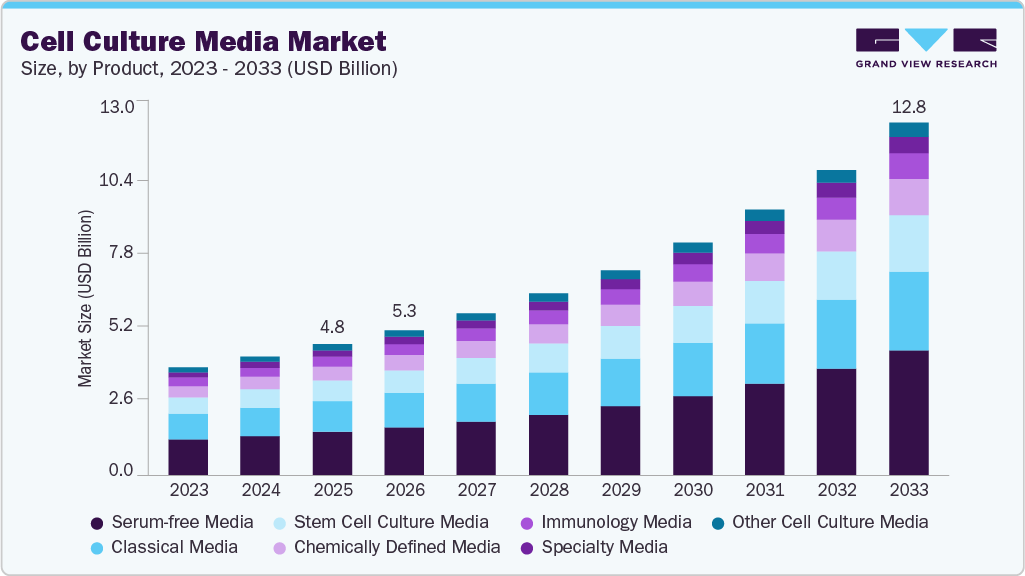
Global Cell Culture Media Market Growth Fueled by Rising Biotech Investments

The global cell culture media market size was estimated at USD 4.31 billion in 2024 and is projected to reach USD 12.80 billion by 2033, growing at a CAGR of 13.20% from 2025 to 2033. Cell culture media, typically a gel or liquid, contains essential nutrients and compounds that regulate and support the growth of cells or microorganisms used in biopharmaceutical manufacturing.

The cell culture media industry is currently in a high-growth phase, driven by increasing demand from the biopharma, diagnostics, and research sectors. The market is witnessing rapid advancements in media formulations, significant investments in biotechnology research, and expanding applications in drug discovery, regenerative medicine, and personalized therapies. Competition and innovation are fueling new product launches and strategic collaborations among leading companies. For instance, in December 2024, Creative Biolabs (U.S.) introduced advanced iPSC and FGF2 solutions to accelerate stem cell therapy research and provide customized support for global regenerative medicine initiatives.

The industry is also observing a high level of mergers and acquisitions (M&A), driven by the need for market consolidation and portfolio expansion. Leading companies are acquiring smaller players to strengthen technological capabilities and extend their global presence. For example, in March 2022, Fujifilm, through its Life Sciences division in Japan and the U.S., acquired Shenandoah Biotechnology (Pennsylvania) to enhance its recombinant protein and cell culture expertise worldwide. These strategic efforts enable key players to meet the increasing demands of the biopharma, diagnostics, and research markets while maintaining competitiveness in a rapidly evolving landscape.

Key Market Trends & Insights

  • North America held the largest revenue share of 38.57% of the global market in 2024.
  • The U.S. cell culture media market is expected to experience significant growth during the forecast period.
  • By product, the serum-free media segment accounted for the highest share at 33.16% in 2024.
  • Based on application, biopharmaceutical production dominated with a 47.79% revenue share in 2024.
  • By end-use, pharmaceutical & biotechnology companies captured the largest share of 34.17% in 2024.

Download a free sample PDF of the Cell Culture Media Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 4.31 Billion
  • 2033 Projected Market Size: USD 12.80 Billion
  • CAGR (2025–2033): 13.20%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Competitive Landscape

The cell culture media market is characterized by a mix of established global leaders and emerging innovators striving to address the evolving needs of biotechnology, pharmaceutical, and regenerative medicine industries. Major players such as Sartorius AG, Danaher, Merck KGaA, Thermo Fisher Scientific, Inc., FUJIFILM Corporation, and Lonza have strengthened their market positions through robust product portfolios, wide distribution networks, and continuous R&D investments. Their offerings range from classical and serum-free media to advanced formulations designed for vaccine production, biopharmaceutical manufacturing, stem cell research, and cancer biology.

Meanwhile, companies including BD, STEMCELL Technologies, Cell Biologics, Inc., and PromoCell GmbH are expanding their global footprint through niche product innovations and customized media solutions that cater to the dynamic needs of researchers and clinical developers.

Recent Developments

  • May 2025: PL BioScience (Germany) partnered with DewCell Biotherapeutics (South Korea) to launch a scalable, animal-free artificial human platelet lysate, offering a next-generation cell culture medium for global cell therapy applications.
  • April 2025: Capricorn Scientific collaborated with florabio AS (Turkey) to introduce animal-free, high-yield cell culture media, combining their expertise in scalable, defined formulations to support global biotech and vaccine R&D.

Key Companies Profiled

  • Sartorius AG
  • Danaher
  • Merck KGaA
  • Thermo Fisher Scientific, Inc.
  • FUJIFILM Corporation
  • Lonza
  • BD
  • STEMCELL Technologies
  • Cell Biologics, Inc.
  • PromoCell GmbH

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global cell culture media market is poised for robust growth, driven by expanding applications in biopharmaceutical production, regenerative medicine, and personalized therapies. Advancements in serum-free and animal-free formulations, coupled with rising investments in biotech R&D, are reshaping the industry landscape. Strategic collaborations, mergers, and acquisitions among key players are enhancing technological capabilities and expanding global reach. With North America leading in market share and Asia Pacific emerging as the fastest-growing region, the market is set to witness sustained momentum through 2033, supported by innovation, scalability, and the growing demand for high-quality cell culture solutions.

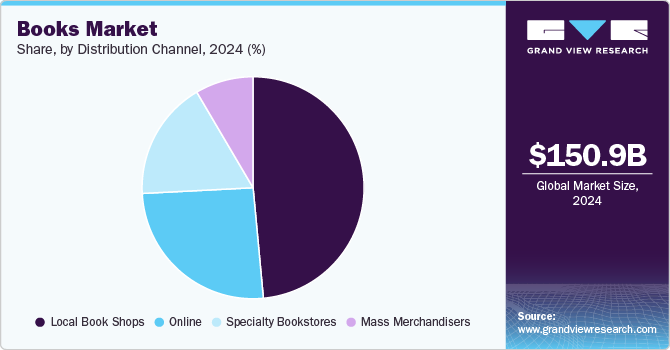
Books Market Growth Driven by Rising Reading Culture

The global books market size was estimated at USD 150.99 billion in 2024 and is projected to reach USD 192.12 billion by 2030, growing at a CAGR of 4.2% from 2025 to 2030. Rising consumer spending on books—fueled by increasing disposable incomes, growing interest in reading, and innovations in book formats—continues to drive market expansion.

The market remains largely dominated by academic publishers, while non-academic or trade publishing accounts for a smaller share. Academic publishing benefits from its close association with the global education ecosystem, catering primarily to schools, universities, research institutes, and professional education sectors.

Technological advancements have further transformed the reading experience. The introduction of audio and video-integrated e-books has attracted diverse audiences across regions, while improved accessibility of paperback formats for differently-abled and non-English-speaking readers continues to support inclusive market growth.

Key Market Trends & Insights

  • North America accounted for over 33.0% of the global market revenue in 2024.
  • The U.S. books market is expected to grow at a CAGR of 4.2% from 2025 to 2030.
  • By type, the educational segment held an 18.29% share in 2024.
  • By category, the fictional books segment dominated with a 59.99% share in 2024.
  • By format, the hard copy segment accounted for 84.12% of total revenue in 2024.

Download a free sample PDF of the Books Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 150.99 Billion
  • 2030 Projected Market Size: USD 192.12 Billion
  • CAGR (2025–2030): 4.2%
  • Largest Market (2024): North America

Competitive Landscape

The global books market is fragmented, featuring a blend of large multinational publishers and smaller independent players that contribute to the sector’s creative diversity. Major players such as Penguin Random House, Hachette Book Group, HarperCollins, Simon & Schuster, Macmillan, and Pearson dominate the landscape with their broad product portfolios and global distribution networks.

These companies continue to strengthen their market presence through digital transformation, mergers and acquisitions, and strategic partnerships. For instance, Penguin Random House’s acquisition of Simon & Schuster significantly enhanced its presence in the North American market.

Recent Developments

  • 2024: Penguin Random House launched new mystery and thriller titles in both e-book and hardcopy formats.
  • November 2020: Pearson established a direct-to-consumer division, aiming to build stronger connections with learners worldwide.
  • November 2020: Scholastic Inc. announced a multi-book publishing program with civil rights icon Ruby Bridges.
  • November 2020: HarperCollins signed a two-book deal with filmmaker Quentin Tarantino, whose debut novel “Once Upon a Time in Hollywood” was released in Summer 2021.

Key Companies Profiled

  • Penguin Random House
  • Hachette Book Group
  • HarperCollins Publishers
  • Simon & Schuster, Inc.
  • Pearson
  • Macmillan Publishers
  • Scholastic Inc.
  • Marvel Comics
  • Morris Publishing
  • IDW Publishing

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global books market continues to evolve, supported by technological advancements, educational demand, and the enduring appeal of fiction and print media. As publishers adapt to digital ecosystems and explore innovative content formats, the industry is poised for steady growth through 2030.


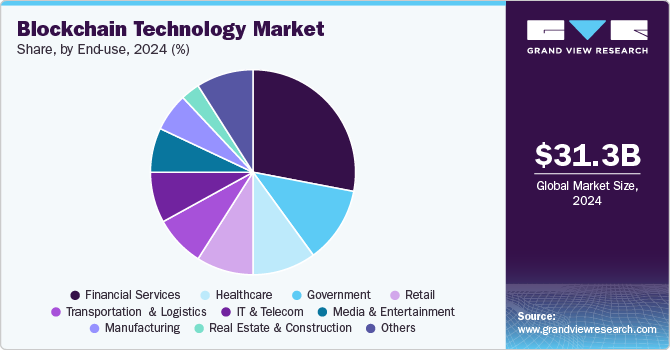
Blockchain Technology Market Poised to Revolutionize Industries

The global blockchain technology market size was valued at USD 31.28 billion in 2024 and is projected to reach USD 1,431.54 billion by 2030, expanding at an exceptional CAGR of 90.1% from 2025 to 2030. The rising demand for secure, transparent, and decentralized transaction systems across multiple industries continues to fuel market growth.

Blockchain’s immutable and decentralized ledger system ensures transparency and integrity in data management, making it particularly valuable to sectors such as finance, healthcare, and supply chain management. Organizations in these industries are increasingly integrating blockchain solutions to enhance security, traceability, and operational efficiency.

Market Drivers

The growing adoption of blockchain in supply chain optimization is a key growth driver. The technology’s ability to trace, verify, and authenticate the movement of goods in real-time minimizes fraud, strengthens transparency, and boosts overall supply chain efficiency. Consequently, enterprises are actively leveraging blockchain to digitally transform their supply chain operations.

Additionally, the surging interest in cryptocurrencies and digital assets continues to drive the adoption of blockchain technology. As the foundational technology behind cryptocurrencies like Bitcoin and Ethereum, blockchain is being explored for broader applications such as Central Bank Digital Currencies (CBDCs) and digital asset management.

Furthermore, the increasing need for secure and cost-effective cross-border payments is accelerating blockchain’s penetration in the financial sector. Unlike traditional international payment systems that involve multiple intermediaries and high fees, blockchain-based solutions offer faster, transparent, and low-cost transactions, thereby reshaping the global remittance landscape.

Key Market Trends & Insights

  • North America dominated the global market in 2024, accounting for 37.4% of total revenue.
  • The U.S. blockchain technology market is anticipated to grow at a significant CAGR from 2025 to 2030.
  • By type, the public cloud segment led the market with a 61.5% revenue share in 2024.
  • By component, the infrastructure & protocols segment dominated in 2024.
  • By offering, the platform segment held the largest share in 2024.

Download a free sample PDF of the Blockchain Technology Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 31.28 Billion
  • 2030 Projected Market Size: USD 1,431.54 Billion
  • CAGR (2025–2030): 90.1%
  • Largest Market (2024): North America
  • Fastest-Growing Market: Asia Pacific

Competitive Landscape

The global blockchain technology market is highly competitive, with leading players focusing on innovation, product expansion, and strategic collaborations to maintain their market position. Key participants include IBM Corporation, Microsoft Corporation, The Linux Foundation, Blockchain Tech LTD, and others.

  • Monax Labs: A pioneer in blockchain-based smart contract solutions, offering a decentralized platform for secure, transparent legal and contractual processes.
  • Chain: Specializes in scalable blockchain infrastructure for enterprises, enabling secure asset transfers and smart contract automation across industries such as finance, healthcare, and logistics.

Recent Developments

  • January 2024: Chain upgraded its Chain Prime product, evolving it into a comprehensive Trading-as-a-Service (TaaS) platform for institutional clients, while focusing on enterprise blockchain products like Chain Cloud, Sequence, and Chain NFTs.
  • December 2023: RYVYL partnered with R3 to launch RYVYL Block, a blockchain-as-a-service platform simplifying blockchain adoption for businesses handling high transaction volumes.
  • October 2023: DTCC acquired Securrency Inc., aiming to embed blockchain-based digital asset infrastructure into its financial services offerings.
  • September 2023: LayerZero collaborated with Google Cloud, appointing it as its primary oracle provider to ensure secure verification of cross-chain transactions.

Key Companies Profiled

  • IBM Corporation
  • Microsoft Corporation
  • The Linux Foundation
  • Blockchain Tech LTD
  • Chain
  • Circle Internet Financial, LLC
  • Deloitte Touche Tohmatsu Limited
  • Digital Asset Holdings, LLC
  • Global Arena Holding, Inc. (GAHC)

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The blockchain technology market is on an exponential growth trajectory, driven by the rising need for transparency, efficiency, and digital security. As industries increasingly adopt blockchain for digital transformation, the technology is set to redefine global business operations, particularly in finance, logistics, and governance.

Biogas Market Poised for Steady Growth Through 2030

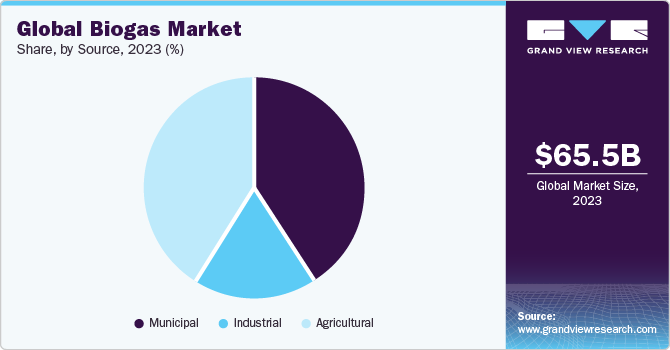
The global biogas market size was estimated at USD 65.53 billion in 2023 and is projected to reach USD 87.86 billion by 2030, growing at a CAGR of 4.2% from 2024 to 2030. The industry is poised for steady growth due to increasing demand across multiple applications, including heat, electricity, upgraded biogas, vehicle fuel, and cooking gas.

A growing focus on renewable energy sources, particularly within the electric power sector, has accelerated the adoption of biogas for electricity generation. Additionally, the rising need to reduce dependence on fossil fuels is creating lucrative opportunities for biogas utilization in vehicle fuel applications.

The U.S. emerged as one of the largest biogas markets in North America in 2023 and is expected to expand at a substantial CAGR during the forecast period. Government initiatives aimed at achieving zero carbon emissions and reducing reliance on conventional fuels are major growth drivers. Favorable regulatory frameworks, strong political support, and advancements in agricultural and waste management systems are further bolstering market expansion.

In North America, biogas demand is primarily driven by the U.S., supported by increasing applications in cooking gas, electricity generation, vehicle fuel, and heat production. The region benefits from stringent environmental regulations, growing investments in refinery infrastructure, and a rising preference for sustainable energy solutions.

However, the abrupt onset of the COVID-19 pandemic disrupted manufacturing and industrial operations worldwide, reducing demand for biogas in heat generation and other industrial applications. As industries recover and sustainability goals gain prominence, the market is anticipated to regain momentum.

Key Market Trends & Insights

  • Europe dominated the global market, accounting for 41% of revenue share in 2023.
  • Italy’s biogas market growth is being fueled by strong government initiatives toward decarbonization.
  • By application, the electricity segment led the market, accounting for around 30% of revenue share in 2023.
  • By source, municipal sources accounted for the largest share of 41.35% in 2023.

Download a free sample PDF of the Biogas Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2023 Market Size: USD 65.53 Billion
  • 2030 Projected Market Size: USD 87.86 Billion
  • CAGR (2024–2030): 4.2%
  • Europe: Largest market in 2023

Competitive Landscape

The global biogas market is highly competitive, characterized by the presence of leading international players. Key companies such as Air Liquide, PlanET Biogas, Wartsila, EnviTech Biogas AG, Robert Bosch GmbH, Asia Biogas, and Schmack Biogas GmbH dominate the market through large-scale operations and significant R&D investments.

Spanish firms are also taking major steps to promote biogas adoption. For example, in June 2020, Repsol, a Spanish energy company, announced the development of an industrial-scale biogas project, emphasizing the country’s commitment to renewable energy transition.

Key Companies Profiled

  • Agrinz Technologies GmbH
  • Air Liquide
  • DMT International
  • Gasum Oy
  • HomeBiogas Inc.
  • PlanET Biogas
  • Scandinavian Biogas Fuels International AB
  • Schmack Biogas Service
  • Total
  • Xebec Adsorption Inc.

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global biogas market is gaining traction as governments and industries increasingly prioritize sustainable and low-carbon energy alternatives. Rising investments in biogas infrastructure and favorable policies for renewable integration are enhancing market opportunities. Europe continues to lead due to strong regulatory backing, while North America and Asia Pacific show promising growth potential. The shift toward circular economies and waste-to-energy systems will remain key to driving long-term market expansion.

Barbeque Grill Market Leaders Strengthen Portfolios Through New Launches

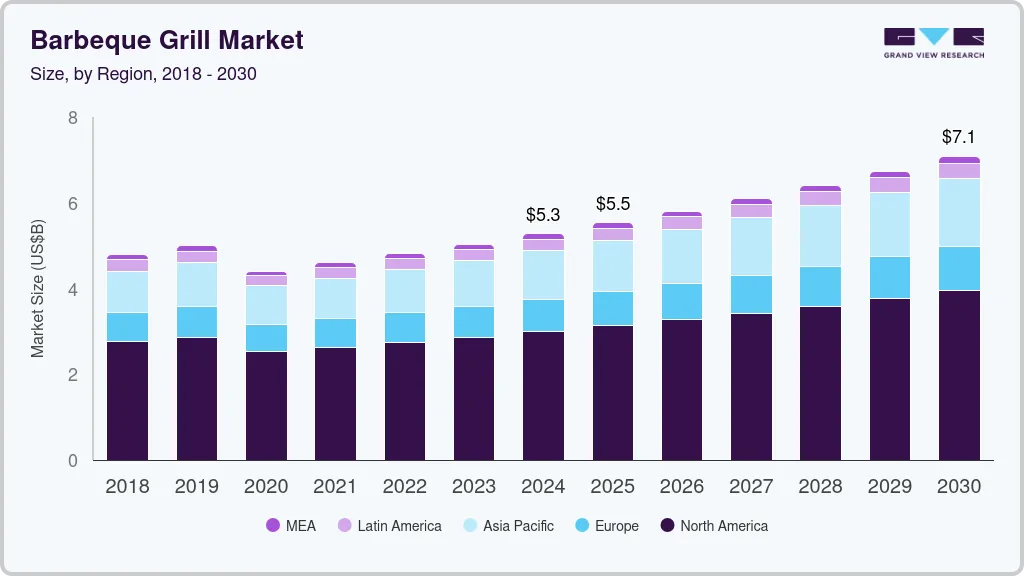
The global barbeque grill market size was valued at USD 5.28 billion in 2024 and is projected to reach USD 7.08 billion by 2030, growing at a CAGR of 5.1% from 2025 to 2030. Shifting lifestyle patterns and evolving eating habits among younger consumers, coupled with the rising popularity of outdoor events and social gatherings, have driven demand for slow-cooked barbecue dishes such as brisket, pork shoulder, and ribs.

The market’s growth trajectory is expected to continue in the coming years. Unlike many other product segments, the barbeque grill industry remained relatively resilient during the pandemic. As restaurants faced closures and restrictions, more consumers turned to home cooking. According to research by the Hearth, Patio & Barbecue Association (HPBA), published in November 2021, 38% of grill owners purchased a new grill within the past two years, and 27% of those cited increased home cooking during the pandemic as their reason for upgrading.

With changing consumer tastes, restaurants are innovating their barbeque menus beyond traditional offerings of chicken, seafood, and vegetables, now introducing items such as barbeque beetroot and sweet potato. The growing number of quick-service restaurants and barbeque eateries reflects consumers’ preference for convenient dining options. Young consumers, in particular, are increasingly exploring unique culinary experiences. The popularity of barbeque restaurants offering live cooking, buffet spreads, and vibrant dining atmospheres is further propelling the market’s expansion.

Key Market Trends & Insights

  • North America barbeque grill market accounted for a revenue share of 56.7% in 2024.
  • The U.S. barbeque grill market is expected to grow at a CAGR of 5.1% from 2025 to 2030.
  • Based on product, the gas barbeque grill segment dominated the market with a share of 55.18% in 2024.
  • Based on application, the commercial segment led the market in 2024.

Download a free sample PDF of the Barbeque Grill Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 5.28 Billion
  • 2030 Projected Market Size: USD 7.08 Billion
  • CAGR (2025–2030): 5.1%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Competitive Landscape

The global barbeque grill market is moderately consolidated, with key players such as Newell Brand Inc., Spectrum Brands, Inc., The Middleby Corporation, W.C. Bradley Co., Traeger Grills, LANDMANN, Weber-Stephen Products LLC, Transform Holdco LLC, Empire Comfort Systems, and RH Peterson Co. These companies benefit from established brand recognition and strong global distribution networks, enabling them to reach both regional and international markets.

Recent Developments

  • January 2023: Weber Inc. launched the LUMIN electric grill, designed for consumers with limited outdoor space. The model achieves temperatures exceeding 600°F (315°C) within 15 minutes.
  • April 2022: Napoleon introduced the Rogue EQ Connected Electric Grill Series, featuring app-controlled operation and a 7-inch LCD screen for temperature monitoring.
  • October 2021: Weber-Stephen began production of outdoor grills in Zabrze, Poland, aiming to improve logistics and meet growing European demand.
  • November 2021: Kenyon International, Inc. launched the G2 Grill, offering a 35% larger cooking surface than its previous portable models.

Key Companies Profiled

  • Newell Brand Inc.
  • Spectrum Brands, Inc.
  • The Middleby Corporation
  • W.C. Bradley Co.
  • Traeger Grills
  • LANDMANN
  • Weber-Stephen Products LLC
  • Transform Holdco LLC
  • Empire Comfort Systems
  • RH Peterson Co.

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The barbeque grill market is witnessing steady growth driven by changing consumer lifestyles, increased outdoor cooking trends, and the rising number of barbeque-themed restaurants. Innovation in product design, such as electric and app-controlled grills, is reshaping the consumer experience. Expanding restaurant chains and the growing culture of social dining are further supporting market expansion. Moreover, the emphasis on convenience, modern living, and experiential dining is expected to sustain long-term demand across both residential and commercial sectors.

Astaxanthin Market Growth Supported by Aquaculture and Animal Feed Demand

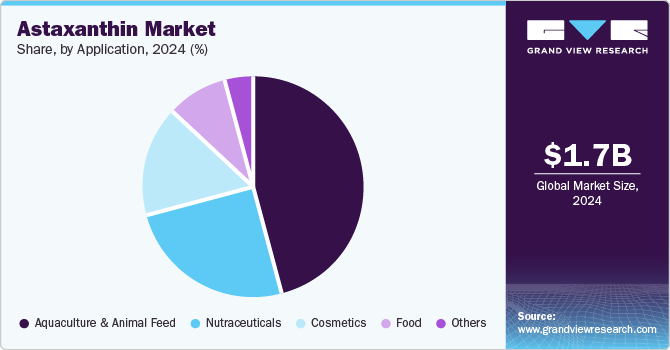
The global astaxanthin market size was estimated at USD 1.69 billion in 2024 and is anticipated to reach USD 3.89 billion by 2030, growing at a CAGR of 14.74% from 2025 to 2030. The increasing use of astaxanthin across industries such as aquaculture, animal feed, nutraceuticals, cosmetics, pharmaceuticals, and food & beverages is fueling market growth.

Astaxanthin is widely used as a feed ingredient for prawns and fish species such as salmon, trout, and ornamental fish to enhance coloration and boost commercial value. Its additional benefits include improved stress tolerance, reproductive capacity, immune gene expression, and disease resistance in aquatic species. Major manufacturers are focusing on product innovations and strategic collaborations to meet the growing demand in aquaculture.

The rising awareness of health and nutrition, coupled with the growing demand for dietary supplements due to escalating healthcare costs, is driving the nutraceutical and natural antioxidant markets. Leading producers are expanding their production capacities to meet increasing demand. For instance, in April 2023, Algalif announced progress on its 12,500 m² sustainable astaxanthin production facility in Iceland, a USD 30 million expansion expected to be fully operational by the end of 2023. Similarly, Beijing Gingko Group initiated a second expansion of its astaxanthin farm in 2022, while Algatech Ltd. tripled production for its FucoVital product to meet growing dietary supplement needs.

Key Market Trends & Insights

  • North America astaxanthin market accounted for the largest share of 35.27% in 2024.
  • The U.S. market is growing, driven by demand for natural antioxidants.
  • By source, the natural segment held the largest revenue share of 58.45% in 2024.
  • By product, dried algae meal or biomass accounted for the largest share of 25.12% in 2024.
  • By application, the aquaculture & animal feed segment held the largest share of 46.07% in 2024.

Download a free sample PDF of the Astaxanthin Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 1.69 Billion
  • 2030 Projected Market Size: USD 3.89 Billion
  • CAGR (2025–2030): 14.74%
  • North America: Largest market in 2024

Competitive Landscape

Key players in the market include Algatech Ltd, Cyanotech Corporation, and ALGAMO. The market is highly competitive, emphasizing sustainability, innovation, and product quality. Algatech Ltd. leads with sustainable algae cultivation and large-scale production, while Cyanotech Corporation is recognized for high-quality Hawaiian-sourced microalgae. Companies are prioritizing advanced cultivation techniques, expanding distribution networks, and forming strategic partnerships to enhance competitiveness.

Recent Developments

  • March 2024: Nutrex-Hawaii, Inc. (a subsidiary of Cyanotech Corporation) launched a sugar-free gummy version of its popular BioAstin Hawaiian Astaxanthin supplement, offering 12mg of natural astaxanthin per daily serving.
  • April 2023: Algalif reported progress on its 12,500 m² Iceland facility, a USD 30 million expansion aimed at scaling sustainable astaxanthin production.
  • April 2023: Algalíf and Divis Nutraceuticals launched an improved version of AstaBead, demonstrating continued innovation in astaxanthin applications for health and wellness.

Key Companies Profiled

  • Algatech Ltd
  • Cyanotech Corporation
  • Algalíf Iceland ehf
  • Beijing Gingko Group (BGG)
  • PIVEG, Inc.
  • Fuji Chemical Industries Co., Ltd
  • ENEOS Corporation
  • Atacama Bio Natural Products S.A.
  • E.I.D. – Parry (India) Limited
  • ALGAMO

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The astaxanthin market is poised for strong growth, supported by expanding applications in nutraceuticals, aquaculture, and cosmetics. Increasing consumer inclination toward natural and sustainable ingredients continues to boost industry investments and product innovations. Advancements in microalgae cultivation and large-scale production are further improving cost efficiency and output. Moreover, strategic collaborations and capacity expansions among key players are expected to enhance global supply capabilities and accelerate market expansion in the coming years.

Animal Vaccines Market Growth Supported by Rising Meat and Dairy Consumption

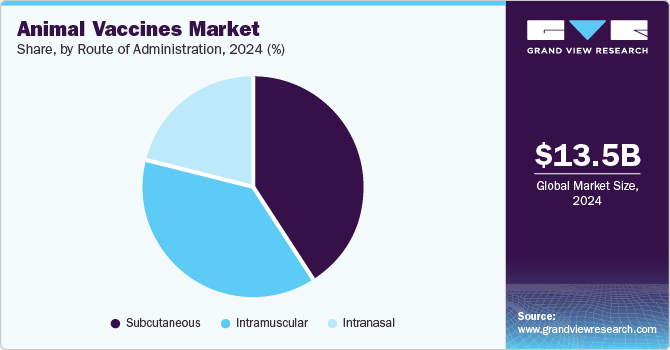
The global animal vaccines market size was estimated at USD 13.48 billion in 2024 and is projected to reach USD 22.95 billion by 2030, growing at a CAGR of 9.5% from 2025 to 2030. The rising incidence of cattle disease outbreaks and the expanding livestock population are key factors driving the global adoption of animal vaccines, particularly for ruminants such as cattle.

Additionally, increasing government initiatives are playing a vital role in promoting market growth. These programs are focused on enhancing animal welfare, ensuring food safety, controlling the spread of diseases, and advancing sustainable agriculture. For instance, in February 2025, Biovet—a division of Bharat Biotech Group—announced that its BIOLUMPIVAXIN vaccine for preventing lumpy skin disease in dairy calves and buffaloes was approved by India’s Central Drug Standard Control Organization (CDSCO).

Growing concerns over food security and the rising adoption of animal husbandry practices are fueling the demand for vaccines across the livestock population. Increasing consumption of animal-based products has boosted livestock production globally. According to OECD projections, global pork meat consumption is expected to rise from 112.58 megatons in 2022 to 127.27 megatons by 2029. Furthermore, cow milk accounts for over 80% of global milk production, with India and Pakistan projected to contribute over 30% of total output by 2029. These trends, coupled with the emergence of new animal diseases and technological advancements in vaccine development, are accelerating market growth.

The growing prevalence of zoonotic diseases, which can affect both animals and humans, is another major market driver. For instance, in February 2025, a new strain of H5N1 avian flu was detected in six dairy herds in Nevada, according to the U.S. Department of Agriculture. This has heightened the need for H5N1-specific vaccines and emphasized the urgency of developing rapid and effective immunization programs. The situation underscores the importance of enhanced biosecurity protocols and comprehensive vaccination strategies to protect animal and public health.

Key Market Trends & Insights

  • North America dominated the market, accounting for a revenue share of over 28% in 2024.
  • The U.S. animal vaccines market is witnessing significant growth.
  • By product, the attenuated live vaccines segment dominated with a revenue share of over 37.0% in 2024.
  • By animal type, the livestock segment held the highest revenue share in 2024.
  • By distribution channel, the hospital/clinic pharmacy segment led the market in 2024.

Download a free sample PDF of the Animal Vaccines Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 13.48 Billion
  • 2030 Projected Market Size: USD 22.95 Billion
  • CAGR (2025–2030): 9.5%
  • North America: Largest market in 2024

Competitive Landscape

The market is highly competitive, comprising both large multinational players and regional manufacturers. Key competitive factors include the rapid adoption of preventive veterinary injections and government-supported vaccine procurement programs. To maintain market share and expand product portfolios, major companies are engaging in mergers, acquisitions, partnerships, and new product launches.

For example, in February 2021, Ceva partnered with the French National Research Institute for Agriculture, Food, and Environment (INRAE) to strengthen R&D in preventing infectious animal diseases and improving overall animal health.

Recent Developments

  • February 2025: Zoetis received conditional approval from the USDA CVB for its H5N2 Avian Influenza killed virus vaccines.
  • February 2025: Medgene and Elanco collaborated to commercialize Elanco’s HPAI vaccine platform for dairy cattle in the U.S.
  • August 2022: Zoetis expanded its poultry portfolio by launching the Poulvac Procerta HVT-IBD vaccine for protection against Infectious Bursal Disease (IBD).
  • January 2022: Boehringer Ingelheim partnered with MabGenesis to develop novel canine monoclonal antibodies.
  • November 2021: Ceva invested in a new cryogenic storage facility in Monor, expanding its European vaccine production capacity.

Key Companies Profiled

  • Zoetis
  • Merck & Co., Inc.
  • Boehringer Ingelheim Animal Health
  • Elanco
  • Virbac
  • Phibro Animal Health Corporation
  • Calier
  • Ceva

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global animal vaccines market is poised for robust growth, supported by rising livestock populations, expanding disease prevention programs, and growing awareness of zoonotic threats. Ongoing R&D initiatives and government-backed vaccination campaigns are strengthening market foundations. Increasing technological innovations in vaccine formulation are enhancing effectiveness and accessibility. As demand for animal-based products continues to surge, the market is expected to maintain steady momentum through the forecast period.

Air Purifier Market Witnesses Rapid Expansion Amid Rising Pollution

The global air purifier market size was estimated at USD 16,935.1 million in 2024 and is projected to reach USD 30,078.4 million by 2033, growing at a CAGR of 6.6% from 2025 to 2033. Rising air pollution levels and increasing awareness of indoor air quality and health are the key factors driving market growth.

Rapid urbanization and industrialization have led to higher levels of airborne contaminants, encouraging consumers to invest in effective air purification solutions. Technological innovation continues to shape market dynamics, with manufacturers introducing smart air purifiers equipped with HEPA filtration, app-based control, and real-time air quality monitoring. These advancements improve convenience and efficiency, appealing to tech-oriented users. Furthermore, the integration of AI and IoT into air purification systems is fueling demand in smart homes and offices, broadening the market’s consumer base.

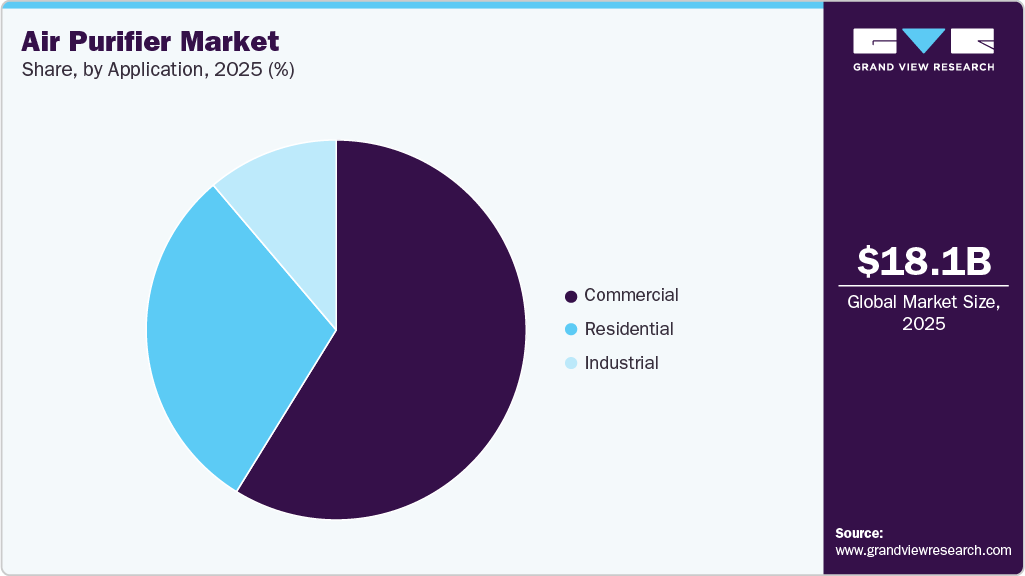
The air purifier industry has seen a noticeable shift toward residential end users. Growing health awareness and the pursuit of cleaner indoor environments are prompting more households to adopt air purifiers. While commercial and industrial sectors remain important, the increase in residential adoption highlights changing consumer preferences. In response, manufacturers are developing compact, energy-efficient models tailored for home use.

Key Market Trends & Insights

  • Asia Pacific dominated the air purifier market with the largest revenue share of 39.5% in 2024.
  • The China air purifier market accounted for over 40.0% share in Asia Pacific, driven by persistent air quality challenges and a growing health burden.
  • By technology, the activated carbon segment is projected to grow at a CAGR of 7.7% from 2025 to 2033 in terms of revenue.
  • By application, the commercial segment is expected to expand at a CAGR of 7.2% from 2025 to 2033.
  • By coverage range, the below 250 Sq. Ft. segment is anticipated to grow at a CAGR of 7.3% from 2025 to 2033.
  • By sales channel, the online segment is projected to record a CAGR of 7.3% from 2025 to 2033.
  • By type, the standalone/portable segment is expected to grow at a CAGR of 7.0% from 2025 to 2033.

Download a free sample PDF of the Air Purifier Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2024 Market Size: USD 16,935.1 Million
  • 2033 Projected Market Size: USD 30,078.4 Million
  • CAGR (2025–2033): 6.6%
  • Asia Pacific: Largest market in 2024

Competitive Landscape

Some of the key players operating in the market include Alfa Laval, Danfoss, and Kelvion Holding GmbH.

  • Honeywell International, Inc. – A leading global technology company offering a diverse range of air purifiers for residential, commercial, and industrial applications. Known for integrating smart features such as HEPA filters and real-time air quality monitoring, Honeywell maintains a strong market presence supported by brand trust and extensive distribution networks. Its products are particularly popular in North America and Asia, serving both general consumers and specialized environments like healthcare.
  • IQAir – A premium air quality technology firm specializing in high-performance purifiers and monitoring systems. It is recognized for medical-grade products widely used in hospitals, laboratories, and polluted regions. IQAir dominates the luxury and professional segments of the market, known for its advanced filtration technology and accurate air quality data, with strong footholds in Asia and Europe.

Recent Developments

  • January 2024: COWAY CO., LTD. launched Airmega 100, featuring 360° air intake and a 3-stage HEPA filtration system that purifies up to 810 sq. ft. per hour. It includes a real-time air quality indicator, energy-saving mode, auto operation, and precision particle sensors.
  • February 2023: The company introduced a carbon air purifier utilizing UV technology to enhance indoor air quality. This system removes odors, gases, and volatile organic compounds (VOCs) while reducing microbial growth, including viruses and bacteria, on evaporator coils.

Key Companies Profiled

  • IQAir
  • Honeywell International, Inc.
  • LG Electronics
  • Unilever PLC
  • Koninklijke Philips N.V.
  • Hamilton Beach Brands, Inc.
  • Panasonic Corporation
  • Whirlpool Corporation
  • Carrier

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global air purifier market continues to evolve as consumers prioritize healthier indoor environments and air quality awareness grows. Advancements in smart technologies, AI integration, and filtration efficiency are reshaping the competitive landscape. The shift toward residential adoption highlights a major transformation in consumer demand patterns. With strong innovation and regional expansion, the market is poised for sustained growth throughout the forecast period.

3D Printing Market Witnesses Surge in Industrial Automation and Prototyping

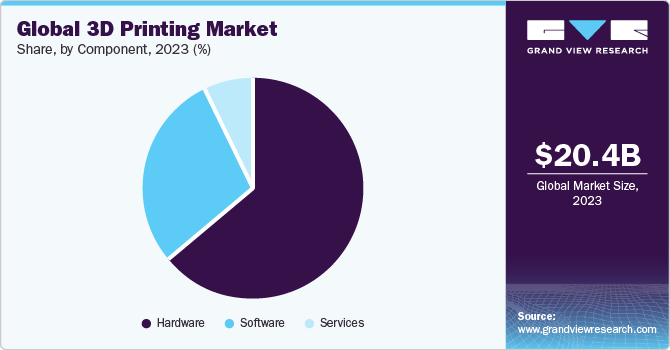
The global 3D printing market was valued at USD 20.37 billion in 2023 and is projected to reach USD 88.2 billion by 2030, growing at a CAGR of 23.5% from 2024 to 2030. Market growth is driven by aggressive R&D activities in three-dimensional printing and the increasing demand for rapid prototyping across industries such as healthcare, automotive, and aerospace & defense.

3D printing, often referred to as additive manufacturing (AM) in industrial contexts, involves the layer-by-layer addition of material to create a 3D object from a digital design. The process begins with the selection of an appropriate technology, followed by deployment across multiple industries through installation, consulting, and customer support services, as well as licensing and patent management.

Manufacturers are leveraging 3D printing for prototyping, structural design, product modeling, and faster time-to-market, which has significantly reduced production costs. This, in turn, enables them to deliver high-quality, cost-effective products, fueling market adoption in the coming years.

However, misconceptions among small and medium enterprises (SMEs) regarding the cost and value of prototyping remain a challenge. Many SMEs view prototyping as an expensive pre-manufacturing step rather than a strategic investment, hindering broader adoption. Additionally, the lack of technical expertise and standardized process controls continue to restrain market growth.

Key Market Trends & Insights

  • North America led the global market, accounting for over 33% of total revenue in 2023.
  • The U.S. market is expanding rapidly, supported by the technology’s ability to enable quick product development and rapid prototyping.
  • By printer type, the industrial printer segment dominated the market, contributing over 76% of revenue in 2023.
  • By technology, stereolithography accounted for over 10% of total market share in 2023.
  • By software, the design software segment led with a 36% revenue share in 2023.

Download a free sample PDF of the 3D Printing Market Intelligence Study by Grand View Research.

Market Size & Forecast

  • 2023 Market Size: USD 20.37 Billion
  • 2030 Projected Market Size: USD 88.2 Billion
  • CAGR (2024-2030): 23.5%
  • North America: Largest market in 2023
  • Asia Pacific: Fastest growing market

Competitive Landscape

The global 3D printing market is moderately consolidated, with key players focusing on technological innovation, partnerships, and expanding industrial applications.

Leading Companies

  • 3D Systems, Inc. – A U.S.-based firm offering a wide range of 3D printers, materials, software, scanners, and virtual surgical simulators. The company supports sectors such as aerospace, automotive, healthcare, education, and entertainment, helping clients reduce lead times and eliminate costly tooling.
  • Materialise (Belgium) – Specializes in additive manufacturing software and printing services, serving industries including healthcare, aerospace, automotive, consumer goods, and art & design.

Emerging Participants

  • Made In Space, Inc. (U.S.) – Pioneers space-based 3D printing solutions for microgravity and vacuum environments.
  • Voxeljet AG (Germany) – Focuses on industrial 3D printing systems and on-demand production of models and molds for metal casting, leveraging powder binding and additive manufacturing technologies.

Key Companies Profiled

  • 3D Systems, Inc.
  • 3DCeram
  • Arcam AB
  • Autodesk, Inc.
  • Canon, Inc.
  • Dassault Systèmes
  • EnvisionTec, Inc.
  • EOS GmbH (Electro Optical Systems)
  • ExOne

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The 3D printing market is set to experience exponential growth through 2030, supported by rapid innovation, industrial adoption, and expanding use cases across key sectors. As the technology matures and cost barriers decline, additive manufacturing is poised to become a mainstream production technology globally.

Feeding the Blue Revolution: The Aquafeed Market Takes Center Stage

As wild catches level off, farmed seafood is filling the gap, and every farmed fish and shrimp depends on feed. That makes aquafeed one of t...