Plastic Processing Machinery Industry Top Players Analysis: Haitian International and Milacron

Plastic Processing Machinery Industry Data Book Covers Plastic Injection Molding Machine, Plastic Extrusion Machinery, and Plastic Blow Molding Machine Market

The global Plastic Processing Machinery Industry size generated over USD 21.13 billion in 2022 and is expected to grow at a significant CAGR over the forecast period.

Grand View Research’s plastic processing machinery industry data book is a collection of market sizing information & forecasts, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports and summary presentations on individual areas of research.

Plastic Injection Molding Machine Market Insights

The global plastic injection molding machine market size was estimated at USD 11.7 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 4.8% from 2023 to 2030. The adoption of injection molded components is anticipated to increase across a variety of industries, including automotive, electronics, consumer products, packaging, and others. Manufacturers are focusing on the development of plastic injection molding machines, which can bring down production costs, provide flexibility in production, reduce scrap, reduce maintenance, shorten production cycle time, and are efficient. New plastic injection molding processes such as foam injection molding, co-injection molding, gas-assisted injection molding, and multiple component injection molding are creating high demand for injection-molded materials. This technological advancement has propelled the use of plastic injection molding machines in various industries such as medical, electronics, construction, aerospace, and defense.

Electric plastic injection molding machines are highly efficient and require less start-up time and run-time compared to that of hydraulic injection molding machines. Electric plastic injection molding machines use 50% to 75% less energy on average than their hydraulic equivalents because they are tighter, faster, and cleaner, and have a repeatable process production equipment with little waste. Moreover, factors such as quiet operation, energy savings from 30% to 70%, less wastage of material, and low requirements of power are expected to boost the demand for electric injection molding machines.

Factors such as easy access to new and advanced technologies in the EV industry, availability of a highly skilled workforce, presence of advanced processing capabilities, and increased R&D initiatives have boosted the penetration of electric vehicles in the U.S. The favorable government regulations and initiatives in the form of tax rebates and subsidies have further fueled the demand for electric vehicles in the U.S. Increasing demand for plastic injection molded components in conventional and electric vehicles for various interior and exterior parts are expected to augment the plastic injection molding market growth in the U.S.

Growing demand for on-the-go packaged products owing to increasing purchasing power and busy lifestyle in the U.S. is expected to have a positive impact on the packaging industry growth in the country. A plastic injection molding machine is used for manufacturing various packaging products such as containers, bottles, caps & closures, and covers. Growth in the packaging industry coupled with the rising adoption of plastic injection molding machines for manufacturing packaging products is expected to drive market growth in the country.
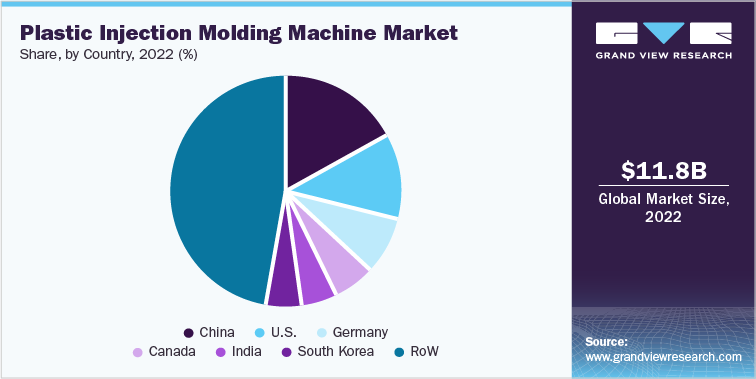
Plastic Injection Molding Machine Market, by Country, 2022 (%)

Order your copy of the Free Sample of “Plastic Processing Machinery Industry Data Book - Plastic Injection Molding Machine, Plastic Extrusion Machinery, Plastic Blow Molding Machine Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Plastic Blow Molding Machine Market Insights

The global plastic blow molding machine market size was estimated at USD 2.97 billion in 2022 and is expected to grow at a compounded annual growth rate (CAGR) of 3.9% from 2023 to 2030. The medical industry's growing need for blow-molded plastic items and the growing significance of plastic recycling is predicted to boost market expansion throughout the projected period. Plastic blow molding machines are widely used for different applications such as concrete forms of all shapes and sizes, panels, barricades, and traffic markers in the building & construction industry. Industries such as construction, packaging, and automotive are the industries propelling the demand for plastic molding machines. Plastic blow molding machines are incorporating robotics, artificial intelligence (AI), and sensor technologies to increase productivity, decrease human error, and improve efficiency. Automation of plastic blow molding machines is anticipated to increase output capacity and reduce costs, contributing to the market's estimated revenue growth.

The demand for blow-molded plastics across the U.S. is majorly generated by the expanding automotive industry, on account of the popularity of electric vehicles and the rise in the number of construction activities. For instance, the U.S. witnessed a growth in electric car sales from 1.0 million in 2022 to 1.6 million in 2023. The rising demand for electric vehicles is expected to significantly boost the demand for blow-molded plastic products, thereby driving market growth.

Contrary to most industries, COVID-19 has positively impacted the market as demand for plastic blow molding machines surged in response to the growing demand for plastic packaging for sanitizers, cleaning supplies, and beverages like water. For instance, a Spanish supplier of plastics machinery claimed that in June 2020, production in the bottle and bottling sector was 100% more than typical.

The rising demand for plastic containers is driving the demand for plastic molds, which will ultimately help the industry in the U.S. to flourish. For instance, Meredith-Springfield Associates Inc. in August 2021 announced the expansion of its manufacturing facility by 5,000 square feet. The company also installed two extrusion blow molding machines and one injection stretch blow molding equipment.

The development of the market is anticipated to be aided by a focus on recycling plastics, offsetting the detrimental effects of the prohibition of single-use plastic on the blow molding industry. For instance, in November 2020, Austria implemented mandatory targets by making a beverage reuse quota of 25% by 2025 compulsory in their Waste Management Act. With this, it became the first European country to do so.

Go through the table of content of Plastic Processing Machinery Industry Data Book to get a better understanding of the Coverage & Scope of the study

Plastic Processing Machinery Industry Data Book Competitive Landscape

The manufacturers of plastic processing machinery adopt several strategies, including acquisitions, mergers, joint ventures, new product developments, and geographical expansions, to enhance their market penetration and cater to the changing technological requirements of various end-users such as automotive, consumer goods, packaging, and electronics, among others. Strategies adopted by the companies usually include product portfolio expansion, collection network expansion, and geographic network expansion.

Key players operating in the Plastic Processing Machinery Industry are:

  • Arburg GmbH + Co KG
  • Haitian International Holdings Limited
  • Milacron
  • Nissei Plastic Industrial Co., Limited
  • Engel Austria GmbH

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S. based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Healthcare Information Systems Industry: Key Company Market Share Analysis

Healthcare Information Systems Industry Data Book Covers Hospital Information Systems, Pharmacy Automation Systems, Laboratory Informatics, and Revenue Cycle Management Market

The global healthcare information systems industry size generated over USD 406.4 billion in 2022 and is expected to grow at a CAGR of 13.3% over the forecast period.

Grand View Research’s Healthcare Information Systems Industry databook is a collection of market sizing & forecasts insights, market dynamics & trends, opportunity assessment, regulatory & technology framework, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses studies. Within the purview of the databook, such information is systematically analyzed and provided in the form of summary presentations and detailed outlook reports on individual areas of research.The following data points will be included in the final product offering in four reports and one sector report overview.

Hospital Information Systems Market Insights

The global hospital information system market size was valued at USD 118.2 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 17.7% from 2023 to 2030. Hospital Information Systems (HIS) help healthcare facilities to improve their operational outcomes and reduce the workload on the staff, which is expected to boost industry growth. Various initiatives undertaken by governments across the globe and rising demand for the deployment of advanced IT solutions in hospitals for enhanced operational efficiency are some of the key factors that are expected to boost the adoption of HIS. The need to curb healthcare expenditures due to hospital workflow inefficiencies is also anticipated to boost the adoption of these systems globally. Thus, the growing demand for effective clinical outcomes and reduced healthcare costs are some of the key factors that are boosting the adoption of HIS in developed and emerging economies.

The developed and developing economies are struggling to provide high care delivery standards that are quality oriented with minimum medical errors and are cost-effective. The implementation of these systems helps providers offer improved patient outcomes and streamline their workflows, which is expected to further drive the demand for the systems.

Moreover, these systems offer cost-effective services and help reduce resource wastage. The rising penetration of technologically advanced solutions is also expected to drive industry growth. The rising implementation of healthcare IT services and solutions by hospitals to provide enhanced care to patients at reduced costs combined with the increasing need to upgrade the existing systems is likely to be a key driver for the industry growth. Moreover, constant upgrades in the healthcare and IT infrastructure along with increased adoption of cloud-based services in healthcare facilities are expected to drive the market further.

There are stringent regulatory norms, which ensure safe and secure storage of patient data, confidentiality, user-level authorization, traceability of information, and mitigation of cyber security threats. Thus, healthcare facilities are switching from on-premise software to cloud-based information systems to avoid security breaches and maintain data security. The pandemic had a positive impact on the industry. Factors, such as increased adoption of the HIS to reduce the workload on the already strained healthcare professionals contributed to the industry growth. Moreover, the high adoption of IT solutions in healthcare facilities further boosted the demand for these systems.

Order your copy of the Free Sample of “Healthcare Information Systems Industry Data Book - Hospital Information Systems, Pharmacy Automation Systems, Laboratory Informatics and Revenue Cycle Management Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

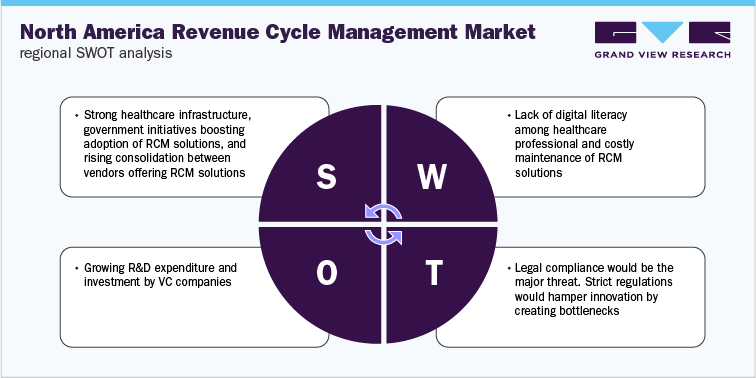
North America Revenue Cycle Management Market, Regional SWOT analysis

Revenue Cycle Management Market Insights

The global revenue cycle management market size was valued at USD 269.2 billion in 2022 and is projected to expand at a compound annual growth rate (CAGR) of 11.2% from 2023 to 2030. The rapidly growing era of digitalization of healthcare is driving the demand for advanced revenue cycle management (RCM) solutions. The growing number of multiple data siloes and unorganized workflows in healthcare settings is paving a path for market development and growth. RCM is a combination of third-party payers, payment models, guidelines, and codes. A practice’s existence depends upon obtaining the right assets.

Due to the numerous benefits, available healthcare facilities are readily outsourcing RCM solutions and services. According to a survey conducted by CWH Advisors and sponsored by CareCredit, over 61% of healthcare providers are interested in outsourcing their RCM processes to an external party. The growing adoption rates are anticipated to propel market growth over the forthcoming years. One of the major challenges faced in adopting and implementing RCM software solutions is the lack of proper reimbursement regulations with respect to insurance and other formalities. The existing reimbursement policy gaps between public and private insurers are restraining the growth of the RCM market.

The ongoing Covid-19 pandemic had an unprecedented and unexpected impact on majority of the healthcare sectors and brought in significant transformations to the normal functioning of healthcare systems. Healthcare providers and healthcare payers struggled through several challenges impacting their revenue earnings and inpatient volume. Medical billing complexity and rising healthcare costs created a drastic rise in demand for outsourcing RCM solutions across the globe. The surge in demand for advanced and innovative RCM solutions drove key participants to developed value-added features such as payer connect, remote coding services, reporting, analytics, and audit and compliance to improve revenue generation and productivity.

Go through the table of content of Healthcare Information Systems Industry Data Book to get a better understanding of the Coverage & Scope of the study

Healthcare Information Systems Industry Data Book Competitive Landscape

Mergers & acquisitions, product launches, and collaborations & partnerships are continuously adopted by these companies to maintain a competitive edge in the market.

Key players operating in the Healthcare Information Systems Industry are:

  • McKesson Corporation
  • Cerner Corporation
  • athenahealth, Inc.
  • Allscripts Healthcare, LLC
  • Medidata Solutions Inc.

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S. based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Biobanking Industry: Biobanking and Repository Services Segment Accounted for The Largest Revenue Share in 2022

Biobanking Industry Data Book Covers Biobanks, Cell Banking Outsourcing, Cord Blood Banking Services, DNA & RNA Banking Services Market

Grand View Research’s Biobanking Industry databook is a collection of market sizing & forecasts insights, market dynamics & trends, opportunity assessment, regulatory & technology framework, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses studies. Within the purview of the databook, such information is systematically analyzed and provided in the form of summary presentations and detailed outlook reports on individual areas of research.The following data points will be included in the final product offering in four reports and one sector report overview.

Biobanks Market Insights

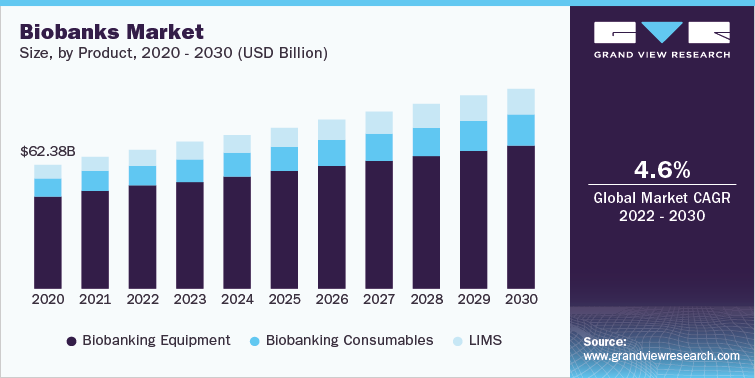
The global biobanks market size was valued at USD 66.66 billion in 2021 and is expected to grow at a compound annual growth rate (CAGR) of 4.6% from 2022 to 2030. High investments in the R&D of advanced therapies, such as regenerative medicine, personalized medicine, and cancer genomic studies, are driving the space. Moreover, the onset of COVID-19 has put biobanks at the forefront of the pandemic control measures, resulting in the organic revenue growth of the market. The COVID-19 outbreak had a major influence on the biobanking industry. Biobanking is important for the diagnosis & production of medicines for a variety of disorders. International initiatives to produce vaccines and other medicines to prevent the spread of the virus have been urgently needed.

The collection, processing, and analysis of patient samples are at the frontline of this crisis. For example, the Health Minister announced EUR 2 million in financing for the National Irish COVID-19 Biobank (NICB) in a July 2021 update from the Government of Ireland. The NICB has become a critical part of Ireland’s COVID-19 pandemic response. According to a February 2021 release, the Sample Collection Database was designed by the SciLifeLab Data Centre in partnership with Biobank Sweden and the research area ‘Biobanks for COVID-19’ of the SciLifeLab & KAW National COVID-19 research program.

Furthermore, Tulane University announced a new COVID-19 biobank containing blood & cell samples from survivors in July 2021 to aid researchers in determining why some people heal rapidly while others have long-term effects. As a result, such activities show that the outbreak of the pandemic boosted the demand for biobank services, benefiting the global economy. The increasing popularity of precision/personalized medicine and genetic testing has been a key driver of the market. Biobanks have been playing a significant role in biomedical research. Over the past few decades, there have been several advances in platforms and tools used in genetic studies.

This has led to an increase in demand for biospecimens from clinical labs to develop assays for genetic testing. Collaborations between private and public institutions in biobanking have played a crucial role in market progression. Digitalization, precision medicine, and virtualization are rapidly changing the biobanking industry through the development of novel methods and concepts of synergies initiated by public and private organizations. Companies across all fields are partnering with biobanks, which accelerates market revenue. For instance, Illumina partnered with four institutions - the University of Colorado at Denver, Vanderbilt University, Montreal Heart Institute University, and Partners HealthCare - to genotype their bio-samples for R&D activities.

Biobanks Market Size, by Product, 2020-2030 (USD Billion)

Order your copy of the Free Sample of “Biobanking Industry Data Book - Biobanks, Cell Banking Outsourcing, Cord Blood Banking Services, DNA & RNA Banking Services Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Cell Banking Outsourcing Market Insights

The global cell banking outsourcing market size was computed at USD 9.86 billion in 2021 and is anticipated to grow at a compound annual growth rate (CAGR) of 16.39% from 2022 to 2030. Rising advancement of the cryopreservation and cell banks preparation methodologies, increasing adoption of stem cell therapies, and growing demand for monoclonal antibodies along with effective biopharmaceuticals are the major factors, driving growth of the market. According to CellTrials.org global enrolments of new trials in advanced cell therapy were up almost 30% in the first quarter of 2020. Most of the rise can be associated to cell therapy efforts for treating COVID-19, and over half of those trials for COVID-19 employ umbilical cord MSCs. Hence, the pandemic has created a new market for those companies which are engaged in the manufacturing of MSCs products from donated birth tissues, hence may contribute to the market growth, post pandemic.

Moreover, many of these manufacturers have applied for COVID-19 EUA from the FDA and are partnering with local hospitals to treat COVID-19 patients. For instance, in September 2021, Life Cell’s Mesocel received approval for a clinical trial from DCGI; therapy derived MSC of the umbilical cord tissue set to treat patients with pneumonia, COVID-19, and acute respiratory distress.

The presence of favorable government initiatives for the development of stable cell lines, as well as the introduction of new technology for cell line storage and characterization, are among the critical factors expected to drive market growth in the forecast period. For instance, In December 2021, ‘Vineti’ and ‘Be The Match BioTherapies’ collaborated to develop an integrated supply chain management solution for gene and cell therapy. Such initiatives and collaborations are anticipated to drive growth during the forecast period.

Furthermore, the key players in the market are also involved in research collaborations, in order to reprogram newborn stem cells from umbilical cord blood as well as umbilical cord tissue into iPSCs. These collaborations are also expected to drive the growth of market over the forecast period. For instance, In May 2021, Opsis Therapeutics, FUJIFILM Cellular Dynamics, and Blue Rock Therapeutics entered into strategic research and development to create cell therapies to cure eye diseases. These companies will use their expertise to develop off-the-shelf iPSCs to cure ocular diseases.

Go through the table of content of Biobanking Industry Data Book to get a better understanding of the Coverage & Scope of the study

Biobanking Industry Data Book Competitive Landscape

The market players are involved in the manufacturing of various products associated with cell banking industry including reagents, consumables, and equipment along with certain services. To maintain a significant share in the market, key participants are undertaking various initiatives and implementing business strategies, such as product launches, product portfolio expansion, reinforcement and stabilizing the distribution network, and manufacturing capacity expansion and geographic reach expansion through acquisitions, collaborations, and partnership.

Key players operating in the Biobanking Industry are:

  • Danaher Corporation
  • Tecan Trading AG.
  • Thermo Fisher Scientific
  • Qiagen
  • Merck KGaA

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S. based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Innerwear Industry: Technology Trends and Restraint Analysis, 2023 - 2030

Innerwear Industry Data Book Covers Top Innerwear, Bottom Innerwear and Thermals & Baselayers Market

The global Innerwear Industry was estimated at USD 203.72 billion in 2022 and is anticipated to increase at a significant CAGR of 5.4% from 2023 to 2030.

Grand View Research’s innerwear industry data book is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research.

Top Innerwear Market Insights

The global Top Innerwear Market size was estimated at USD 82.46 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.0% from 2023 to 2030. Top innerwear, such as bralettes and camisoles, are often designed to be stylish and can double as outerwear, giving people the option to showcase their innerwear as part of their outfits. Top innerwear has gained popularity and wider acceptance in recent years. This shift can be attributed to changing fashion trends, increased body positivity and inclusivity, and the desire for comfort and versatility in clothing choices.

The acceptance of top innerwear as a fashion statement is also reflected in the rise of lingerie-inspired fashion trends, and this trend has been seen on fashion runways, in street style, and on social media platforms, further contributing to the normalization of wearing innerwear as outerwear. The availability of a wider range of sizes, styles, and designs has made top innerwear more accessible to individuals with different body types.

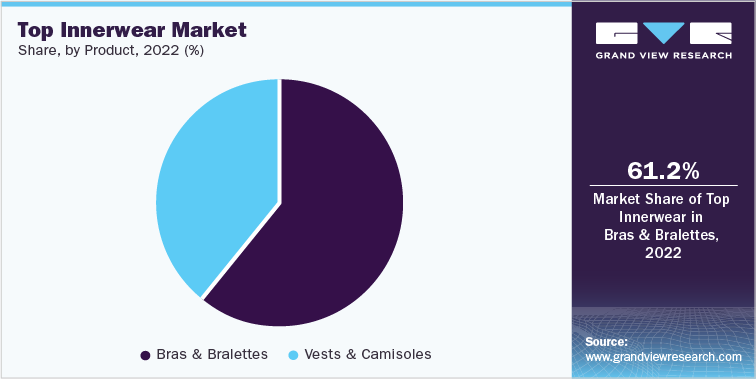
Bras and bralettes are designed to provide support and comfort to the breasts. They typically feature underwire or other supportive structures that help lift and shape the breasts, reducing strain on the back and shoulders. The use of soft and breathable materials further improves comfort. Intimate bras are designed to make the wearer feel confident, attractive, and comfortable in intimate settings. Intimate bras are available in various sizes, styles, and price ranges. This, coupled with a growing emphasis on self-care and personal style, has contributed to the widespread popularity of intimate bras among women of all ages.

Top Innerwear Market Share, by Product, 2022 (%)

Bottom Innerwear Market Insights

The global Bottom Innerwear market size was estimated at USD 102.91 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.4% from 2023 to 2030. Bottom innerwear held the largest share of the overall innerwear market. Bottom innerwear refers to undergarments worn on the lower half of the body, including underwear, shapewear, and other types of intimate apparel. Bottom innerwear has gained significant popularity and attention among users in recent years. The focus on comfort, functionality, and personal style has led to an increased interest in different types of bottom innerwear. Brands have also expanded their offerings to cater to a broader range of body types, providing more inclusive options and styles.

Panties come in a wide range of styles, including briefs, bikinis, hipsters, thongs, and boyshorts. Each style differs based on coverage, rise, and fit. It allows individuals to choose the style that best suits their comfort and aesthetic preferences. Leggings are form-fitting, stretchy bottoms that cover the legs and are typically made of spandex or a blend of spandex and other fabrics. Both panties and leggings are popular bottom innerwear choices that offer comfort and style. Panties are primarily underwear designed for coverage and hygiene, while leggings provide coverage for the legs and can be worn as standalone bottoms or for layering.

Order your copy of the Free Sample of “Innerwear Industry Data Book - Top Innerwear, Bottom Innerwear and Thermals & Baselayers Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Thermals and Baselayers Market Insights

The global Thermals and Baselayers Market size was estimated at USD 18.35 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 7.3% from 2023 to 2030. Thermals and base layers are specialized types of innerwear designed to provide insulation and regulate body temperature in cold weather or during outdoor activities.

Thermals are typically made from thermal fabrics such as Merino wool, synthetic blends, or cotton blends, whereas base layers are generally made from technical fabrics like polyester, nylon, or Merino wool. Both thermals and base layers play an essential role in providing comfort and regulating body temperature in cold weather or during outdoor activities. They provide insulation, moisture management, and breathability to ensure optimal performance and comfort.

Go through the table of content of Innerwear Industry Data Book to get a better understanding of the Coverage & Scope of the study

Innerwear Industry Data Book Competitive Landscape

The manufacturers in the innerwear market aim to achieve optimum business growth and a strong market position through the implementation of various strategies such as acquisitions, new product launches, collaborations, and strengthening of distribution networks in the global as well as regional markets. Innerwear manufacturers aim to strengthen their market positions by expanding their customer base through diversification of their product portfolios, incorporating a wide range of innerwear. Thus, players are aiming to achieve business growth in the regional market through product launches, mergers, acquisitions, and other strategic initiatives.

Key players operating in the Innerwear Industry are:

  • Hanesbrands Inc.
  • Berkshire Hathaway Inc. (Fruit of the Loom)
  • PVH Corp.
  • Jockey International Inc.
  • Minus33 Merino Wool Clothing

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S. based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Insulation Industry Top Players Analysis: Armacell, Lydall, Inc, and Kingspan Group

Insulation Industry Data Book Covers Board Insulation, Blanket Insulation, Pipe Insulation, and Others (Foam) Insulation Market

The global Insulation Industry was estimated at USD 53.34 billion in 2022 and is anticipated to increase at a significant CAGR of 4.7% from 2023 to 2030.

Grand View Research’s insulation sector database is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research.

Board Insulation Market Insights

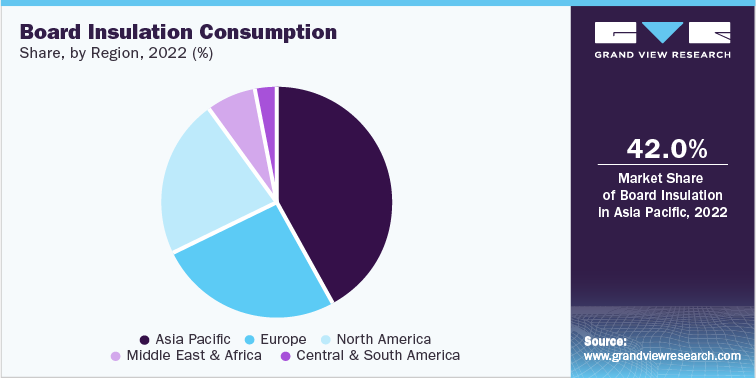
The global board insulation market size was estimated at USD 12.8 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 3.6% from 2023 to 2030. This growth can be attributed to the increased focus on energy efficiency and the growing demand for sustainable building materials across the globe. As the cost of energy increases, there is a growing demand for insulation materials that aid in reducing energy consumption. Board insulation is a highly effective way to insulate buildings and this trend is expected to grow at a significant pace during the forecast period.

Rigid board insulation is highly effective at insulating buildings to curb the energy requirements for heating and cooling. It is effectively easy to install, and the operating cost makes it an ideal choice for most of the building contractors. This is particularly important in cold climates, where it is important to minimize heat loss. As a result, the demand for boards from the building & construction industry is expected to increase during the forecast period.

Manufacturers of board insulation have partnerships with merchants and distributors to ensure the timely supply of boards. Some of the major manufacturers are involved in offering new product launches to increase their market share. Strategic partnerships as well as collaborations, are some of the strategies adopted by major manufacturers to gain competitive advantages.

Board Insulation Consumption Share, by Region, 2022 (%)

Blanket Insulation Market Insights

The global blanket insulation market size was estimated at USD 14.5 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.6% from 2023 to 2030. This growth can be attributed to the increasing use of insulation in building & construction and industrial applications. Blanket insulation can also be utilized for acoustic fabrication in warehouses and other commercial buildings, as well as thermal insulation in interior spaces. The construction industry is expected to reach about USD14 trillion by the end of 2030 due to increasing urbanization and increased spending on housing and remodeling across the globe. Owing to the increase in the use of blankets across the construction sector is expected to drive the market during the forecast period.

The use of blanket insulation generates cheaper energy bills, and year-round comfort by assisting with low maintenance and a comfortable temperature. Additionally, noise reduction from outside and between floors and rooms makes it an ideal choice of insulation for both commercial and residential spaces. Sustainability, comfortability, and low maintenance are some of the major factors fueling the blanket insulation demand throughout the forecast period.

Major manufacturers have partnerships with merchants and distributors to ensure smooth supply throughout the U.S. Manufacturers in the U.S. adopt mergers & acquisitions strategies to boost their overall market share and have a competitive advantage. In addition, manufacturers often have agreements with raw material suppliers to ensure timely supply to cater to the demands of customers.

Order your copy of the Free Sample of “Insulation Industry Data Book - Board Insulation, Blanket Insulation, Pipe Insulation, and Others (Foam) Insulation Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Pipe Insulation Market Insights

The global pipe insulation market size was estimated at USD 17.71 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.3% from 2023 to 2030. Rising awareness pertaining to energy conservation among consumers is expected to drive the market over the forecast period.The market witnessed a severe downfall in investments in the industrial sector owing to the pandemic, thereby impacting overall growth. In addition, a dramatic fall in crude oil prices led to a drop in fiscal resources for oil-producing countries, which affected the product demand from the oil & gas sector. The market in Asia Pacific is expected to witness exponential growth over the forecast period on account of the rising number of industries in economies, such as China and India.

Rapid urbanization coupled with the rising demand for residential and commercial construction is anticipated to further fuel the market growth. Increasing adoption of district heating systems, driven by rising electricity tariffs, rising environmental awareness, and technological advances is expected to propel market growth in the U.S. In addition, rising investments in the expansion of gas liquefaction terminals are expected to drive the demand for pipe insulations over the forecast period.The presence of a large number of manufacturers and service providers, coupled with the easy availability of raw materials and easy installation processes, has resulted in intense market competition.

The price structure for pipe insulation varies with respect to production processes and raw materials used. The growing demand for pharmaceutical and cosmetic products is driving the expenditure on capacity additions by major pharmaceutical companies. Process pipes form an integral component in these production facilities and are expected to generate significant demand for pipe insulation over the forecast period. Corrosion under insulation has been one of the major challenges faced by the industry. It is a localized form of external corrosion that occurs on carbon, low alloy steel, and stainless-steel pipes operating at temperatures above 80° Celsius.

Go through the table of content of Insulation Industry Data Book to get a better understanding of the Coverage & Scope of the study

Insulation Industry Data Book Competitive Landscape

Unlike other markets, the players in the global insulation market are more inclined towards increasing their market share through organic growth, rather than mergers and acquisitions. Companies in the market are focusing on expanding their product portfolio by developing cost-effective insulation products with enhanced properties.

Key players operating in the Insulation Industry are:

  • Armacell
  • Lydall, Inc
  • Kingspan Group
  • Owens Corning
  • Huntsman International LLC
  • Saint-Gobain Group

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S. based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Ammunition Industry: List of Key Emerging Companies, Technology Disruptors, and Innovators

Ammunition Industry Data Book Covers Small Caliber Ammunition, Medium Caliber Ammunition, and Large Caliber Ammunition Market

The global Ammunition industry was estimated at USD 22.96 billion in 2022 and is anticipated to increase at a significant CAGR of 3.1% from 2023 to 2030.

Grand View Research’s ammunition industry data book is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research.

Small Caliber Ammunition Market Insights

The global Small Caliber Ammunition Market size was valued at USD 11.93 billion in 2022 and is expected to expand at a compound annual growth rate (CAGR) of 3.7% from 2023 to 2030. Terrorism and political violence risks are expected to incline on account of rising geopolitical tensions and weakening of liberal democratic governance. Also, the repercussive effects of chronic conflicts are emerging as one of the major factors, intensifying the political violence across the globe. Protracted and complex armed conflicts with multiple states and non-state actors is one the major contributing factor to political violence, thereby having a degrading effect on the security and stability of the regions. Also, a broader shift towards populist nationalism and authoritarian governance is one of the major factors heightening the war and civil commotion risks. These factors are expected to positively influence the market growth of small caliber ammunition.

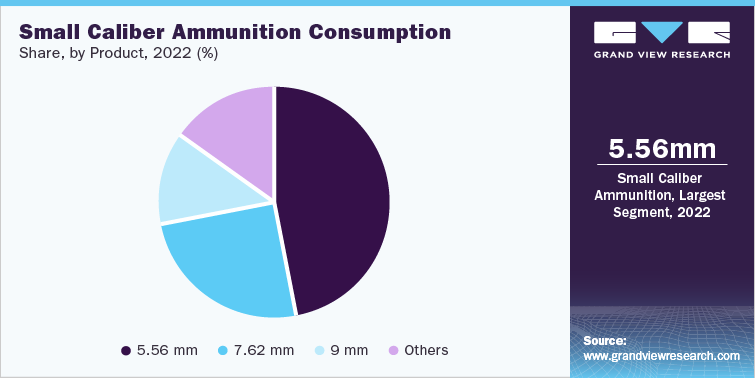
5.56mm caliber includes 5.56 × 45, and others. The 5.56mm NATO cartridge can be recognized by its appearance, the painting of projectile tips, the stamping with the initials of the manufacturer and manufacturing year on the base of the cartridge case, and the markings on the packing containers. 5.56mm caliber are expected to rise owing to their high availability and are used by the Soviet Union on a large scale.

Small Caliber Consumption share, by Product, 2022 (%)

Medium Caliber Ammunition Market Insights

The global Medium Caliber Ammunition Market size was valued at USD 3.56 billion in 2022 and is expected to expand at a compound annual growth rate (CAGR) of 2.9% from 2023 to 2030. In the recent past, the prospects of interstate conflicts have reached their peak after the end of the Cold War. Also, weak leadership in international diplomacy coupled with rising geopolitical tensions have contributed to the sustained risk of armed conflict in recent years. Moreover, the growing rate of polarization over economic, political, and social issues in mature economies coupled with division in western countries in the face of complex risks and threats, is further projected to deteriorate global security and lead to strategic uncertainty.

The Asia Pacific region has witnessed an unprecedented surge in the defense spending over the past decade. Rising geopolitical tension and border disputes between the regional powers have been the primary driving factor boosting the defense spending in the region. Additionally, the growing threat from terrorist activities and separatist insurgency has had a major influence on increasing defense spending in the region. This in turn is expected to positively influence the market for medium caliber ammunition over the forecast period.

Order your copy of the Free Sample of “Ammunition Industry Data Book - Small Caliber Ammunition, Medium Caliber Ammunition and Large Caliber Ammunition Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Large Caliber Ammunition Market Insights

The global Large Caliber Ammunition Market size was valued at USD 5.12 billion in 2022 and will grow at a compound annual growth rate (CAGR) of 1.9% from 2023 to 2030. Large caliber ammunition include ammunition with 105mm caliber and 120mm caliber. Large caliber cartridges are generally projectiles. These cartridges are designed for long-range tank engagement and are used for anti-armor weapons. Large caliber ammunition can be classified into spin-stabilized, fin-stabilized, and rocket-assisted, which is a combination of spin-stabilized and fin-stabilized. A majority of the guns use spin-stabilized large caliber cartridge as it promotes flight stability using spinning, whereas fin-stabilized projectiles obtain stability through the fins located at the end of the projectile. These cartridges are also used for gunnery training in tank-mounted gun cannons.

Russia’s invasion of Ukraine has substantially raised the global security concerns thus opening the growth opportunities for the large caliber ammunition segment. As a result, the large caliber ammunition manufacturers based in the U.S. which is the major hub of munition manufacturing has ramped up the production exponentially, thus positively influencing the target market growth.

Go through the table of content of Ammunition Industry Data Book to get a better understanding of the Coverage & Scope of the study

Ammunition Industry Data Book Competitive Landscape

Key companies, such as General Dynamic Corporation, Northrop Grumman, and BAE Systems, generate majority of their revenues through military and government channels. Their primary customers include the U.S. Department of Defense and intelligence community. Moreover, they also deliver products to the U.S. government customers including the Department of Homeland Security.

Key players operating in the Ammunition Industry are:

  • Northrop Grumman Corporation
  • FN Herstal
  • Olin Corporation
  • General Dynamics Corporation
  • BAE Systems, Inc.
  • Rheinmetall Defense
  • Nexter KNDS Group

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Musical Instruments Industry: Demand for Keyboards Is Expected to Increase Significantly During the Forecast Period

Musical Instruments Industry Data Book Covers Stringed, Percussion, Wind, and Keyboard Instruments Market

The global Musical Instruments industry was estimated at USD 14,117.9 million in 2022 and is anticipated to increase at a significant CAGR of 7.3% from 2023 to 2030.

Grand View Research’s musical instruments industry data book is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research.

Stringed Instruments Market Insights

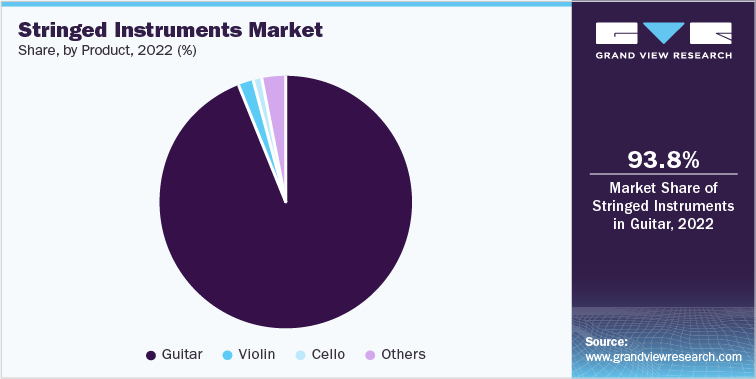
The global Stringed Instruments Market size was valued at USD 8,958.3 million in 2022 and is expected to expand at a compound annual growth rate (CAGR) of 7.4% from 2023 to 2030. The stringed instruments market held the largest market share in the overall musical instruments market. This growth is primarily driven by the increased sales of electric guitars. Electric guitars have gained immense popularity among musicians and enthusiasts for their distinct and versatile sound, well-suited for various music genres such as rock, pop, blues, and jazz. The unique tonal characteristics and the ability to manipulate sound using effects pedals and amplifiers have made electric guitars essential in modern music production. These factors have significantly contributed to the sales of electric guitars, thereby driving the overall stringed instruments market’s growth.

Stringed instruments offer a wide range of tonal possibilities and can be used in various music genres and styles, from classical to rock, folk to jazz. Guitars, violins, cellos, and ukuleles are found in diverse musical landscapes. Their versatility attracts musicians from different backgrounds, expanding the market reach of these instruments and driving growth.

Moreover, technological advancements have played a significant role in the growth of stringed instruments. Innovations in manufacturing processes, materials, and instrument design have improved the quality, playability, and durability of these instruments. Additionally, advancements in amplification and sound processing technologies have enhanced the capabilities and versatility of electric and acoustic-electric stringed instruments, making them more appealing to a broader range of musicians.

For example, Wood Violins, a renowned manufacturer of electric violins, unveiled the new Viper Classic at the National Association of Music Merchants in 2022. The Viper Classic is available in 4-string and 5-string fretless models, featuring a wood Tru-Tone piezo pickup with a transducer in the bridge. It also includes a first-position heel, which benefits players who are just starting out on the electric violin.

Stringed Instruments Market Share, by Product, 2022 (%)

Order your copy of the Free Sample of “Musical Instruments Industry Data Book - Stringed, Percussion, Wind and Keyboard Instruments Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Keyboard Instruments Market Insights

The global Keyboard Instruments Market size was valued at USD 2,843.5 million in 2022 and will grow at a compound annual growth rate (CAGR) of 7.5% from 2023 to 2030. Advancements in technology have revolutionized the keyboard instruments market. Digital keyboards now offer a wide range of features, including realistic piano sounds, multiple instrument voices, recording capabilities, and built-in learning tools. These technological advancements have made keyboards more accessible and appealing to beginners and professionals alike, contributing to market growth.

For instance, in January 2023, Yamaha, the world's largest manufacturer of musical instruments, announced the launch of the P-S500, a digital piano designed for beginners. The new P-S500 is equipped with Stream Lights technology, which uses red and blue lights above each key to visually guide the pianist on which notes to play and when to play them. Additionally, the P-S500 pairs with the Smart Pianist app, providing users with a seamless connection to a smart device and granting full access to instrument controls and configuration tools.

The availability of learning resources and educational programs has contributed to the increased demand for keyboard instruments. Many music schools and online platforms offer comprehensive courses and tutorials tailored for beginners, making it easier for aspiring musicians to start their learning with keyboards. Additionally, music stores often organize workshops and demo sessions to engage potential buyers and assist them in making informed decisions about their instrument purchase, thereby driving the keyboard instruments market. For instance, in April 2022, the National Keyboard Studies Programme announced an initiative that offers school children in the UK the opportunity to learn melodica. This program aims to provide low-cost music education to children by utilizing this inexpensive and low-maintenance instrument.

Go through the table of content of Musical Instruments Industry Data Book to get a better understanding of the Coverage & Scope of the study

Musical Instruments Industry Data Book Competitive Landscape

The manufacturers in the musical instruments market aim to achieve optimum business growth and a strong market position through the implementation of various strategies such as acquisitions, new product launches, collaborations, and strengthening of distribution networks in the global as well as regional markets. Musical instrument manufacturers aim to strengthen their market positions by expanding their customer base through diversification of their product portfolios and incorporating a wide range of musical instruments. Thus, the players are aiming to achieve business growth in the regional market through product launches, mergers, acquisitions, and other strategic initiatives.

Key players operating in the Musical Instruments Industry are:

  • Casio Computer Co., Ltd.
  • F. Martin & Co., Inc.
  • D'addario & Company, Inc.
  • Eastman Music Company
  • Fender Musical Instruments Corporation

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Bicycle Industry: Technology Trends and Growth Driver Analysis, 2023 - 2030

Bicycle Industry Data Book Covers Bicycle, Bicycle Accessories, and Cargo Bikes Market

The global Bicycle industry was estimated at USD 76.01 billion in 2022 and is anticipated to increase at a significant CAGR of 9.5% from 2023 to 2030.

Grand View Research’s bicycle sector data book is a collection of market sizing information & forecasts (2017-2030), key players’ competitive benchmarking analysis, government regulatory data, macro-environmental analysis, and technological framework studies. Within the purview of the database, all such information is systematically analyzed and provided in the form of presentations and detailed outlook reports on individual areas of research.

Bicycle Market Insights

The global bicycle market size was valued at USD 64,625.7 million in 2022 and is expected to expand at a compound annual growth rate (CAGR) of 9.7% from 2023 to 2030. The increase in the number of people opting for bicycling as a form of leisure is anticipated to propel market growth. Preference for bicycles as a convenient form of exercise to ensure a healthy life, free from obesity and other disorders, is expected to further boost the market expansion. The popularity of dockless bicycle-sharing systems has been rising lately. This system allows users to locate a bicycle nearby and unlock it electronically. Incepted originally in Europe, dockless bicycle-sharing systems are gaining popularity, particularly in Asian nations such as India and China.

Furthermore, recent advancements in mobile app development and Global Positioning System (GPS) have resulted in app-based dockless bicycle-sharing systems. Moreover, the growing adoption of such dockless bicycle-sharing systems is anticipated to fuel the demand for cycles significantly. Chinese bicycle-sharing companies are particularly investing and expanding their operations aggressively in European nations to capitalize on the market opportunities. This is expected to boost the market growth in the forthcoming years.

People have started realizing the importance of staying fit and having a healthy life. They have also started realizing that regular bicycling can keep disorders, such as obesity, at bay. The market is likely to grow as more and more people are resorting to bicycling as a regular form of exercise. Events such as Tour de France and Ronde van Vlaanderenare further add to the popularity of these vehicles. Meanwhile, a rise in bicycling events being organized in various countries in Asia, Africa, and the Middle East is fueling the sales of mountain and road bicycles.

Order your copy of the Free Sample of “Bicycle Industry Data Book - Bicycle, Bicycle Accessories and Cargo Bikes Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

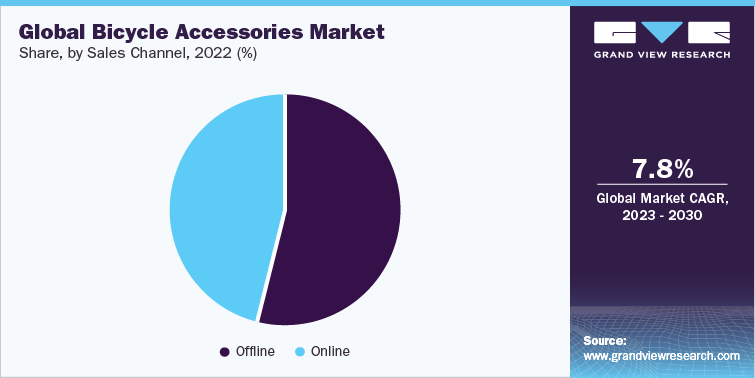
Global Bicycle Accessories Market, by Sales Channel, 2022 (%)

Bicycle Accessories Market Insights

The global bicycle accessories market size was valued at USD 11.43 billion in 2022 and will grow at a compound annual growth rate (CAGR) of 7.8% from 2023 to 2030. The market growth can be attributed to factors, such as health and fitness trends and increasing environmental concerns. As more people take up cycling for transportation, exercise, or leisure, the demand for bicycle accessories has also increased. From helmets, lights, and locks to bags, mirrors, water bottle cages, and pedals, bike accessories are crucial in enhancing the safety, comfort, and functionality of bicycles and cyclists. With the emergence of e-bikes and the growing popularity of cycling among younger generations, the industry is expected to continue its growth in the coming years.

Increase in e-bike sales: E-bikes or electric bikes, have also contributed to the growth of the market. As more people switch to e-bikes for their daily commutes or leisure rides, there is an increasing demand for accessories, such as mounts, integrated lighting, and horn systems, as they help increase the rider’s safety. For example, bicycle lights help cyclists be seen by other road users, especially in low-light conditions or when riding at night. This can be especially important on roads with heavy traffic, where motorists may have difficulty spotting cyclists. In addition, cyclists can reduce the risk of an accident by making themselves more visible by installing appropriate lighting systems.

The high volume of traffic and resulting congestion, coupled with concerns for rider safety and the increasing popularity of cycling, have contributed to a surge in the adoption of bicycle accessories. Other factors driving industry growth include rising interest in cycling sports, growing demand for sports and mountain bikes, and increasing sales of electric bicycles (e-bikes) in emerging markets. As a result, accessories, such as speedometers, mudguards, handlebar grips, LED lights, gloves, helmets, mirrors, and other related products have experienced a rise in demand, leading to projections of rapid expansion in the market.

Go through the table of content of Bicycle Industry Data Book to get a better understanding of the Coverage & Scope of the study

Bicycle Industry Data Book Competitive Landscape

Key companies are investing aggressively; launching new products; introducing new services, such as home delivery of high-end bicycles, after-sales support, and maintenance; and pricing their products and services competitively as part of the efforts to retain their competitiveness. Moreover, a few key market players are expanding their market presence by opting for strategies such as mergers & acquisitions and partnerships and collaborations. For instance, in November 2021, PIERER Mobility AG acquired FELT Bicycles. With this acquisition, PIERER has planned to expand its operations in the North American market for bicycles. This acquisition was intended to serve a customer segment demanding customizing their bicycle according to their individual needs.

Key players operating in the Bicycle Industry are:

  • Accell Group
  • Atlas Cycles (Haryana) Ltd.
  • Avon Cycles Ltd
  • Cervelo
  • Dorel Industries Inc.

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Electric Vehicle Charging Station Industry: Competitive Dashboard Analysis, 2023 - 2030

Electric Vehicle Charging Station Industry Data Book Covers Electric Vehicle Charging Infrastructure and Micro Mobility Charging Infrastructure Market

The global Electric Vehicle Charging Station industry was estimated at USD 24.26 billion in 2022 and is anticipated to increase at a significant CAGR of 25.5% from 2023 to 2030.

Grand View Research’s electric vehicle charging station sector database is a collection of market sizing information & forecasts, regulatory data, reimbursement structure, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, all such information is systematically analyzed and provided in the form of presentations and detailed outlook reports on individual areas of research.

Electric Vehicle Charging Infrastructure Market Insights

The global electric vehicle (EV) charging infrastructure market size was valued at USD 19.67 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 25.5% from 2023 to 2030. The rising levels of carbon emissions and other harmful gases stemming from transportation have triggered the necessity of adopting electric vehicles. As a result, the demand for an electric vehicle charging infrastructure among commercial and residential applications. Moreover, the increasing partnerships between car manufacturers for charging facilities by providing a subscription model is expected to further drive the market.

The technological progress of both electric vehicles charging software and hardware is expected to change the way electric vehicle owners use and benefit from electric vehicle charging applications. Technologies such as Smart car API and charging networks precisely determine an electric vehicle’s charge time even before the car driver plugs the car into a station. Additionally, green energy is expected to play a significant role in both public and residential electric vehicle charging space. Electric vehicle owners are majorly concerned about carbon emissions. To address these concerns, companies are making rapid advancements in the charging technologies of their electric vehicle charging networks.

The market penetration of electric vehicle charging equipment is significantly high at commercial spaces as compared to residential places. The number of commercial charging stations is predicted to increase in line with the growing adoption of electric vehicles. Efforts toward strengthening the charging infrastructure in commercial spaces would be decisive toward encouraging the adoption of electric vehicles, as overnight charging at residential complexes or individual home would not be sufficient for long-distance journeys. Moreover, public charging infrastructure would also facilitate the ultra-fast charging capabilities necessary for long-distance journeys. However, electric vehicle chargers for residential spaces can also offer significant growth potential as they provide a cheaper and convenient mode for charging electric vehicles as compared to commercial charging stations.

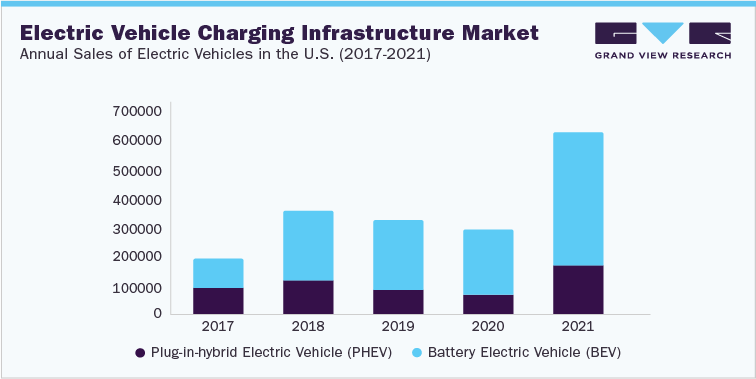
Electric Vehicle Charging Infrastructure Market Annual Sales of Electric Vehicles in the U.S. (2017-2021)

Order your copy of the Free Sample of “Electric Vehicle Charging Station Industry Data Book - Electric Vehicle Charging Infrastructure and Micro Mobility Charging Infrastructure Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Micro Mobility Charging Infrastructure Market Insights

The global micro-mobility charging infrastructure market size was valued at USD 4.58 billion in 2021 and is expected to expand at a compound annual growth rate (CAGR) of 25.8% from 2023 to 2030. Increasing adoption of micro-mobility vehicles such as e-scooters and e-bikes to help reduce pollution and congestion, especially in crowded cities is a major factor driving the market growth. Micro-mobility is a better alternative to public transportation for countries worldwide focusing on solving their transportation problems rising concern of emissions from vehicles running on gasoline or diesel. Moreover, government subsidies and tax incentives aimed at encouraging the adoption of micro-mobility vehicles are further expected to create more growth opportunities for the market.

Rising applications of micro-mobility vehicles in the transportation and commercial sectors are presenting the need for a strong network of micro-mobility charging stations. In response to the rising demand, micro-mobility vehicle manufacturers are also focusing on offering charging networks across the globe. For instance, in November 2020, TIER, a German e-scooter startup, raised USD 250 million in a Series C funding round from SoftBank Vision Fund 2 to expand its presence in European cities. Such developments bode well for the growth of the micro-mobility charging infrastructure market over the forecast period.

The rapidly growing demand for shared mobility solutions is further expected to drive the market growth over the forecast period. Increasing traffic congestion, fuel cost, and rapidly shrinking parking spaces in emerging and developed countries have led to a greater demand for shared mobility solutions. Moreover, citizens prefer the use of shared mobility solutions as they are cheaper than other modes of transportation and eliminate the issues related to parking spaces. However, the high costs of setting up micro-mobility vehicle charging infrastructure could hamper the growth prospects of the market to a certain extent.

Go through the table of content of Electric Vehicle Charging Station Industry Data Book to get a better understanding of the Coverage & Scope of the study

Electric Vehicle Charging Station Industry Data Book Competitive Landscape

The key market players have developed novel concepts and ideas and upgraded the current set of products to sustain the intense competition in the market. The players have adopted new product development as their key developmental strategy to cater to the increasing demand from end-users. The electric vehicle charging infrastructure market and micro mobility charging infrastructure market can be described as moderately fragmented markets characterized by the presence of various prominent players driving competition by pursuing various strategies aimed at long-term sustenance.

Key players operating in the Electric Vehicle Charging Station Industry are:

  • ChargePoint, Inc.
  • Tesla, Inc.
  • ABB
  • BP Chargemaster
  • ClipperCreek, Inc.

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Plastic Packaging Industry: Driver, Restraint, Challenge and Opportunities Analysis, 2023 - 2030

Plastic Packaging Industry Data Book Covers Food & Beverage, Personal & Household, Industrial and Pharmaceutical/ Healthcare Plastic Packaging Market

The global Plastic Packaging Industry was estimated at USD 347.35 billion in 2022 and is anticipated to increase at a significant CAGR from 2023 to 2030.

Grand View Research’s plastic packaging sector data book is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research along with a statistics e-book.

Food & Beverage Plastic Packaging Market Insights

The global Food & Beverage Plastic Packaging Market size was estimated at USD 190,550.86 million in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 3.7% during the forecast period. Food and beverage is one of the largest markets with a significant impact on the global economy and is constantly growing at a significant rate owing to the rising population around the globe. Changing lifestyles, high rates of urbanization, and increased per capita income are driving the demand for packaged food and beverages, which, in turn, is driving the plastic packaging market.

The global food & beverage plastics packaging market is expected to witness growth on account of rising demand for packaged food & beverage demand in developed and developing economies, stringent regulations regarding the preservation of packaged food shelf life, and more convenient features offered by plastic packaging compared to other types of packaging. The convenience can be in the type of weight, price, heat-sealable, portability, and ease of use. Growing demand for packaged ready-to-eat meals, snacks, beverages, and other food products is substantially propelling the penetration of packaging in the food & beverage sector which can positively drive the demand for food & beverage plastic packaging.

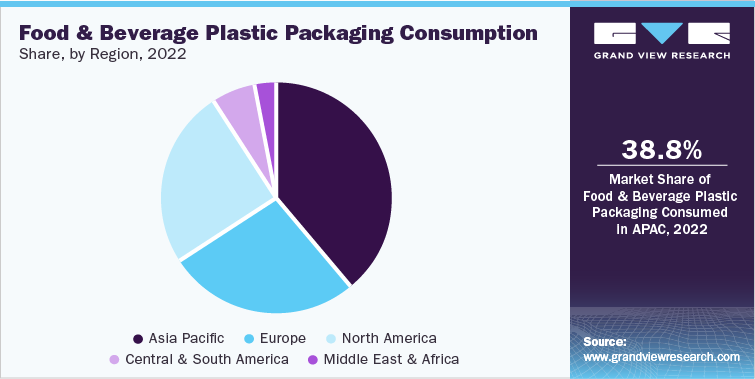
Food & Beverage Plastic Packaging Consumption Share, by Region, 2022

Personal & Household Plastic Packaging Market Insights

The global Personal & Household Plastic Packaging Market size was estimated at USD 70,911.49 million in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 3.8% during the forecast period. Rising consumption of cosmetics, along with increasing disposable income and demand for personal care products, is likely to drive the demand for plastic packaging in personal care & cosmetics applications. Moreover, various product innovations, such as Envers, an extensive range of cosmetic packaging from Lumson S.P.A., which utilizes airless technology on its polyethylene terephthalate glycol (PETG) bottles, increase the demand for added functionality.

Demand for cosmetics and personal care products from millennials is on the rise in major countries including the U.S., China, India, and other developing economies. The consumer base in these countries is expected to increase substantially over the forecast period leading to a higher demand for plastic packaging.

Polyethylene terephthalate is known for its durability, transparency, and resistance to moisture. These properties have made cosmetics product manufacturers consider PET for packaging. Glass and metals have been used considerably in cosmetics product manufacturing. However, the cost associated with these materials positions PET and other plastics at a lower level, thus bringing down the overall cost of the final product. Since the cosmetic products are high priced the rise in packaging cost can hamper the profit margins of the cosmetic product manufacturers.

Order your copy of the Free Sample of “Plastic Packaging Industry Data Book - Food & Beverage, Personal & Household, Industrial and Pharmaceutical/ Healthcare Plastic Packaging Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Industrial Plastic Packaging Market Insights

The industrial packaging segment includes automotive, construction, energy, transportation, and chemical packaging applications. Various automotive parts such as sealing parts, dashboard assemblies, interior panels, interior door panels, bumpers, and air ducts use plastic packaging.

Plastic is a primary material for shippers, pallets, drums, crates, containers, and IBCs which are primarily used for the transportation of industrial, chemical, and petrochemical products. The growing e-commerce industry is expected to create demand for such pallets, shippers, and crates owing to additional warehousing requirements.

The petrochemical market is projected to grow due to the critical demand from end markets that consume petrochemicals. Petrochemicals are widely consumed in chemical, automotive, and other industrial sectors to produce lubricants, motor oil, adhesives, coatings, and paints. The demand for these products is driven by the growth of the automotive, construction, and manufacturing sectors. The growing population and urbanization across the globe are propelling these sectors’ growth which can increase the consumption of petrochemical-based products, thus fueling the demand for rigid bulk packaging.

Go through the table of content of Plastic Packaging Industry Data Book to get a better understanding of the Coverage and scope of the study

Plastic Packaging Industry Data Book Competitive Landscape

The market players compete based on product quality, production capacity, the technology used to produce packaging, and their geographical presence. Major players engage in investing in research and development, developing infrastructure, production facilities expansion, and mergers and acquisitions to vertically integrate their operations across the plastic packaging value chain. These initiatives help them expand their customer base, reduce production costs, develop state-of-the-art products and technologies, ensure competitiveness, and improve their revenue & operations profits.

Key players operating in the Plastic Packaging industry are:

  • Amcor plc
  • Sealed Air
  • Coveris
  • Sonoco Products Company
  • CCL Industries

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter
Recycled Plastics Industry: Recycled Polyethylene Terephthalate Market Size to expand at a CAGR of 5.1% by 2023-2030

Recycled Plastics Industry Data Book Covers Recycled Polyethylene, Recycled Polyethylene Terephthalate (rPET), Recycled Polypropylene, Recycled Polyvinyl Chloride (PVC), and Recycled Polystyrene Market

The global Recycled Plastics Industry was estimated at USD 47.61 billion in 2022 and is anticipated to increase at a significant CAGR from 2023 to 2030.

Grand View Research’s recycled plastics sector data book is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research along with a statistics e-book.

Recycled Polyethylene Market Insights

The global Recycled Polyethylene Market size was estimated at USD 12.37 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.2% during the forecast period. Polyethylene includes high-density polyethylene (HDPE) and low-density polyethylene (LDPE). Polyethylene dominated the recycled plastics market in 2022 and is estimated to maintain its dominance over the forecast period. This can be attributed to the rising consumption of polyethylene for producing reusable bags, agriculture films, toys, milk bottles, housewares, containers, shampoo bottles, trays, food packaging films, and toys. Furthermore, properties such as excellent solvent resistance, high tensile strength, flexibility, toughness, and relative transparency drive the demand for polyethylene in the recycled plastics market.

Recycled HDPE is mainly used to manufacture milk cartons, cutting boards, garbage bins, pens, plastics, fencing, tables, lumber, and bottles. Recycled HDPE offers stiffness with a highly crystalline structure and high density. LDPE waste is mainly generated from household products such as grocery bags, squeezable bottles, plastic wraps, and frozen food containers. Recycled LDPE produces bubble wraps, furniture, garbage cans, and floorings.

Recycled Polyethylene Consumption Share, by Region, 2022

Recycled Polypropylene Market Insights

The global Recycled Polypropylene Market size was estimated at USD 11.11 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.6% during the forecast period. Polypropylene offers excellent chemical and mechanical properties, which make it suitable for use in various industries such as automotive, packaging & labeling, and medical devices. Recycled polypropylene is also used to manufacture battery cases, signal lights, battery cables, brooms and brushes, ice scrapers, kitchen utensils, plastic lumber, outdoor rugs, and oil funnels.

Polypropylene is one of the most formulated plastics across the globe. Properties of polypropylene, such as low moisture & vapor transmission, excellent optical clarity in biaxially oriented films & stretch blow molded containers, and chemical and electrical resistance, are further propelling its demand in the recycled plastics market. Moreover, it manufactures garden rakes, storage bins, shipping pallets, and trays.

Order your copy of the Free Sample of “Recycled Plastics Industry Data Book - Recycled Polyethylene, Recycled Polyethylene Terephthalate (rPET), Recycled Polypropylene, Recycled Polyvinyl Chloride (PVC) and Recycled Polystyrene Market Size, Share, Trends Analysis, And Segment Forecasts, 2023 - 2030” Data Book, published by Grand View Research

Recycled Polyvinyl Chloride (PVC) Market Insights

The global Recycled Polyvinyl Chloride Market size was estimated at USD 6.25 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 4.7% during the forecast period. Sorting and separation are significant challenges in the polyvinyl chloride recycling process. Different formulations composed of various additives are used to produce PVC plastic products, and separating different types of plastics, fillers, and stabilized flame retardants takes work. Furthermore, contamination of other waste streams, such as polyethylene terephthalate, polystyrene, and polyethylene with polyvinyl chloride, carries a significant risk of releasing hydrochloric acid (HCI) at elevated temperatures. These issues associated with PVC recycling affect its demand in the recycled plastics market.

Polyvinyl chloride is found in rigid bottles, clamshells, flexible medical & bedding bags, shrink wrap, wire/cable insulation-coated fabrics, and flooring. Recycled polyvinyl chloride is used to manufacture windows, pipes, floor tiles & mats, gutters, electrical boxes, traffic cones, garden hoses, fencing, films & sheets, cassette trays, electrical boxes, mobile home skirting, and binders, among others.

Recycled Polyethylene Terephthalate (rPET) Market Insights

The global Recycled Polyethylene Terephthalate (rPET) Market size was estimated at USD 5.20 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 5.1% during the forecast. Various types of clothing, such as t-shirts and jackets, use fiber from recycled PET. It is also used in manufacturing automobile seat covers, sofa & chair seat covers, and carpets. The low production cost of clothing and favorable government regulations are the factors expected to drive the demand for recycled PET. Increasing investments in sports activities globally are augmenting the growth of the sports clothing & accessories market, which, in turn, are expected to drive the demand for recycled PET fibers. Jerseys for sports teams are the most common products manufactured using recycled PET fiber. The market for jerseys has grown substantially in Asia Pacific over the past ten years due to increased sports activities in the region, especially in China and India.

The recycled PET market is the largest in the Asia Pacific because of a strong manufacturing industry wherein rPET is widely used across several applications. A broad customer base, government initiatives, and cheap production costs are expected to grow the rPET market. Asia Pacific will continue to be the largest market for rPET owing to a strong network of manufacturing facilities located in economically viable countries in the region. The high import of post-consumer PET bottles and primary production sites due to relaxed regulations is expected to drive market growth.

Go through the table of content of Recycled Plastics Industry Data Book to get a better understanding of the Coverage & Scope of the study

Recycled Plastics Industry Data Book Competitive Landscape

The global players face intense competition from each other and regional players with strong distribution networks and good knowledge about suppliers and regulations. Expanding application areas within the packaging, construction, agriculture, and consumer goods, among other industries, are anticipated to offer growth opportunities for crucial and small and medium market players. In addition, regional players know local competition and recycled plastics demand, which gives them a competitive edge over other players. Therefore, the market players are focusing on strengthening their market positions in the emerging markets of Asia Pacific and Europe through different geographical expansion strategies.

Key players operating in the Recycled Plastics industry are:

  • Biffa
  • Stericycle
  • Republic Services, Inc.
  • Waste Management, Inc.
  • Veolia

Check out more Industry Data Books, published by Grand View Research

About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead. 

Contact:

Sherry James
Corporate Sales Specialist, USA
Grand View Research, Inc.
Phone: 1-415-349-0058
Toll Free: 1-888-202-9519
Email: sales@grandviewresearch.com
Web: https://www.grandviewresearch.com/sector-reports-list
Follow Us: LinkedIn | Twitter

Inside the Unified Endpoint Management Market: Where AI Meets Zero Trust Endpoint Security

Managing laptops, tablets, smartphones, desktops, and IoT devices through separate tools has become hard to sustain. Unified endpoint manage...