Climate-Smart Cows: Innovation Driving the Ruminant Methane Reduction Market

Ruminant Methane Reduction Market Growth & Trends

The global Ruminant Methane Reduction Market is poised for significant growth, with its size projected to reach USD 4.22 billion by 2030. This expansion is anticipated to occur at a Compound Annual Growth Rate (CAGR) of 6.34% from 2025 to 2030, according to a new report by Grand View Research, Inc.

A primary driver for this market's growth is the increasing global livestock population. For instance, in India alone, the National Dairy Development Board reported a total of approximately 192 million bovine dairy cattle and around 113.3 million Asian domestic water buffaloes in 2023, collectively amounting to 307.5 million heads. This substantial animal population directly contributes to methane emissions, highlighting the need for reduction solutions.
Furthermore, the market is expected to benefit from the rising research and development (R&D) efforts by both governmental bodies and market players. These initiatives are focused on developing innovative solutions for methane reduction in ruminants. Coupled with this, ongoing technological advancements are anticipated to further fuel the demand for ruminant methane reduction technologies, as they offer increasingly cost-effective and efficient methods for mitigating these emissions.

Crucially, stringent government regulations and a growing awareness about climate change mitigation among various stakeholders are also vital factors propelling market growth. Governments worldwide are increasingly acknowledging the importance of curbing greenhouse gas emissions, including methane, from the agricultural sector. In response, they are implementing policies and offering incentives to encourage farmers to adopt practices and technologies specifically designed to reduce methane emissions from ruminants.

Curious about the Ruminant Methane Reduction Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Ruminant Methane Reduction Market Report Highlights

  • Feed additives/ Supplements dominated the product segment with a revenue share of over 90% in 2024, owing to increasing R&D and advancements in biotechnology and animal nutrition research.
  • In the product segment, the other products sector is expected to witness the fastest CAGR during the forecast period.
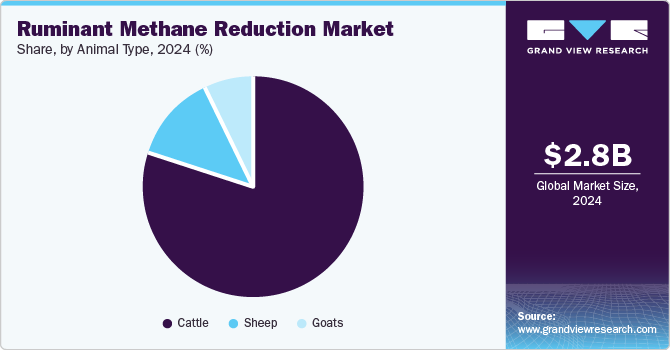
  • In the animal type segment, the cattle sector held the largest revenue share of around 80.08% in 2024, due to the rising awareness about methane emission impact on environment and increasing focus of government on greenhouse emission reduction.
  • In the animal type segment, the goats sector is anticipated to witness the fastest CAGR from 2025 to 2030. Innovations and technological advancements targeting methane emission reduction from goats is expected to drive market growth.
  • North America dominated the market in 2024, owing to increase in investments and financial incentives aimed at reducing methane emission. Asia Pacific, on the other hand, is expected to witness the fastest CAGR during forecast period.

Ruminant Methane Reduction Market Segmentation

Grand View Research has segmented the global ruminant methane reduction market based on product, animal type and region:

Ruminant Methane Reduction Product Outlook (Revenue, USD Billion, 2018 - 2030)

  • Feed Additives/ Supplements
    • Plant-based
    • Chemical-based
    • Microbial-based
  • Other Products

Ruminant Methane Reduction Animal Type Outlook (Revenue, USD Billion, 2018 - 2030)

  • Cattle
  • Sheep
  • Goats

Download your FREE sample PDF copy of the Ruminant Methane Reduction Market today and explore key data and trends.
Agencies Take Note: Programmatic DOOH Is Redefining Campaign Strategy

Programmatic Digital Out-Of-Home Market Growth & Trends

The global Programmatic Digital Out-Of-Home Market is on a rapid growth trajectory, with projections indicating it will reach a substantial USD 6,148.8 million by 2030. This expansion is set to occur at an impressive CAGR of 31.5% from 2024 to 2030, according to a new report by Grand View Research, Inc.

pDOOH is distinguished by its effectiveness in capturing consumer attention in public environments where traditional advertising methods may fall short. The dynamic and visually engaging nature of digital out-of-home (DOOH) advertisements is key to drawing eyeballs and fostering engagement. Furthermore, the inclusion of interactive features on some digital displays offers a more immersive experience, prompting consumer interaction and participation. This capability is particularly valuable for brands aiming to deliver memorable and impactful advertising campaigns.

Crucial to the market's growth have been significant advancements in display technology. The emergence of high-resolution screens, sophisticated LED technology, and interactive displays has transformed static billboards and posters into vibrant, attention-grabbing canvases capable of showcasing rich multimedia content. These technological leaps not only amplify the visual appeal of advertisements but also provide greater flexibility in content delivery. This allows advertisers to finely tune their messages based on variables such as the time of day, specific location, and the demographics of the audience present.

The market has further benefited from the widespread adoption of data-driven targeting capabilities. By harnessing real-time data analytics and profound audience insights, advertisers can now deliver highly personalized and contextually relevant advertisements directly to consumers. Whether it's customizing ads based on prevailing weather conditions, the precise time of day, or proximity to a retail point of sale, data-driven targeting empowers advertisers to optimize campaign performance and maximize their Return on Investment (ROI). This elevated level of targeting precision has significantly enhanced the efficacy of pDOOH advertising, making it a compelling choice for brands seeking to establish meaningful connections with their target audiences.

Curious about the Programmatic Digital Out-Of-Home Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Programmatic Digital Out-Of-Home Market Report Highlights

  • Based on programmatic platform, the demand-side platforms (DSPs) segment led the market with the largest revenue share of 56.03% in 2023. The proliferation of digital screens and the digital transformation of urban environments have expanded the inventory available for pDOOH campaigns, driving the adoption of DSPs
  • Based on location, the indoor segment led the market with the largest revenue share of 72.4% in 2023. Indoor environments often provide access to detailed demographic and behavioral data, enabling precise targeting based on factors such as time of day, consumer behavior patterns, and specific location-based contexts
  • Based on end use, the real estate segment led the market with the largest revenue share of 15.3% in 2023. As urbanization and smart city initiatives continue to grow, the real estate segment's contribution to the market has become increasingly significant, driving its substantial share of global revenue
  • North America dominated the market with the largest revenue share of 35.0% in 2023. The strong presence of leading technology companies and digital advertising firms in North America drives innovation and adoption of programmatic solutions

Programmatic Digital Out-Of-Home Market Segmentation

Grand View Research has segmented the global programmatic digital out-of-home market report based on programmatic platforms, location, end-user, format, and region:

pDOOH Programmatic Platforms Outlook (Revenue, USD Million, 2017 - 2030)

  • Demand-Side Platforms (DSPs)
  • Supply-Side Platforms (SSPs)

pDOOH Location Outlook (Revenue, USD Million, 2017 - 2030)

  • Indoor
  • Outdoor

pDOOH End-use Outlook (Revenue, USD Million, 2017 - 2030)

  • Automotive
  • Financial Services
  • Government
  • Media & Entertainment
  • Retail & E-commerce
  • Real Estate
  • Restaurants
  • Others

pDOOH Format Outlook (Revenue, USD Million, 2017 - 2030)

  • Billboards
  • Street Furniture
  • Transit
  • Others

Download your FREE sample PDF copy of the Programmatic Digital Out-Of-Home Market today and explore key data and trends.
Uncovering the Hidden Value: Why the Process Mining Software Market Is Exploding

Process Mining Software Market Growth & Trends

The global Process Mining Software Market is projected to reach a valuation exceeding USD 21.92 billion by 2030, as per a new report by Grand View Research, Inc. This significant growth is anticipated at an impressive CAGR of 59.4% from 2025 to 2030.

Key Market Drivers

The primary impetus behind this market expansion is the escalating understanding among businesses of the critical need to comprehend and analyze their operations, largely fueled by ongoing digital transformation initiatives. Furthermore, the relentless surge in data volumes across diverse industries is intensifying the demand for process mining software and associated services.

The COVID-19 pandemic, despite its disruptions to global imports and exports (particularly impacting transportation, logistics, and manufacturing sectors), inadvertently spurred market growth. The resulting resource shortages compelled businesses to explore cloud-based solutions and embrace automation technologies, thereby indirectly boosting the adoption of process mining software.

Core Functionality and Benefits

Process mining software integrates various crucial functions, including Business Intelligence (BI), analytics, automation, and Artificial Intelligence (AI). Its core purpose is to help enterprises overcome challenges posed by siloed data scattered across different business processes. By leveraging this technology, organizations can effectively identify and rectify inefficiencies that hinder the performance of their business processes.

The market has also benefited immensely from the sheer volume of data being generated and the increasing necessity to derive actionable insights from this enterprise-wide distributed data. Businesses are actively seeking tools that can facilitate efficient data processing and data mapping. This, in turn, is propelling the demand for process mining software solutions that offer features such as automated process mapping and fact-based insights.

Curious about the Process Mining Software Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Process Mining Software Market Report Highlights

  • In terms of component, the software segment dominated the market in 2024 and is projected to retain its dominance over the forecast period. This can be attributed to the increase in demand from enterprises for software solutions that can be easily integrated into their prevailing BI infrastructure. The services segment is anticipated to register the highest CAGR of around 46.1% over the forecast period
  • Based on deployment, the cloud segment reported the largest revenue share in 2024 and it is expected to register the maximum growth rate over the forecast period. This can be attributed to the rising acceptance of the remote work model and adoption from small and medium as well as large enterprises to integrate cloud technologies into their existing infrastructure. The on-premise segment is expected to grow at a significant rate throughout the forecast period
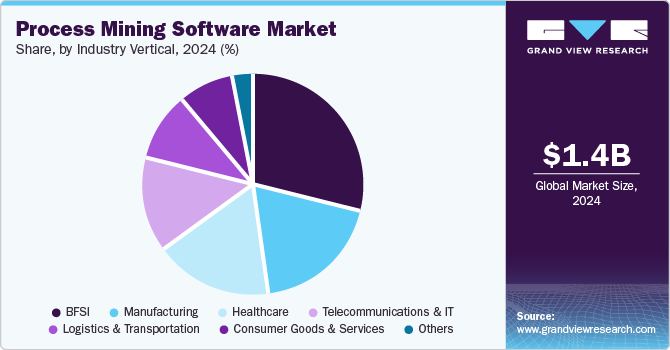
  • In terms of industry vertical, the BFSI industry segment accounted for the largest revenue share in 2024 and is expected to dominate the market throughout the forecast period. As customers are increasingly adopting digital devices and bank competitors are implementing digital technologies, banks and financial services organizations are striving to enhance customer experience and offer better services. Meanwhile, the consumer goods and services industry segment is anticipated to expand at the highest CAGR of over 56.6% over the forecast period
  • Europe dominated the market in 2024 and is expected to retain its dominance over the forecast period. This can be attributed to the growing demand for analytics solutions from small & medium as well as large enterprises in the region. Meanwhile, Asia Pacific is anticipated to register the highest CAGR of around 63.2% over the forecast period

Process Mining Software Market Segmentation

Grand View Research has segmented the global process mining software market report based on component, deployment, application, industry vertical, and region:

Process Mining Software Component Outlook (Revenue, USD Million, 2018 - 2030)

  • Software
  • Services

Process Mining Software Deployment Outlook (Revenue, USD Million, 2018 - 2030)

  • On-Premise
  • Cloud

Process Mining Software Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Strategic Sourcing
  • Contract Management
  • Category Management
  • Transactional Procurement
  • Supplier Management

Process Mining Software Industry Vertical Outlook (Revenue, USD Million, 2018 - 2030)

  • Manufacturing
  • Healthcare
  • BFSI
  • Consumer Goods & Services
  • Telecommunications & IT
  • Logistics & Transportation
  • Others

Download your FREE sample PDF copy of the Process Mining Software Market today and explore key data and trends.
Boba Beyond Beverages: Exploring the Expanding Applications in the Popping Boba Market

Popping Boba Market Growth & Trends

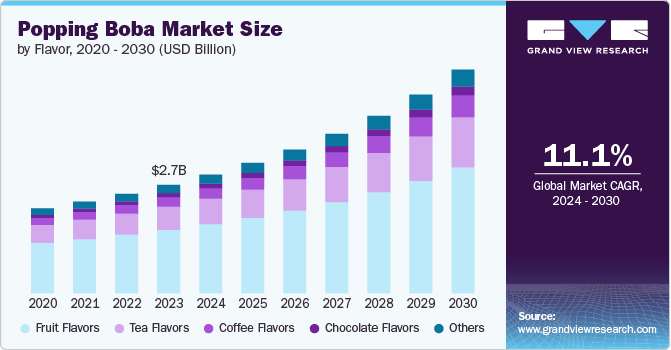
The Popping Boba Market is set for significant expansion, with a Grand View Research, Inc. report forecasting its size to hit USD 5.68 billion by 2030. This represents a robust CAGR of 11.1% over the period from 2024 to 2030. This growth is underpinned by popping boba's natural composition, derived from fruit juices and seaweed extracts, which offers a unique sensory experience. Its appeal to health-conscious consumers is further boosted by its low-calorie count and lack of added sugars. Moreover, rising disposable incomes, especially across Asian developing economies, are enabling consumers to explore premium beverage choices, thereby accelerating demand.

Manufacturers are increasingly prioritizing natural fruit extracts and shunning artificial colors and flavors to align with health-conscious consumer preferences. The market is also seeing a broader spectrum of popping boba flavors, from traditional fruit-based options to more adventurous and savory combinations, encouraging ongoing exploration and market expansion. Consumers are actively seeking healthier alternatives to sugary drinks, and popping boba's natural fruit flavors and reduced sugar content directly address this demand, particularly among younger generations who are more focused on diet and overall well-being.

In 2023, the fruit-flavored popping boba segment commanded a significant portion of the market. This emphasis on fruit flavors stems from evolving consumer attitudes towards health and wellness. As awareness of natural ingredients grows, consumers are gravitating towards fruit-flavored options, perceiving them as healthier substitutes for conventional sweets. This trend has spurred the creation of innovative flavor pairings and the integration of superfood ingredients like acai and matcha into boba products. With consumers prioritizing both health and sensory enjoyment, fruit flavors are poised to remain a key driver of market growth, prompting brands to further innovate with exotic fruit blends and organic sourcing.

The bubble tea segment also held a dominant share of the market in 2023. The bubble tea industry has experienced a surge of innovation in flavors and formulations, with businesses consistently introducing new and seasonal options to attract customers. Strategic marketing now heavily relies on limited-time offerings featuring unique fruit flavors or collaborations with popular brands. Furthermore, the rise of DIY bubble tea kits has empowered consumers to create their favorite drinks at home, extending the product's reach beyond traditional retail channels. This burgeoning market segment not only fulfills the growing demand for customized beverages but also nurtures consumer creativity, firmly establishing popping boba's position within the wider bubble tea landscape. The trend of experiential consumption, where consumers seek memorable dining experiences, has also spurred the proliferation of bubble tea shops, particularly in urban centers.

The food service segment was a major market shareholder in 2023. Popping boba's versatility makes it an appealing ingredient for food service operators looking to innovate their menus. With a diverse array of flavors, from tropical fruits to decadent desserts, businesses can cater to a wide range of palates and dietary needs, including gluten-free and vegan options. This adaptability allows food service establishments to continuously engage their clientele through frequent introductions of limited-time offers or seasonal specials incorporating popping boba. Beyond beverages and desserts, chefs are creatively integrating popping boba into savory dishes, such as salads and appetizers, highlighting its adaptability and paving the way for new culinary trends.

Geographically, Asia Pacific commanded the largest market share in 2023. This is attributed to shifts in consumer preferences, evolving culinary trends, and innovative product offerings. The escalating popularity of bubble tea, especially in countries like Taiwan, China, South Korea, the Philippines, and Thailand, has been instrumental in driving demand for novel boba flavors. Additionally, the proliferation of specialized bubble tea shops, cafes, and convenience stores across the region has significantly improved the accessibility of bursting boba for consumers. Rapid urbanization and the expansion of e-commerce in Asia Pacific further amplify the demand for these juicy tapioca pearls.

Curious about the Popping Boba Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Popping Boba Market Report Highlights

  • North America is expected to grow with a considerable CAGR over the forecast period from 2024 to 2030. Health-conscious consumers are seeking alternatives to traditional sugary syrups and are attracted to popping boba's potential for flavored, low-calorie options, as well as the use of natural ingredients driving the market's expansion. Moreover, food service operators in North America are responding to this trend by incorporating popping boba into their menus, ranging from specialty tea shops to mainstream coffee houses, thus diversifying their offerings and attracting a wider customer base.
  • The coffee-flavored popping boba segment is estimated to grow with a substantial CAGR over the forecast period. Various flavors such as espresso, mocha, hazelnut, and caramel are becoming increasingly popular as manufacturers experiment with different roasting techniques and flavor profiles.
  • The smoothies and beverages segment is estimated to grow with a substantial CAGR over the forecast period. The increasing demand for unique and customizable beverage options has encouraged cafes, juice bars, and restaurants to incorporate popping boba into their menus, resulting in a proliferation of flavored smoothies and drinks that attract a younger demographic seeking novelty and fun in their culinary experiences.
  • The retail segment is estimated to grow with a substantial CAGR over the forecast period. In the retail sector, the distribution of popping boba products has become increasingly diverse, encompassing various channels such as supermarkets, specialty stores, and online platforms. Traditional retail outlets like supermarkets have started to dedicate more shelf space to ready-to-use popping boba products, catering to the growing number of home consumers looking to replicate their favorite bubble tea experiences at home.

Popping Boba Market Segmentation

Grand View Research has segmented the global popping boba market based on flavor, application, distribution channel, and region:

Popping Boba Flavor Outlook (Revenue, USD Million; 2018 - 2030)

  • Fruit Flavors
  • Tea Flavors
  • Coffee Flavors
  • Chocolate Flavors
  • Others

Popping Boba Application Outlook (Revenue, USD Million; 2018 - 2030)

  • Bubble Tea
  • Frozen Yogurt Toppings
  • Ice Cream Toppings
  • Smoothies & Beverages
  • Others

Popping Boba Distribution Channel Outlook (Revenue, USD Million; 2018 - 2030)

  • Food Service
  • Retail
    • Supermarkets & Hypermarkets
    • Convenience Stores
    • Online
    • Others

Download your FREE sample PDF copy of the Popping Boba Market today and explore key data and trends.
Revolutionizing Product Formulations: The Impact of the Polyisobutylene Market

Polyisobutylene Market Growth & Trends

The global Polyisobutylene Market size is anticipated to reach USD 3.42 billion by 2030, according to a new report by Grand View Research, Inc. The market is projected to grow at a compound annual growth rate (CAGR) of 7.3% from 2025 to 2030. This expansion is expected to be driven by the significant growth observed across various end-use industries globally, including automotive, electrical and electronics, food packaging, and building and construction.

Key Properties and Applications of Polyisobutylene

Polyisobutylene (PIB) exhibits a unique combination of desirable properties, including low gas and moisture permeability, high thickening efficiency, good shear stability, excellent electrical insulation, and strong adhesive and tackifier characteristics, along with resilience to UV radiation. These properties make it highly suitable for the manufacturing of a diverse range of products such as filler compounds, adhesives, and sealants, as well as critical components like tubeless tire inner linings, lubricants additives, fuel additives, wrap films, and cable insulation materials.

Strategic Partnerships Driving Manufacturing Capacity

Major players in the polyisobutylene market are actively engaging in strategic partnerships to increase their manufacturing capacity. For instance, in January 2019, Saudi Aramco and TotalEnergies entered into an agreement with Daelim Co., Ltd. for the construction of a new polyisobutylene plant. This facility became operational in 2024 and is located in Saudi Arabia. This initiative provides Daelim Co., Ltd. with the opportunity to serve customers across the Middle East, as well as in European and Asian markets.

Leveraging Regional Scenarios for Market Expansion

Polyisobutylene manufacturers are strategically tapping into regional political landscapes and collaborating with governments to strengthen their market foothold. For example, in March 2021, Kothari Petrochemicals received consent for expansion from the Pollution Control Board in India. This approval from a government agency was a crucial step that led to an increase in their polybutylene production capacity.

Marketing Initiatives Enhancing Brand Presence

Leading polyisobutylene manufacturers are actively implementing various marketing initiatives to bolster their brand presence within the market. For instance, in August 2021, Chevron Oronite, a subsidiary of Chevron Corporation, sponsored and exhibited their product portfolio, which included polyisobutylene, dispersants, PIBSA, and other related products, at the Specialty & Agro Chemicals America conference. Such strategic initiatives are vital for promoting their brands in the competitive polyisobutylene market.

Curious about the Polyisobutylene Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Polyisobutylene Market Report Highlights

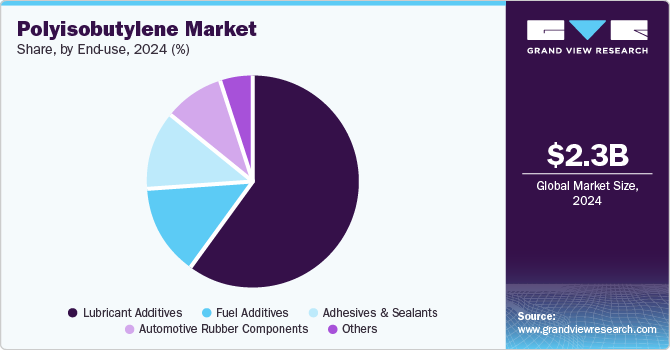
  • The automotive rubber components application segment is expected to register the highest revenue-based CAGR over the forecast period. This is attributed to the use of polyisobutylene in the inner lining of tubeless tires, which is expected to be driven by the growing demand for passenger and commercial vehicles
  • By product, high molecular weight polyisobutylene dominated the market and accounted for more than 68.2% share of the overall revenue in 2024. This is attributed to its use in adhesives, fuel and lubricant additives, food-grade packaging films, and automotive rubber applications
  • The increasing demand for tubeless tires in the automotive industry and the rising demand for lubricant additives are expected to drive the market for polyisobutylene
  • Asia Pacific accounted for more than 36.7% share of the overall revenue in 2024. This can be credited to the increasing demand for polyisobutylene from key industries, including automotive, construction, cosmetics, and aerospace, in emerging economies such as China and India

Polyisobutylene Market Segmentation

Grand View Research has segmented the global polyisobutylene industry report based on product, end-use, and region:

Polyisobutylene Product Outlook (Volume, Tons; Revenue, USD Million, 2018 - 2030)

  • High Molecular Weight
  • Medium Molecular Weight
  • Low Molecular Weight

Polyisobutylene End-use Outlook (Volume, Tons; Revenue, USD Million, 2018 - 2030)

  • Adhesives & Sealants
  • Automotive Rubber Components
  • Fuel Additives
  • Lubricant Additives
  • Others

Download your FREE sample PDF copy of the Polyisobutylene Market today and explore key data and trends.
Inside the Laser Cladding Market: What Industry Professionals Need to Know

Laser Cladding Market Growth & Trends

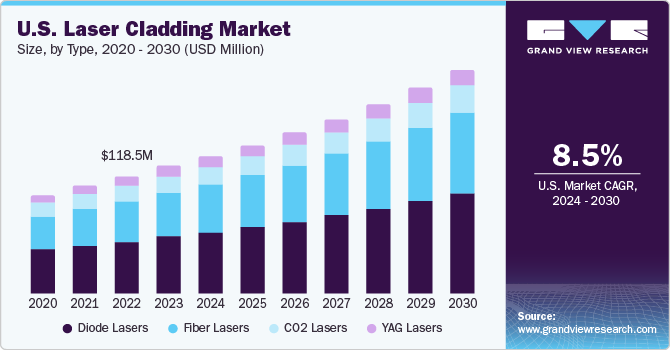
The global Laser Cladding Market size is projected to reach an impressive USD 1,042.1 million by 2030. This growth is anticipated at a compound annual growth rate (CAGR) of 9.3% from 2024 to 2030, as detailed in a new report by Grand View Research, Inc.

The increasing focus on lightweight materials and advanced engineering solutions across vital industries such as aerospace and automotive has significantly bolstered the demand for laser cladding. This technology is crucial for a range of applications, from repairing and refurbishing worn-out components to adding specialized functional coatings for purposes like creating thermal barriers or enhancing electrical conductivity.

Advancements in Laser Technology Fueling Expansion

Ongoing advancements in laser technology are a primary driver of market growth. These innovations include the development of higher power lasers, improved beam delivery systems, and enhanced process monitoring and control capabilities. Such technological progress has broadened the spectrum of materials that can be effectively processed and increased the complexity of geometries that can be coated. This, in turn, has expanded the potential applications of laser cladding, accelerating its adoption across a diverse array of industries.

Enhancing Infrastructure Lifespan and Operational Efficiency

Laser cladding plays a critical role in extending the lifespan of essential infrastructure and equipment in sectors such as energy, mining, and heavy machinery. By applying robust protective coatings to vulnerable areas prone to wear, corrosion, or erosion, laser cladding helps mitigate operational risks, minimize downtime, and significantly enhance asset reliability. This translates into substantial cost savings and improved operational efficiencies for asset-intensive industries.

Market Structure: Consolidation and Vertical Integration

The laser cladding market demonstrates a degree of consolidation and vertical integration, particularly among larger players with extensive capabilities and global reach. Equipment manufacturers in this sector often provide a comprehensive suite of solutions to their customers, which may include material supply, engineering services, and aftermarket support. This strategic integration helps streamline the supply chain, enhance customer service, and allows companies to capture a larger share of the overall value chain.

Curious about the Laser Cladding Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Laser Cladding Market Report Highlights

  • Based on type, the diode lasers segment led the market with the largest revenue share of 43% in 2023. The adoption of diode lasers is driven by their flexibility in beam shaping and modulation, enabling fine-tuning of process parameters to achieve desired coating properties
  • Based on type, the fiber lasers segment is expected to grow at a significant CAGR over the forecast period, due to their superior beam quality, high power density, and reliability. Fiber lasers utilize optical fibers as the gain medium, offering excellent beam stability and delivery characteristics
  • Based on material, the cobal based alloys segment led the market with the largest revenue share of 35% in 2023, due to their excellent wear resistance, corrosion resistance, and high-temperature strength. These alloys are widely used in applications such as aerospace, oil and gas, and power generation industries
  • Based on end-use, the aerospace and defense segment led the market with a revenue share of 31% in 2023. The aerospace and defense sector represents a significant end-user segment for global market. Laser cladding is used for repairing and enhancing critical components such as turbine blades, engine parts, and aircraft structures
  • Asia Pacific led the market in 2023, owing to expanding manufacturing sectors and increasing investments in infrastructure and technology driving the demand for laser cladding solutions

Laser Cladding Market Segmentation

Grand View Research has segmented the global laser cladding market report based on type, material, end-use, and region:

Laser Cladding Type Outlook (Revenue, USD Million, 2018 - 2030)

  • Diode Lasers
  • Fiber Lasers
  • CO2 Lasers
  • YAG Lasers

Laser Cladding Material Outlook (Revenue, USD Million, 2018 - 2030)

  • Cobalt Based Alloys
  • Nickel Based Alloys
  • Iron Based Alloys
  • Carbide & Carbide Blends
  • Others

Laser Cladding End-use Outlook (Revenue, USD Million, 2018 - 2030)

  • Aerospace & Defense
  • Oil & gas
  • Automotive
  • Power Generation
  • Medical
  • Others

Download your FREE sample PDF copy of the Laser Cladding Market today and explore key data and trends.
Leading the Pack: An Analysis of the Europe Pet Wearable Market

Europe Pet Wearable Market Growth & Trends

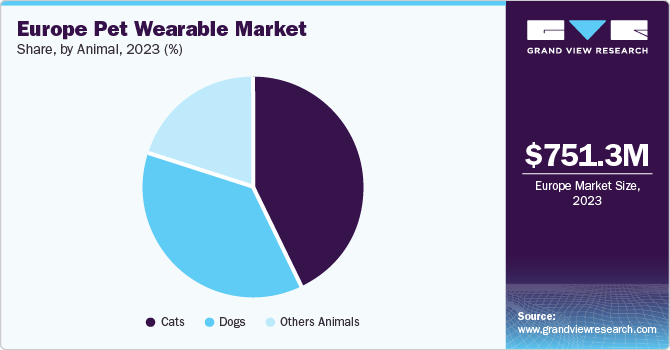
The Europe Pet Wearable Market was valued at an estimated USD 751.3 million in 2023 and is projected to exhibit robust growth at a compound annual growth rate (CAGR) of 14.6% from 2024 to 2030. This market expansion is primarily driven by several factors: increasing pet ownership, heightened concerns regarding pet safety, and continuous advancements in miniaturization and smartphone integration for these devices.

Key Market Drivers

Official figures from the European Pet Food Industry Federation (FEDIAF) indicate a consistent rise in the adoption of various pets, including cats, dogs, exotic birds, and fish across the region. This growing pet population directly translates into a greater demand for solutions that enable comprehensive monitoring of their well-being and activities.

Furthermore, Europe benefits from the presence of well-established market players, such as Datamars, known for offering a diverse array of pet wearables and complementary software solutions. The strong presence of such companies provides pet owners with more advanced options, fosters confidence in the technology, attracts further investment into the sector, and ultimately propels regional market growth.

Europe's Contribution to the Global Market

In 2023, the Europe pet wearables market accounted for a significant 27.8% share of the global pet wearable market revenue. The increasing rates of pet ownership, coupled with a rising awareness among pet owners about animal health, are significant contributors to the escalating demand for these products. As disposable income levels rise across the European region, pet owners are increasingly willing to invest in advanced pet care solutions, thereby fueling the demand for innovative wearables.

The Role of Technological Innovation

The continuous evolution of pet wearables is heavily reliant on technological innovations, leading to the development of more advanced and user-friendly products. These innovations encompass the integration of sophisticated sensors, advanced data analytics capabilities, and seamless wireless connectivity, all of which significantly enhance the functionalities of pet wearables. For instance, the incorporation of GPS tracking enables real-time monitoring of a pet's location, while specialized health sensors provide crucial insights into vital signs and activity levels. A user-friendly design ensures seamless integration into a pet owner's daily routine, promoting ease of use and broad accessibility.

Advanced Technologies: AI, ML, and IoT

Advances in cutting-edge technologies, including sensing technologies, Artificial Intelligence (AI), and Machine Learning (ML), play a pivotal role in driving innovation and the development of new products that offer extended battery life and improved connectivity features. Integrating modern sensing technology into pet wearables facilitates a deeper, more nuanced understanding of pets' behavior, health, and overall well-being.

Moreover, the trends of miniaturization and extended battery life offer substantial advantages to both pets and their owners. The improved battery life of these solutions significantly reduces the need for frequent charging, guaranteeing uninterrupted monitoring of pet activity over extended durations. The increasing adoption of smart homes in developed European economies, such as Germany, France, and the UK, is also anticipated to further drive market growth in the coming years by enabling greater integration and convenience for pet owners.

Curious about the Europe Pet Wearable Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Europe Pet Wearable Market Report Highlights

  • The radio frequency identification technology segment accounted for the largest revenue share of 44.8% in 2023.
  • The cats segment accounted for the largest revenue share in 2023.
  • The smart collar segment accounted for the leading revenue share of 42.6% in 2023.
  • The connectivity integrated circuits segment held the dominant revenue share in 2023.
  • The identification & tracking application segment held the largest revenue share in 2023.

Europe Pet Wearable Market Segmentation

  • Technology Outlook (Revenue, USD Million, 2018 - 2030)
    • RFID
    • GPS
    • Sensors
  • Product Outlook (Revenue, USD Million, 2018 - 2030)
    • Smart Collar
    • Smart Camera
    • Smart Harness and Vest
    • Others
  • Animal Outlook (Revenue, USD Million, 2018 - 2030)
    • Dogs
    • Cats
    • Other Animals
  • Component Outlook (Revenue, USD Million, 2018 - 2030)
    • GPS Chips
    • RFID Chips
    • Connectivity Integrated Circuit
      • Bluetooth Chips
      • Wi-Fi Chips
      • Cellular Chips
    • Sensors
    • Processors
    • Memory
    • Displays
    • Batteries
    • Others
  • Application Outlook (Revenue, USD Million, 2018 - 2030)
    • Identification & Tracking
    • Behavior Monitoring & Control
    • Facilitation, Safety & Security
    • Fitness Monitoring
    • Medical Diagnosis & Treatment

Download your FREE sample PDF copy of the Europe Pet Wearable Market today and explore key data and trends.
Understanding the Digital Logistics Market: Trends and Insights

Digital Logistics Market Growth & Trends

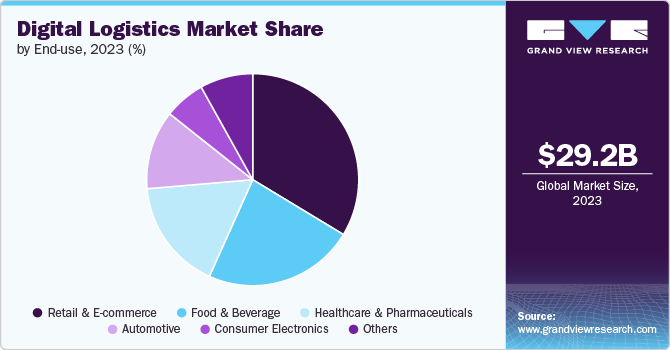
The global Digital Logistics Market reached an estimated USD 29.18 billion in 2023 and is projected to expand significantly at a compound annual growth rate (CAGR) of 18.4% from 2024 to 2030. This robust growth is primarily fueled by the rapid expansion of the e-commerce sector, ongoing technological advancements, and the critical need for businesses to mitigate supply chain disruptions and maintain operational continuity.

Understanding Digital Logistics

Digital logistics involves leveraging digital technologies to manage, optimize, and automate logistics and supply chain operations. It integrates various digital tools and platforms, enhancing the efficiency, visibility, and adaptability of moving goods from suppliers to customers.

Benefits of Digital Logistics Solutions

Digital logistics solutions offer a multitude of advantages, including enhanced efficiency, improved visibility, and substantial cost reduction. By automating and optimizing logistics processes, businesses can reduce manual labor, minimize errors, and accelerate operations. Real-time tracking and monitoring capabilities provide greater transparency, enabling companies to manage their supply chains more effectively. Furthermore, these solutions empower companies to scale operations and adapt to dynamic market demands with greater ease.

Key Growth Drivers

The exponential rise in e-commerce has generated immense demand for efficient, fast, and flexible logistics solutions. Digital logistics technologies are crucial for managing the complexities of e-commerce supply chains, ensuring rapid order fulfillment, real-time tracking, and streamlined returns management. As businesses increasingly globalize, managing international logistics becomes more intricate. Digital logistics solutions are indispensable for coordinating global supply chains, managing cross-border shipments, and navigating diverse regulatory requirements, all of which contribute to market expansion.

Technological Advancements Powering the Market

Companies are increasingly harnessing Artificial Intelligence (AI) and Machine Learning (ML) to predict demand, optimize routes, and reduce delivery times. By analyzing vast datasets, these technologies can anticipate disruptions, adjust logistics plans in real-time, and enhance decision-making. Internet of Things (IoT) devices provide real-time data on shipment location, condition, and status. Sensors embedded in containers and vehicles monitor critical factors like temperature, humidity, and shock levels, which are vital for sensitive goods such as pharmaceuticals and perishables.

Innovation in Action

Continuous innovation and the launch of new technological solutions for logistics operations are significantly propelling market growth. For example, in July 2024, C.H. Robinson Worldwide, Inc. introduced Digital Dispatch. This advanced load-matching platform, powered by AI and data science, provides real-time, personalized load recommendations based on carriers' search history and preferences. This innovation drastically reduces the time carriers spend searching for freight, leading to faster and more relevant matches. Consequently, carriers can secure loads more quickly, optimize their routes, increase earnings, and minimize empty miles. Digital Dispatch is currently available for small carriers, with plans for future expansion to larger operators.

Curious about the Digital Logistics Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Digital Logistics Market Report Highlights

  • The solution segment dominated the market in 2023 and accounted for more than 64.0% share of global revenue.
  • The cloud segment dominated the target market in 2023 and accounted for more than 75.0% share of global revenue.
  • The transportation management segment dominated the market in 2023 and accounted for more than 31.0% share of global revenue.
  • The retail & e-commerce segment dominated the market in 2023 and accounted for more than 33.0% share of global revenue.
  • North America dominated the global digital logistics market and accounted for a revenue share of over 36.0% in 2023.

Digital Logistics Market Segmentation

  • Component Outlook (Revenue, USD Million, 2017 - 2030)
    • Solution
    • Services
  • Deployment Outlook (Revenue, USD Million, 2017 - 2030)
    • Cloud
    • On-premises
  • Application Outlook (Revenue, USD Million, 2017 - 2030)
    • Transportation Management
    • Warehouse Management
    • Order Management
    • EDI
    • Others
  • End-use Outlook (Revenue, USD Million, 2017 - 2030)
    • Retail & E-commerce
    • Automotive
    • Healthcare & Pharmaceuticals
    • Food & Beverage
    • Consumer Electronics
    • Others

Download your FREE sample PDF copy of the Digital Logistics Market today and explore key data and trends.
Unpacking the Explosive Growth of the Data Centric Security Market

Data Centric Security Market Growth & Trends

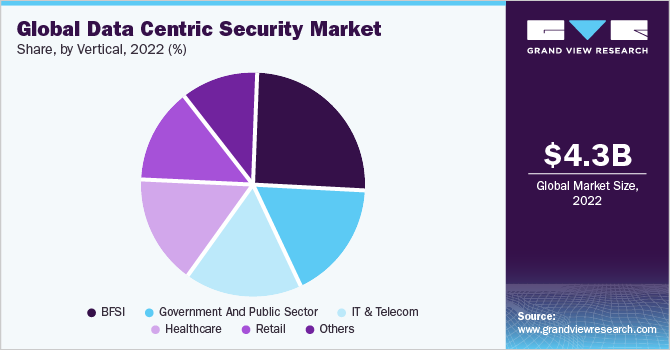
The global Data Centric Security Market is projected to reach an impressive USD 24.01 billion by 2030, demonstrating a robust Compound Annual Growth Rate (CAGR) of 24.2% from 2023 to 2030, as per new reports from Grand View Research, Inc. This significant growth is primarily driven by the rapid proliferation of digital technologies and the escalating incidence of cybercrimes, which have dramatically increased the risk of cyber-attacks and data breaches for organizations worldwide. Consequently, there's a heightened demand for data-centric security solutions designed to safeguard sensitive information across various locations, both within and between organizations.

Key Drivers and Regulatory Impact

Stringent government regulations and policies across different regions are also fueling market demand. For instance, regulations like the European Union's General Data Protection Regulation (GDPR) and the California Consumer Privacy Act (CCPA) have created a strong impetus for industries such as retail, BFSI (Banking, Financial Services, and Insurance), IT & telecom, and healthcare to implement adequate security measures.

The increasing financial and reputational repercussions of data breaches are further boosting the demand for data-centric security. A notable example is the May 2019 data breach at First American Financial Corporation, which exposed 885 million credit card applications and real estate personal and financial transaction records due to a common website design flaw. In response to such growing data breaches, organizations are making substantial investments in data-centric security solutions to mitigate risks and vulnerabilities, thereby minimizing associated costs, including remediation efforts, legal liabilities, and potential loss of user trust.

Technological Advancements and Industry-Specific Solutions

The market growth is also significantly propelled by the increasing effectiveness and efficiency of data-centric security solutions, driven by advancements in technologies such as:

  • Data encryption
  • Data masking
  • Tokenization
  • Data Loss Prevention (DLP)

These technological advancements provide organizations with more comprehensive and robust protection capabilities for sensitive information. Furthermore, the development of industry-specific data protection solutions, tailored to address the unique nature and sensitivity of data across sectors like healthcare, government, and finance, has intensified the need for advanced data-centric security solutions. This has led to increased adoption of data-centric security solutions specifically designed to tackle distinct industry challenges.

Curious about the Data Centric Security Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Data Centric Security Market Report Highlights

  • The software segment accounts for the largest market share of over 63.3% in 2022 and is anticipated to maintain its dominance over the forecast period owing to the growing need to strengthen data privacy and regulation laws across industries such as BFSI, IT & telecom, healthcare, and retail, among others
  • The cloud segment is expected to observe the highest CAGR of 25.1% during the forecast period. The growing migration of data and workload to the cloud has made it essential for organizations to enhance the security and privacy of sensitive information, thereby fueling the demand for data centric security
  • The small & medium enterprises segment is anticipated to witness an exceptional CAGR of 24.8% during the forecast period. The growing awareness of the importance of data privacy owing to the increased media coverage of data breaches and legal requirements has enhanced the demand for data-centric security solutions in the segment
  • The healthcare segment is anticipated to register a considerable CAGR of 25.7% over the forecast period owing to the growing adoption of cloud platforms to store and manage sensitive information related to patient’s health, financial transaction, and other healthcare operations
  • North America accounted for the largest market share of over 35.2% in 2022 and is expected to retain its position over the forecast period. The growing cyber threats and crimes across industries such as retail, BFSI, and healthcare, along with the focus of government on imposing stringent data security regulations, has boosted the demand for data centric security

Data Centric Security Market Segmentation

Grand View Research has segmented the global data centric security market based on solution, deployment, enterprise size, vertical, and region:

Data Centric Security Solution Outlook (Revenue, USD Billion, 2018 - 2030)

  • Software
  • Services

Data Centric Security Deployment Outlook (Revenue, USD Billion, 2018 - 2030)

  • Cloud
  • On-premise

Data Centric Security Enterprise Size Outlook (Revenue, USD Billion, 2018 - 2030)

  • Small and Medium-sized Enterprises
  • Large enterprises

Data Centric Security Vertical Outlook (Revenue, USD Billion, 2018 - 2030)

  • BFSI
  • Government and Public Sector
  • Healthcare
  • IT and Telecom
  • Retail
  • Others

Download your FREE sample PDF copy of the Data Centric Security Market today and explore key data and trends.
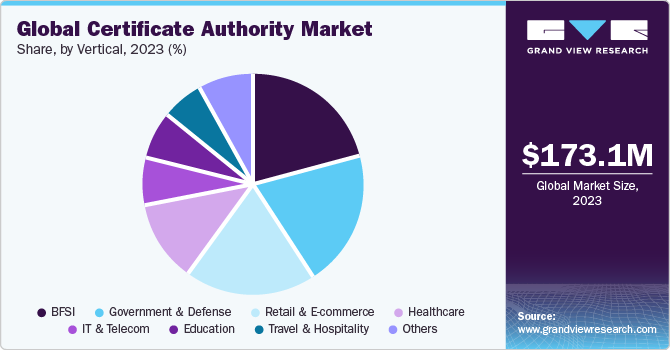
The Billion-Dollar Horizon: Forecasting the Certificate Authority Market by 2030

Certificate Authority Market Growth & Trends

The global Certificate Authority Market is poised for substantial expansion, with projections indicating it will reach USD 401.4 million by 2030. This growth is driven by a strong Compound Annual Growth Rate (CAGR) of 13.1% from 2024 to 2030, according to a new report by Grand View Research, Inc. The evolving technological landscape, including the widespread adoption of cloud computing, mobile computing, and blockchain, presents both new opportunities and challenges for securing digital communications, to which CAs are actively adapting by offering innovative solutions.

Catalysts for Market Growth

A significant driver for the certificate authority market is the burgeoning e-commerce sector, which necessitates SSL/TLS certificates for secure online transactions. Enhanced Validation (EV) certificates, known for their rigorous identity verification processes, are particularly favored by e-commerce platforms aiming to build customer trust. The dynamic e-commerce landscape, encompassing both traditional online retail and omni-channel approaches, is fostering innovation in multi-domain and mobile-friendly certificate solutions.

According to the FIS Global Payment Report 2023, e-commerce experienced a 10% year-over-year growth from 2021 to 2022 and is anticipated to grow at a CAGR of 9% from 2022 to 2026. This increasing reliance on digital payments in e-commerce compels companies to adopt certifications to ensure secure transactions and safeguard customer data.

Regulatory Landscape and Compliance

Governments globally are actively introducing regulations and standards to bolster digital communication security and protect user privacy. Initiatives such as the European Union's General Data Protection Regulation (GDPR), the California Consumer Privacy Act (CCPA), and various industry-specific regulations (e.g., HIPAA, PCI DSS) impose stringent requirements for data protection and secure communication.

Certificate authorities play a vital role in enabling organizations to comply with these regulations. They provide essential SSL/TLS certificates and other cryptographic solutions that facilitate the encryption of data in transit and the authentication of websites and online services, thereby ensuring a secure digital environment.

Curious about the Certificate Authority Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Certificate Authority Market Report Highlights

  • Based on component, the certificate type segment led the market with the largest revenue share of 62.0% in 2023, due to the increasing adoption of cloud computing services and hybrid IT infrastructures
  • Based on enterprise size, the SMEs segment is anticipated to witness at the fastest CAGR during the forecast period. SMEs increasingly deploy IoT devices for various purposes, such as inventory management, asset tracking, and environmental monitoring, which lead to secure device authentication
  • Based on certificate validation type, the domain validation segment led the market with the largest revenue share of 46.0% in 2023. Advancements in technology, such as automation and improved validation processes, have simplified the issuance and management of domain validation certificates, making them more accessible to organizations
  • Based on vertical, the healthcare segment is anticipated to witness at the fastest CAGR during the forecast period. Healthcare organizations face increasing cybersecurity threats due to adopting electronic health records and telemedicine platforms
  • North America accounted for the largest revenue share of 33.7% in 2023 and is projected to grow at a significant CAGR over the forecast period. The region has witnessed a rise in data breaches and cyberattacks, leading businesses and government agencies to prioritize cybersecurity

Certificate Authority Market Segmentation

Grand View Research has segmented the global certificate authority market report based on component, enterprise size, certificate validation type, vertical, and region:

Certificate Authority Component Outlook (Revenue, USD Million, 2018 - 2030)

  • Certificate Type
  • Services

Certificate Authority Enterprise Size Outlook (Revenue, USD Million, 2018 - 2030)

  • SMEs
  • Large Enterprises

Certificate Authority Certificate Validation Type Outlook (Revenue, USD Million, 2018 - 2030)

  • Domain Validation
  • Organization Validation
  • Extended Validation

Certificate Authority Vertical Outlook (Revenue, USD Million, 2018 - 2030)

  • BFSI
  • Retail and E-commerce
  • Government and Defense
  • Healthcare
  • IT and Telecom
  • Travel and Hospitality
  • Education
  • Others

Download your FREE sample PDF copy of the Certificate Authority Market today and explore key data and trends.
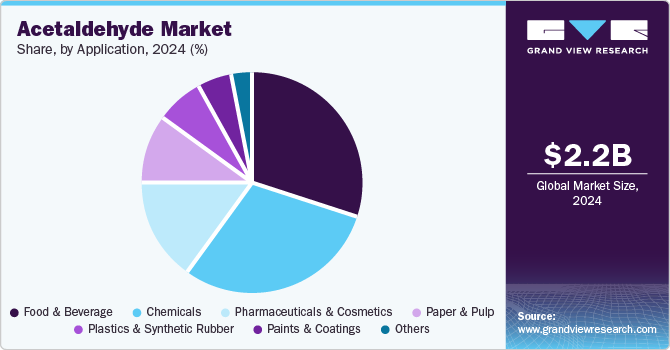
Grand View Research Unveils Key Trends in the Global Acetaldehyde Market

Acetaldehyde Market Growth & Trends

The global Acetaldehyde Market is projected to reach an estimated USD 3.05 billion by 2030, exhibiting a Compound Annual Growth Rate (CAGR) of 5.4% from 2025 to 2030, according to a new report by Grand View Research, Inc. This growth is primarily driven by the increasing demand for acetaldehyde as a chemical intermediate in the production of various commodity compounds. These compounds find extensive use across diverse industries, including rubber, food & beverage, and others.

Production and Market Dynamics

Large-scale global production of acetaldehyde is undertaken to meet commercial demands. The manufacturing process can employ various raw materials, including ethanol and ethylene. The availability and cost of these feedstocks significantly influence the economic viability of production.

Acetaldehyde is commonly found in smaller quantities in certain fermented foods, such as soy products, canned vegetables, milk products, and non-alcoholic beverages. The growing demand for processed foods and alcoholic beverages further impacts the CH3CHO market.

Applications in Food and Beverages

A key application of CH3CHO is as a flavoring agent to enhance the taste and aroma of specific food products. It is frequently incorporated into various beverages and confectionery items to impart fruity, nutty, or green apple-like flavors. It can also be found in alcoholic beverages like whiskey and brandy, contributing to their distinctive flavor profiles.

Market Strategies and Regional Growth

Leading market players are reinforcing their positions by concentrating on expanding their product portfolios and investing in technological advancements.

The Asia Pacific region is anticipated to register a significant CAGR in the coming years. This is due to the region being a major producer and consumer of the product, with China and India collectively accounting for over 50% of the regional market share.

Curious about the Acetaldehyde Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Acetaldehyde Market Report Highlights

  • The food & beverage segment led market, in terms of revenue and volume, due to the high product usage in various food products as a flavoring agent.
  • Pharmaceuticals & cosmetics segment is expected to grow significantly at CAGR of 5.8% over the forecast period.
  • Oxidation of Ethylene segment accounted for 75.48% of the revenue share in 2024. The oxidation of ethylene is one of the most widely adopted processes for acetaldehyde production due to its cost-effectiveness and high efficiency.
  • Oxidation of Ethanol segment is expected to grow significantly at CAGR of 5.2% over the forecast period.
  • Asia Pacific dominated the market and accounted for 60.0% of global revenue in 2024. The robust industrial and manufacturing landscape in Asia Pacific has made it a key consumer of acetaldehyde for various chemical application.

Acetaldehyde Market Segmentation

Grand View Research has segmented the global acetaldehyde market on the basis of process, application, and region:

Acetaldehyde Process Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)

  • Oxidation of Ethylene
  • Oxidation of Ethanol
  • Dehydrogenation of Ethanol
  • Others

Acetaldehyde Application Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)

  • Food & Beverage
  • Chemicals
  • Pharmaceuticals & Cosmetics
  • Paper & Pulp
  • Plastics & Synthetic Rubber
  • Paints & Coatings
  • Others

Download your FREE sample PDF copy of the Acetaldehyde Market today and explore key data and trends.
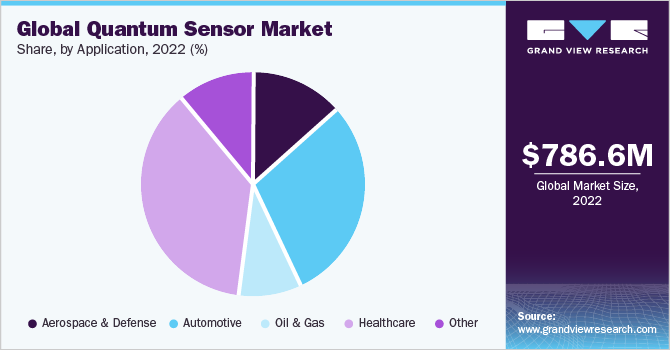
Analyzing the Competitive Landscape of the Quantum Sensor Market

Quantum Sensor Market Growth & Trends

The global Quantum Sensors Market is on a significant growth trajectory, with projections indicating it will reach USD 1.42 billion by 2030. This expansion represents a Compound Annual Growth Rate (CAGR) of 7.8% from 2023 to 2030, as reported by Grand View Research, Inc.

Key Market Drivers

The primary driver behind the increasing demand for quantum sensors is the need for high-precision measurement equipment across diverse sectors, notably healthcare and automotive & transportation. Furthermore, substantial government investments worldwide are accelerating the development of quantum sensors, particularly for military & defense applications.

Quantum Sensors in Space Applications

Quantum technology, including sensing, is poised for considerable adoption in space applications. Quantum sensors are ideal for satellite use due to their ability to provide high accuracy measurements, durability, and efficiency in a compact, low-weight package. Their fundamental atomic features and quantum interference measurements offer precise capabilities for space navigation, position, and timing.

In August 2022, a German consortium comprising Bosch, Q.ANT, TRUMPF, and the German Aerospace Center (DLR) unveiled plans to utilize quantum technology to enhance satellite measurement stability. Their objective is to develop space-qualified attitude sensors, which could improve internet access, especially in remote areas.

Asia Pacific's Rapid Growth

The Asia Pacific region is projected to exhibit the second-fastest growth, with a CAGR of 9.2% during the forecast period. This growth is primarily fueled by the increasing adoption of advanced imaging devices and quantum sensors across sectors like defense, healthcare, automotive, and transportation. Additionally, government initiatives supporting research and development in the field, alongside efforts to promote quantum technology adoption, contribute significantly to the region's lucrative growth prospects. A notable example is the Indian Government's launch of the National Quantum Mission, valued at USD 735.7 million, specifically for quantum technology research applicable across various end-use sectors, including health, finance, communication, and energy.

Curious about the Quantum Sensor Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Quantum Sensor Market Report Highlights

  • The atomic clock segment held the largest share of 37% in 2023 and is projected to grow at a significant CAGR during the forecast period. The atomic clocks use atomic resonance frequency standards and are very precise timekeepers
  • NASA’s Deep Space Atomic Clock is one of the much-known examples of the same. The growing applications for atomic sensors in navigation, power grid, telecommunication, and financial trading, among others, is a prime factor boosting the sales of atomic clock devices
  • The healthcare application segment held the largest share and is projected to grow at the fastest CAGR during the forecast period. Quantum sensors are being used in biomedical devices to empower a radical rise in their sensitivity
  • A new generation of medical imaging devices that are capable of detecting human physiology will lead to faster and more precise diagnoses. Such devices can benefit from quantum sensors and provide considerable growth opportunities in the field of medical devices
  • Major launches and innovations are augmenting the automation tool segment. For instance, in December 2022, AOSense, a small company, created the first generation of quantum technology and novel products in quantum gravimetry. The company worked with NASA’s Goddard Space Flight Center, to develop quantum sensors for precise navigation

Quantum Sensor Market Segmentation

Grand View Research has segmented the global quantum sensors market on the basis of product type, application, and region:

Quantum Sensor Product Type Outlook (Revenue, USD Billion, 2017 - 2030)

  • Atomic Clocks
  • Gravitational Sensors
  • PAR Quantum Sensors
  • Quantum Magnetic Sensors
  • Others

Quantum Sensor Application Outlook (Revenue, USD Billion, 2017 - 2030)

  • Aerospace & Defense
  • Automotive
  • Oil & Gas
  • Healthcare
  • Other

Download your FREE sample PDF copy of the Quantum Sensor Market today and explore key data and trends.
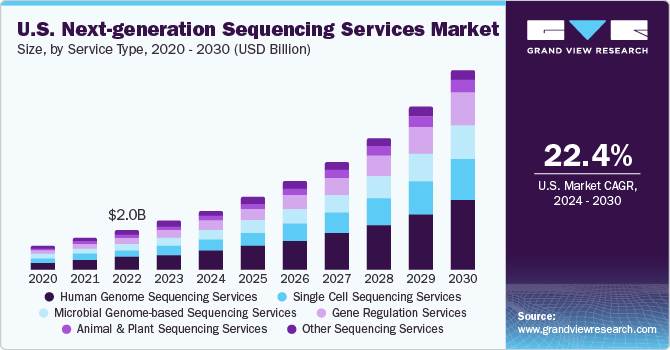
Beyond the Gene: Exploring the Impact of the Next-Generation Sequencing Services Market

Next-Generation Sequencing Services Market Growth & Trends

The Next-Generation Sequencing Services Market is forecasted to reach USD 24.48 billion by 2030, expanding at a compound annual growth rate (CAGR) of 22.68% from 2024 to 2030, according to a report by Grand View Research, Inc. Advances in NGS technology have significantly improved gene sequencing efficiency, reproducibility, and cost-effectiveness, driving its adoption in clinical laboratories and hospitals. Recent innovations focus on simplifying sequencing technology and enhancing its sophistication, which has fueled its widespread use among various end-users.

Over the last five years, NGS has transitioned from research applications to clinical use, with 14 countries launching large-scale genome sequencing programs. By 2025, nearly 60 million individuals are expected to have their genomes analyzed. Traditional disease testing service providers have expanded their offerings to include sequencing-based genetic tests. For instance, ARUP Laboratories introduced new coronavirus tests in March 2022, while IDbyDNA, Inc. collaborated to develop an NGS-based test for respiratory illnesses, assisting physicians in diagnosing pneumonia and other respiratory conditions.

The increasing demand for high-throughput sequencing within the pharmaceutical and biotechnology sectors has necessitated improvements in sequencing speed, platform efficiency, and workflow simplification. Companies are now focusing on enhancing sample amplification and purification technologies. In March 2022, Illumina, Inc. unveiled TruSight Oncology (TSO) Comprehensive (EU), a diagnostic tool designed to analyze multiple tumor genes and biomarkers, enabling personalized genomic decisions for cancer patients. This in vitro diagnostic (IVD) kit debuted in Europe, marking the beginning of its global rollout.

Curious about the Next-Generation Sequencing Services Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Next-Generation Sequencing Services Market Report Highlights

  • By service type, human genome sequencing held the largest revenue share in 2023 owing to greater penetration of whole genome and whole exome sequencing
  • Gene regulation services, particularly small RNA sequencing and ChIP-seq, are anticipated to grow at a lucrative pace during the forecast period. Rising investment in RNA sequencing is fueling the growth of gene regulation services
  • The larger revenue share of sequencing services as compared to other workflow steps can be attributed to an increase in the installation of sequencing platforms. High maintenance and recovery costs of this step have also resulted in greater revenue generation
  • By end-use, the universities and other research entities segment held the largest revenue share in 2023 owing to the growing application of NGS technology for cancer prognosis as well as diagnosis and major projects taken up by academicians and universities
  • North America dominated the market in 2023 owing to higher penetration of the technology in this region and the availability of funds to employ the technique and derive research findings for disease targeting

Next-Generation Sequencing Services Market Segmentation

Grand View Research has segmented the global next-generation sequencing services market report based on service type, workflow, end-use, and region

Next-generation Sequencing (NGS) Service Type Outlook (Revenue, USD Million, 2018 - 2030)

  • Human Genome Sequencing Services
  • Single Cell Sequencing Services
  • Microbial Genome-based Sequencing Services
  • Gene Regulation Services
    • Small RNA Sequencing
    • ChIP Sequencing
    • Other Gene Regulation-based Services
  • Animal & Plant Sequencing Services
  • Other Sequencing Services

Next-generation Sequencing (NGS) Services Workflow Outlook (Revenue, USD Million, 2018 - 2030)

  • Pre-sequencing
  • Sequencing
  • Data Analysis

Next-generation Sequencing (NGS) Services End-use Outlook (Revenue, USD Million, 2018 - 2030)

  • Universities & Other Research Entities
  • Hospitals & Clinics
  • Pharma & Biotech Entities
  • Others

Download your FREE sample PDF copy of the Next-Generation Sequencing Services Market today and explore key data and trends.
Why the Legionella Testing Market is Crucial for Public Health

Legionella Testing Market Growth & Trends

The global Legionella Testing Market is projected to reach USD 547.4 million by 2030, experiencing a compound annual growth rate (CAGR) of 8.2% from 2025 to 2030, as reported by Grand View Research, Inc. The rising prevalence of Legionella-related diseases, such as Pontiac fever and pneumonia, remains a significant driver of market expansion. According to the World Health Organization (WHO), approximately 10 to 15 new cases per million people are detected annually across Europe, Australia, and the United States.

The increasing preference for timely Legionella testing is linked to benefits such as faster recovery and improved patient outcomes. Furthermore, the integration of advanced diagnostic technologies, including polymerase chain reaction (PCR) and point-of-care testing, is anticipated to propel market growth during the forecast period.

Globally, government-backed initiatives such as Legionella testing programs, awareness campaigns, and water safety regulations are set to enhance disease detection and management. In Europe, for example, strict regulatory frameworks mandate routine Legionella testing in water systems, driving the demand for advanced testing methodologies.

Curious about the Legionella Testing Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Legionella Testing Market Report Highlights

  • Europe dominated the global legionella testing market with over 39.0% share in 2024 owing to factors such as increasing awareness regarding legionellosis, sophisticated healthcare systems, public health protection initiatives, and mandatory testing regulations in countries such as the UK and Germany.
  • The IVD testing segment is expected to grow at a significant CAGR over the forecast period.
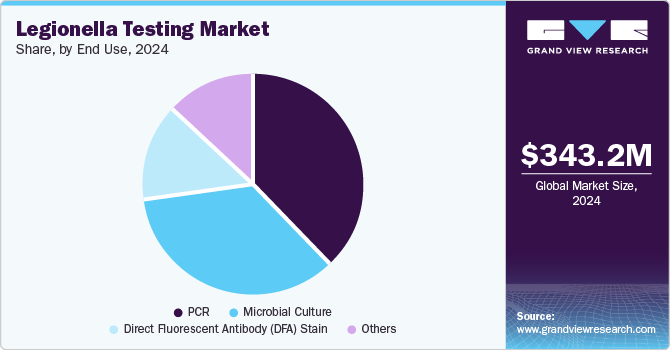
  • Based on end use, the PCR segment dominated market with revenue share of 37.7% in 2024. PCR enables the precise and rapid detection of bacteria through its high sensitivity and quick turnaround time.
  • Increasing legionella outbreaks recorded in numerous regions driven by factors such as demography, environmental factors and others are expected to drive demand.
  • Significantly enhanced healthcare systems, growing awareness regarding timely interventions, and government initiatives associated with public health are likely to add lucrative growth opportunities to this industry over forecast period.

Legionella Testing Market Segmentation

Grand View Research has segmented the legionella testing market on the basis of type, end use, and region:

Legionella Testing Type Outlook (Revenue, USD Million, 2018 - 2030)

  • Water Testing
  • IVD Testing

Legionella Testing End Use Outlook (Revenue, USD Million, 2018 - 2030)

  • Microbial Culture
  • Direct Fluorescent Antibody (DFA) Stain
  • PCR
  • Others

Download your FREE sample PDF copy of the Legionella Testing Market today and explore key data and trends.

The Role of AI and IoT in the Future of the Home Infusion Therapy Market

Home Infusion Therapy Market Growth & Trends

The global Home Infusion Therapy Market is experiencing significant growth, with a projected size of USD 61.7 billion by 2030, reflecting a CAGR of 8.1% from 2024 to 2030. This upward trend is driven by a confluence of factors:

  1. Favorable Government Policies and Regulations: Government initiatives aimed at expanding healthcare coverage and promoting cost-effective treatment options are a key driver. A prime example is the Bipartisan Budget Act of 2018 in the U.S., which mandated government coverage for temporary payments of home infusion therapy. This legislation provided crucial reimbursement support, encouraging the adoption of home infusion services and making them more accessible to patients. Recent legislative efforts, such as "The Preserving Patient Access to Home Infusion Act," continue to seek to modernize Medicare's coverage of home infusion, aiming to remove physical presence requirements for reimbursement and expand the availability of therapies.
  2. Rising Prevalence of Chronic Diseases: The increasing global burden of chronic diseases such as cardiovascular diseases (CVDs), cancer, diabetes, and other life-threatening conditions is a major catalyst for market growth. These conditions often require long-term, consistent medication administration, making home infusion therapy a practical and desirable solution. For instance, in 2019, chronic diseases accounted for 60% of total deaths and 43% of the disease burden in the U.S., highlighting the substantial need for ongoing care, including nutritional products like glutamine, phospholipids, glucose, and amino acids, infused alongside medications.
  3. Cost-Effectiveness and Patient Convenience: Home infusion therapy offers a more cost-effective alternative to hospital stays, reducing expenses related to facility fees, hospital beds, and staffing. This financial advantage appeals to both healthcare systems and patients. Furthermore, the convenience of receiving treatment at home, avoiding travel to clinics, maintaining daily routines, and benefiting from family support, significantly enhances patient preference and adherence to treatment plans.
  4. Growing Geriatric Population: The global aging population is more susceptible to chronic illnesses, leading to a higher demand for long-term care and home-based treatment options. Home infusion therapy provides an effective and convenient solution for managing these conditions in older adults, improving their quality of life.
  5. Shift from Acute Care Settings: There's a growing trend to shift care from high-cost institutional settings like hospitals to more economical and patient-preferred environments such as home and ambulatory infusion centers. This shift is driven by payer dynamics and a focus on value-based care, making home infusion a compelling option.

Key Segments and Regional Outlook:

  • Product: Infusion pumps currently hold the largest revenue share, driven by their increasing use for delivering various medications and nutrients.
  • Application: Anti-infective therapy dominates the market due to the high volume of procedures and the need for continuous administration of antibiotics and antifungals. Chemotherapy is expected to be the fastest-growing segment due to the rising incidence of cancer.
  • Region: North America leads the market, attributed to its advanced healthcare infrastructure, high demand for new technologies, and favorable reimbursement policies. Asia Pacific is projected to be the fastest-growing region, driven by increasing awareness, a large diabetic patient population, and a growing geriatric demographic.

Challenges: Despite the strong growth drivers, the market faces challenges such as the risk of infections associated with home infusion, given the difficulty of maintaining hospital-level sterility in a home environment. Additionally, stringent regulatory frameworks and the high cost of some infusion equipment and therapies can sometimes hinder market expansion and accessibility. A shortage of skilled healthcare professionals (nurses and pharmacists) essential for delivering safe and effective home care is also a concern.

In conclusion, the home infusion therapy market is experiencing robust growth fueled by supportive policies, the rising prevalence of chronic diseases, the lasting impact of the pandemic, cost efficiencies, technological advancements, and patient preference for home-based care. While challenges exist, the overall outlook remains highly positive.

Curious about the Home Infusion Therapy Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Home Infusion Therapy Market Report Highlights

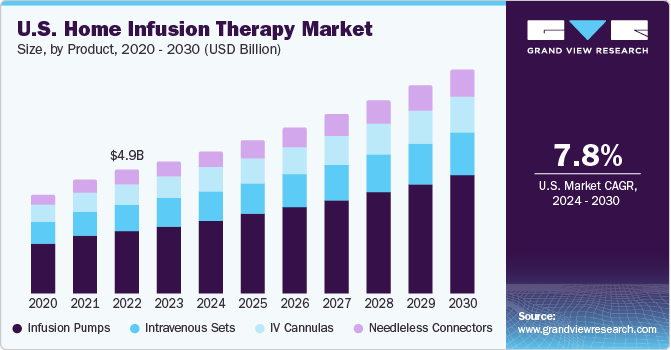
  • By product, The infusion pumps segment accounted for the largest revenue share of over 51.3% in 2023 owing to the increasing use of delivery fluids such as nutrients and medications
  • The anti-infective application segment dominated the market with a revenue share of over 26.9% in 2023as a large number of procedures are performed during the administration of medications, such as antibiotics and antifungals
  • North America dominated the market in 2023 with a revenue share of over 56.22% and this trend is expected to continue throughout the forecast period owing to the increasing demand for new technologies, along with advanced healthcare infrastructure
  • The Asia Pacific market is expected to register the fastest CAGR over the forecast period owing to the increasing number of diabetic patients in the region

Home Infusion Therapy Market Segmentation

Grand View Research has segmented the global home infusion therapy market on the basis of on product, application, and region:

Home Infusion Therapy Product Outlook (Revenue, USD Million, 2018 - 2030)

  •  Infusion Pumps
    • Elastomeric
    • Electromechanical
    • Gravity
    • Others
  • Intravenous Sets
  • IV Cannulas
  • Needleless Connectors         

Home Infusion Therapy Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Anti-infective
  • Endocrinology
    • Diabetes
    • Others
  • Hydration Therapy
    • Athletes
    • Others
  • Chemotherapy
  • Enteral Nutrition
  • Parenteral Nutrition
  • Specialty Pharmaceuticals
  • Others

Download your FREE sample PDF copy of the Home Infusion Therapy Market today and explore key data and trends.

Future Outlook: Heart Pump Device Market to Reach New Heights by 2030

Heart Pump Device Market Growth & Trends

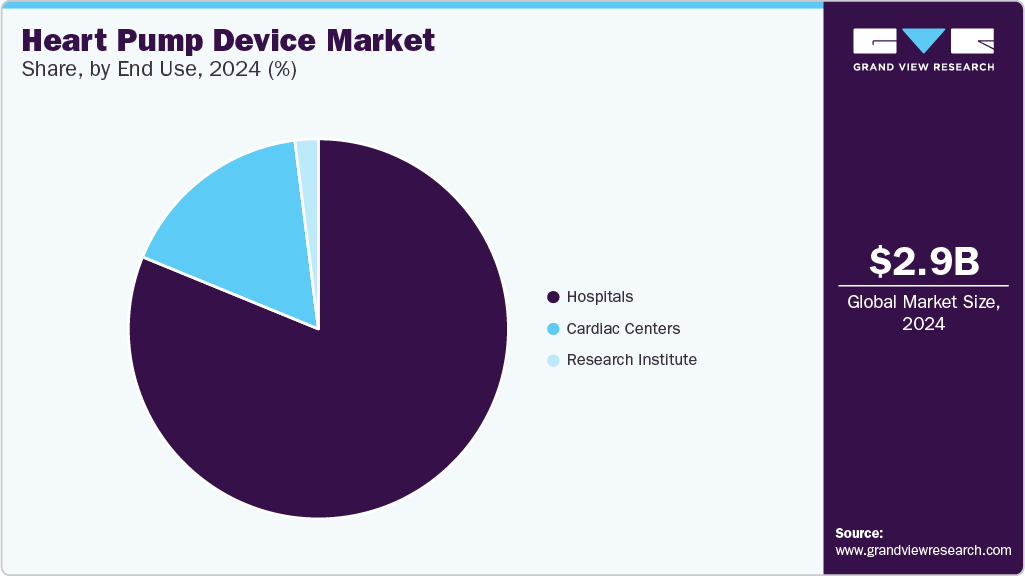
The global Heart Pump Device Market is poised for significant growth, projected to reach USD 6.39 billion by 2030, exhibiting a robust CAGR of 13.6% from 2025 to 2030. This expansion is primarily driven by several key factors:

  1. Rising Prevalence of Cardiovascular Diseases (CVDs):

The increasing incidence of conditions like coronary artery disease, ischemic heart disease, and other CVDs globally is a major demand driver for heart pump devices. For instance, in 2022, approximately 7.6 million individuals in the UK were living with heart disease, and around 160,000 deaths annually were attributed to CVD and other heart-related conditions. Similarly, in Japan, coronary heart disease caused over 163,905 deaths in 2020. This growing patient pool with end-stage heart failure necessitates advanced treatment options, including heart pump devices.

  1. Technological Advancements in Heart Pump Devices:

The market is witnessing continuous innovation, leading to more effective, user-friendly, and reliable devices. Key advancements include:

Miniaturization and Portability: Smaller, more efficient devices are being developed, allowing for less invasive implantation procedures, greater patient mobility, and improved quality of life. Some devices are even small enough to be injected without surgery.

Continuous-Flow LVADs: The shift from pulsatile-flow to continuous-flow Left Ventricular Assist Devices (LVADs) has significantly improved patient outcomes, with continuous-flow devices like Abbott's HeartMate 3 showing higher survival rates and reduced complications (e.g., pump thrombosis, stroke, infection).

Improved Biocompatible Materials: Advancements in materials science are leading to devices with enhanced durability and reliability, reducing the risk of device failure and complications like infection and clotting.

Wireless Power Transfer Technologies: Innovations in this area aim to mitigate driveline-related complications, further enhancing patient safety and quality of life.

AI and IoT Integration: The integration of artificial intelligence and Internet of Things (IoT) technologies in device functionality and remote monitoring presents growing opportunities, enabling ongoing surveillance and instant clinical attention.

Development of ECMO Systems: Extracorporeal Membrane Oxygenation (ECMO) systems are being developed to provide advanced life support for patients with severe heart and lung conditions, effectively taking over the work of the heart and lungs.

  1. Increasing Support and Awareness Initiatives:

Programs focused on disease awareness and the development of advanced treatment options are contributing to market growth. A notable example is Hridyantra, a challenge-based program launched by The School of Medical Research and Technology at IIT Kanpur in January 2022. Its objective is to create an advanced artificial heart, specifically a Left Ventricular Assist Device (LVAD), for patients with end-stage heart failure. This initiative aims to improve existing treatment options for HF patients, thereby driving the demand for heart pump devices, especially in regions like India.

  1. Growing Geriatric Population:

The aging global population is more susceptible to cardiovascular diseases, leading to an increased demand for heart pump devices as a means to improve quality of life and survival rates in this demographic.

  1. Shortage of Organ Donors:

The limited availability of heart donors makes heart pump devices a crucial alternative for patients with end-stage heart failure, either as a bridge to transplantation or as destination therapy.

Challenges:

Despite the promising growth, the market faces challenges such as the high cost of heart pump devices and associated implantation procedures, which can limit accessibility, particularly in developing nations. Stringent regulatory approval processes and occasional product recalls also pose hurdles.

Overall, the global heart pump device market is set for substantial growth, driven by the increasing burden of heart disease, continuous technological advancements, and supportive initiatives aimed at improving patient outcomes.

Curious about the Heart Pump Device Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Heart Pump Device Market Report Highlights

  • Based on type, the implanted heart pump devices segment accounted for the largest revenue share of 69.1% of the market in 2024, due to their ability to assist with pumping blood and serve as a bridge to transplantation or a permanent therapy option for HF patients.
  • Based on product, ventricular assist devices (VADs) held the largest market share of 68.5 % in 2024. It is estimated to register the fastest CAGR of 14.8% during the forecast period; owing to the increasing prevalence of HF worldwide, the demand for VADs is anticipated to grow rapidly over the forecast period.
  • Based on end-use, the hospital segment dominated the market in 2024, attributed to the high number of surgeries performed in hospitals.
  • North America is expected to dominate the market with over 52.59% revenue share in 2024 due to the high prevalence of heart failure, growing aging population, and robust healthcare system.

Heart Pump Device Market Segmentation

Grand View Research has segmented the heart pump device market based on type, product, end use, and region:

Heart Pump Device Type Outlook (Revenue, USD Billion, 2018 - 2030)

  • Implanted Heart Pump Devices
  • Extracorporeal Heart Pump Devices

Heart Pump Device Product Outlook (Revenue, USD Billion, 2018 - 2030)

  • Ventricular Assist Devices (VADs)
    • Left Ventricular Assist Devices (LVADs)
    • Right Ventricular Assist Devices (RVADs)
    • BiVAD Ventricular Assist Devices (BiVADs)
    • Percutaneous Ventricular Assist Devices (PVADs)
  • Intra-Aortic Balloon Pumps (IABPs)
  • Extracorporeal Membrane Oxygenation (ECMO)

Heart Pump Device End Use Outlook (Revenue, USD Billion, 2018 – 2030)

  • Hospitals
  • Cardiac Centers
  • Research Institute

Download your FREE sample PDF copy of the Heart Pump Device Market today and explore key data and trends.

Oxygen Concentrator Market Outlook: Growth, Regions, Leaders, and Segment Showdowns

Oxygen therapy is moving out of hospitals and into living rooms. As chronic respiratory conditions become more common and populations age, o...