Mechanical Anchors: A Key Component in Structural Stability

Mechanical Anchors Market Growth & Trends

The global Mechanical Anchors Market size is expected to reach USD 2,319.8 million by 2030, registering a CAGR of 2.8% from 2023 to 2030, according to a new report by Grand View Research, Inc. The mechanical anchors have potential demand and installation across the building and construction sector including historic masonry materials. These anchors mechanically anchor themselves in the base material with the help of friction and some type of movement to achieve holding values.

The rapidly expanding construction industry is driving demand for the mechanical anchor industry growth. The increasing focus on advanced architectural design across the construction sector is expected to create potential demand over the forecast timeframe from 2023 to 2030. The economic development across rapidly developing countries including China and India is further estimated to accelerate growth during the forecast timeframe.

The continuous involvement of the government and international non-profit organizations for the development of respective areas and countries, in terms of advanced structural designs, that can meet the sustainable goals of the future is helping to generate market demand for mechanical anchors. Additionally, the rising focus to limit the emission of greenhouse gases (GHG) across the buildings and construction industry is another factor anticipated to create demand in the near future.
Mechanical anchors are primarily used in a solid concrete base, brick, & block, and stone. These mechanical anchors have to be strong and sturdy as they are subjected to transferring the load to the base material through, friction, bearing, or keying which requires high strength and hardness. As a result, majority of the mechanical anchors are made from carbon steel material as they exhibit outstanding workability, and strength to absorb stress in extreme load conditions.

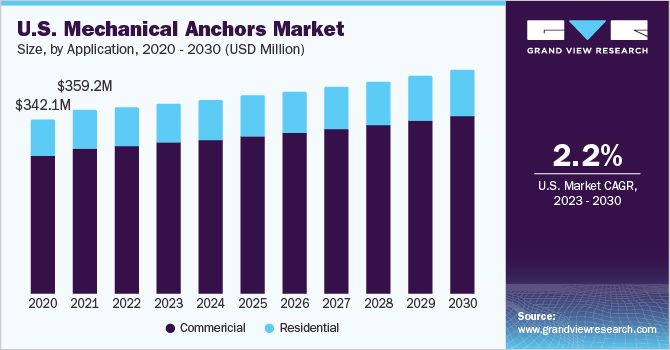
The mechanical anchors industry is segmented into residential and commercial based on the applications. The residential application segment holds a comparatively small share when compared to commercial applications. The use of mechanical anchors in residential applications includes fixing wooden or plastic frames to the concrete or masonry units, railing and fences, and cable trenches.

The U.S. mechanical anchor industry is anticipated to witness moderate growth over the coming years owing to rising demand for machinery tools from the automotive, construction, and aerospace & defense industries. Despite the downturn in 2020 caused by the COVID-19 pandemic, rising emphasis on the production of building tools in the region, along with the continuation of construction operations, is anticipated to prove beneficial for the demand for the anchor.

The value chain of the mechanical anchors market comprises raw material suppliers, manufacturers, suppliers/distributors/exporters, and end-users. The raw materials include carbon steel and stainless steel. These raw materials are used in the manufacturing of anchors and are procured directly from the steel manufacturers or their distributors or suppliers and anchor manufacturers have signed agreements with the steel manufacturers for smooth supply.

Curious about the Mechanical Anchors Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Mechanical Anchors Market Report Highlights

  • Stainless steel was the largest and fastest growing market segment and accounted for 54.2% of the revenue share in 2022 as stainless steel hardly gets oxidized when compared to other materials including iron, and carbon steel. Additionally, aesthetic shining appearance, corrosion resistance, low maintenance, and strength make stainless steel a widely used material for manufacturing mechanical anchors
  • Carbon steel accounted for USD 674.1 million for the year 2022 owing to its high strength. The presence of high carbon content makes them good at resisting abrasion and retaining shape under excess load in construction buildings. In addition, the material is primarily heat-treated by austenitizing, and quenching, followed by tempering to enhance its mechanical properties including yield and tensile strength
  • Residential applications accounted for a revenue share of over USD 476.0 million in 2022. The use of mechanical anchors in residential applications includes fixing wooden or plastic frames to the concrete or masonry units, railing and fences, and cable trenches. Metals such as aluminum and steel are widely used in the manufacturing of windows and doors in buildings owing to the lightweight and highly durable properties exhibited by the metals
  • Commercial applications accounted for 74.3% of the total market share for the year 2022. In commercial sectors, mechanical anchor finds its wide application in various malls, hotels, sports complexes, and industries. This building design is becoming more complex and is fitted with a wide variety of pipes, tubes, and cables suspended from the ceiling. These are primarily held on metal trenches which are fitted with mechanical anchors to fasten them to the underside of the concrete deck for support and hold
  • Companies are engaged in the adoption of strategic initiatives such as research & development and vertical integration to gain a competitive edge

Mechanical Anchors Market Segmentation

Grand View Research has segmented the global mechanical anchors market based on the material, application, and region.

Mechanical Anchor Material Outlook (Revenue, USD Million, 2018 - 2030)

  • Carbon Steel
  • Stainless Steel
  • Others

Mechanical Anchor Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Residential
  • Commercial

Mechanical Anchor Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
    • Italy
  • Asia Pacific
    • China
    • Japan
    • India
    • Australia
    • New Zealand
  • Central & South America
    • Brazil
    • Argentina
  • Middle East & Africa

Download your FREE sample PDF copy of the Mechanical Anchors Market today and explore key data and trends.
India's Solar Revolution: Regional Insights into PV Panel Demand

India Solar PV Panels Market Growth & Trends

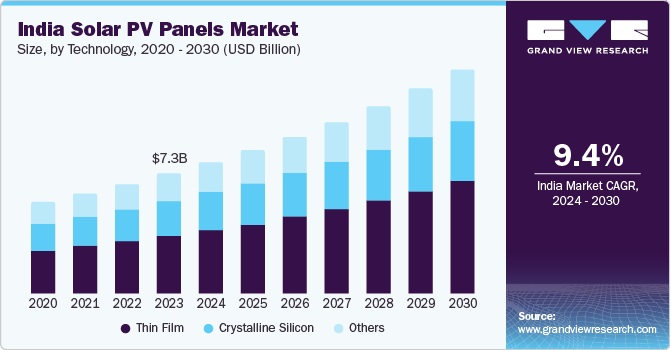
The India Solar PV Panels Market size is anticipated to reach USD 13.69 billion by 2030 and is anticipated to expand at a CAGR of 9.4% from 2024 to 2030, according to a new report by Grand View Research, Inc. Key drivers of the solar market are the cost competitiveness of solar PV compared to grid power, the acceptance of solar energy by governments and large consumers, the potential for significant cost savings through reduced electricity expenses, the availability of tax benefits such as accelerated tax depreciation and income tax exemptions for solar projects, and the emphasis on environmental sustainability through initiatives such as the Companies Act and Corporate Social Responsibility (CSR) goals.

In India, the decreasing cost of solar photovoltaic (PV) technology has made solar energy increasingly competitive with grid power. Technological advancements, economies of scale, and government incentives such as subsidies and tax benefits drive this cost reduction. The Indian government has firmly committed to promoting solar energy through various policies and initiatives. The National Solar Mission aims to increase solar capacity, and state governments offer incentives such as net metering and open access for solar projects. For instance, in June 2021, SolarSquare acquired PV Diagnostics to enhance residential solar standards. This acquisition aims to improve solar energy efficiency and performance through advanced diagnostics technology.

Curious about the India Solar PV Panels Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

India Solar PV Panels Market Report Highlights

  • Thin films dominated the market in 2023.It is due to their cost-effectiveness, flexibility, and efficiency, supported by advancements in solar energy technologies and the dropping prices of thin-film solar technology. Crystalline silicon is expected to grow at the fastest CAGR during the forecast period
  • On Grid held the largest share in 2023, due to the reliability and stability of grid-connected systems, the ability to feed excess power back to the grid for credits or revenue, and the support from government policies such as net metering and incentives for grid-connected solar installation. Off Grid is expected to grow at the fastest CAGR
  • Industrial segment accounted for the largest share in 2023. The dominance is attributed to the rising acceptance of solar power by large consumers for cost savings and environmental sustainability, supported by tax benefits such as accelerated tax depreciation and income tax exemptions for solar projects
  • In September 2023 Gautam Solar, a top Indian solar module manufacturer, secured a patent for an innovative "Tool for Bussing Process of Solar Panel," enhancing panel production yield and reducing manual work by over 50% while doubling production capacity

India Solar PV Panels Market Segmentation

Grand View Research has segmented the India solar PV panels market on the basis of technology, grid, and application:

India Solar PV Panels Technology Outlook (Revenue, USD Billion, 2018 - 2030)

  • Thin Film
  • Crystalline Silicon
  • Others

India Solar PV Panels Grid Outlook (Revenue, USD Billion, 2018 - 2030)

  • On Grid
  • Off Grid

India Solar PV Panels Application Outlook (Revenue, USD Billion, 2018 - 2030)

  • Residential
  • Industrial
  • Commercial

Download your FREE sample PDF copy of the India Solar PV Panels Market today and explore key data and trends.
From Orchard to Table: Insights into Fresh Pears Market Trends

Fresh Pears Market Growth & Trends

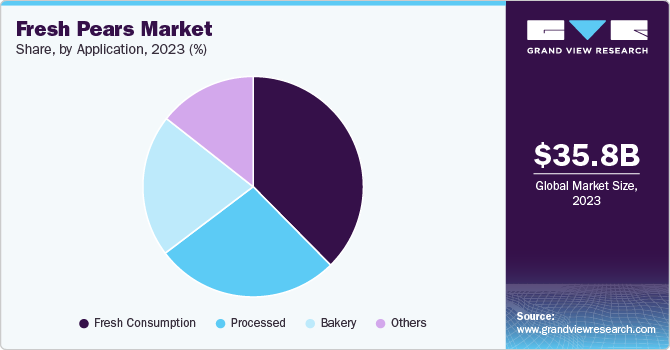
The global Fresh Pears Market was estimated at USD 35.76 billion in 2023 and is expected to grow at a CAGR of 6.3% from 2024 to 2030. One of the primary drivers behind the growth of the fresh pear industry is the increasing consumer trend towards health and wellness. As people become more health conscious, they actively seek nutritious food options. Fresh pears are rich in dietary fiber, vitamins, and antioxidants, making them appealing for consumers looking to enhance their diets. This shift towards healthier eating habits is particularly pronounced among younger demographics prioritizing organic and sustainably sourced produce.

The versatility of pears in culinary applications significantly contributes to their demand. Fresh pears are consumed as a snack and used in various dishes, including salads, desserts, and beverages. The growing interest in gourmet cooking and the incorporation of fresh fruits into meals have heightened the appeal of pears among chefs and home cooks alike. This trend is further supported by increased promotional efforts and marketing campaigns highlighting the diverse uses of fresh pears in home kitchens and restaurants.

Advancements in agricultural practices are another crucial factor driving market growth. Innovations such as precision farming, integrated pest management, and sustainable farming techniques enhance yield quality and quantity while reducing environmental impact. These practices help ensure a steady supply of high-quality fresh pears that meet consumer expectations for freshness and sustainability. Additionally, research into developing pest-resistant and climate-resilient pear varieties is expected to bolster production capabilities in the face of climate change challenges.

The rise of e-commerce platforms has transformed how consumers access fresh produce, including pears. Online grocery shopping has gained popularity, particularly following the COVID-19 pandemic, as consumers seek convenience and safety. This shift allows for greater visibility and distribution of fresh pears, making them more accessible to a broader audience. Vendors with a strong online presence can leverage this trend to reach new customers and enhance their market share.

Emerging markets, particularly in Asia-Pacific regions, present significant growth opportunities for the fresh pear industry. Rising disposable incomes and changing dietary preferences among consumers in these areas are driving demand for fresh fruits. As more consumers in these markets adopt healthier eating habits, the demand for fresh pears is expected to increase substantially. Companies targeting these regions can capitalize on this trend by tailoring their marketing strategies to local preferences.

Despite these growth drivers, the market faces challenges such as perishability, supply chain disruptions, and competition from alternative fruits. To mitigate these issues, market players are focusing on enhancing supply chain efficiency and investing in advanced storage solutions to maintain product quality during transportation. Additionally, developing value-added products like pear-based snacks or beverages can diversify revenue streams and attract a wider customer base. Understanding regional market dynamics will be essential for businesses aiming to adapt successfully to changing consumer behaviors and preferences.

Curious about the Fresh Pears Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Fresh Pears Market Report Highlights

  • Green Anjou pear was the leading segment, accounting for a market value of USD 15 billion in 2023. The growth of the Green Anjou pear category is primarily driven by its versatility and consumer preference for texture and flavor.
  • Conventional pear accounted for over 60% of the global market in 2023. The growth of conventional pears can be attributed to their established presence in the market and the efficiency of large-scale production methods.
  • Fresh consumption was the largest application of pear and accounted for a market of over USD 12.5 billion in 2023. The increasing health consciousness among consumers significantly drives the growth of fresh consumption of pears.
  • Asia Pacific fresh pears market was the largest market for and accounted for a revenue share of 59.58% in 2023. In the Asia-Pacific region, particularly in China, the fresh pear market is experiencing rapid growth.

Fresh Pears Market Segmentation

Grand View Research has segmented global dermatology excimer market report based on product, application, type, and region:

  • Type Outlook (Revenue, USD Billion, 2018 - 2030)
    • Conventional
    • Organic
  • Application Outlook (Revenue, USD Billion, 2018 - 2030)
    • Fresh Consumption
    • Bakery
    • Processed
    • Others
  • Product Outlook (Revenue, USD Billion, 2018 - 2030)
    • Green Anjou
    • Red Anjou
    • Bartlet
    • Red Bartlet
    • Others
  • Regional Outlook (Revenue, USD Billion, 2018 - 2030)
    • North America
      • U.S.
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
    • Asia Pacific
      • China
      • Japan
      • India
      • South Korea
      • Australia & New Zealand
    • Central & South America
      • Brazil
    • Middle East & Africa
      • Saudi Arabia

 Download your FREE sample PDF copy of the Fresh Pears Market today and explore key data and trends.
Protecting Investments: Trends in the Extended Warranty Market

Extended Warranty Market Growth & Trends

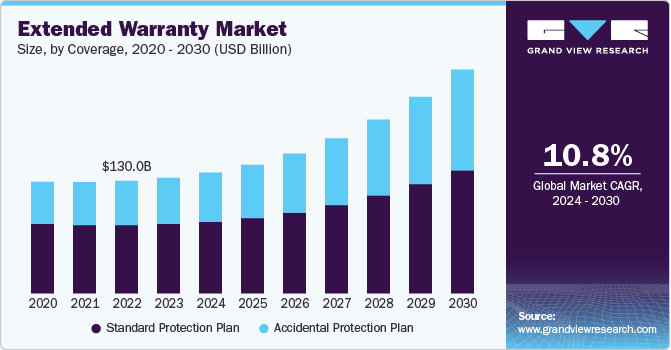
The global Extended Warranty Market size was estimated at USD 133.6 billion in 2023 and is projected to grow at a CAGR of 10.8% from 2024 to 2030 owing to the surge in sales of consumer electronics and home appliances. With the increasing penetration of smartphones, laptops, smart home devices, and kitchen appliances globally, the demand for extended warranties has grown significantly. These products often represent a significant investment for consumers, who seek the reassurance of coverage beyond the standard manufacturer warranty, especially in the case of repairs or replacements. As electronic devices become more sophisticated and prone to technical malfunctions, customers are increasingly purchasing extended warranties for peace of mind.

There has been a significant rise in consumer awareness regarding the benefits of extended warranties. Manufacturers, retailers, and third-party providers have improved their marketing strategies to educate consumers about the financial protection offered by these plans. The proliferation of e-commerce platforms has also facilitated the easy bundling of extended warranty packages with products, further driving their adoption. As more consumers recognize the value of protecting their investments, extended warranty uptake has steadily increased.

The rise of online retail has supported the extended warranty market by creating more opportunities for providers to offer coverage directly to consumers. E-commerce platforms allow retailers to upsell extended warranties while purchasing of products, making it convenient for consumers to opt into these plans. Online comparison tools and platforms that specialize in extended warranty products have also gained popularity, enabling consumers to make more informed decisions about coverage options.

Companies are leveraging extended warranties as a tool for customer retention. Offering extended warranties creates an ongoing relationship between the customer and the product or brand, which can lead to increased customer loyalty. Many manufacturers and retailers bundle warranties with loyalty programs or offer perks to consumers who purchase extended coverage. This focus on retention is particularly important in highly competitive markets, where retaining customers can provide a strategic advantage.

Curious about the Extended Warranty Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Extended Warranty Market Report Highlights

  • The standard protection plan segment accounted for the largest market share, over 60% in 2023.  The surge in sales of mid-range electronics, appliances, and other consumer goods is a major driver of the standard protection plan segment.
  • The manufacturers segment accounted for the largest market share of nearly 45% in 2023.  The rising cost of repairs and replacements is compelling consumers to seek additional protection beyond standard manufacturer warranties.
  • The consumer electronics segment accounted for the largest market share, over 33% in 2023.  Many extended warranty providers now offer installment-based payment options or bundle warranty costs into device financing plans.
  • The individuals segment accounted for the largest market share, over 68% in 2023.  Extended warranty providers are increasingly offering flexible payment plans, allowing individual consumers to spread out the warranty cost over time.
  • The extended warranty market in North America held a share of around 36% in 2023. The market in North America is characterized by high adoption rates across consumer electronics, automotive, and home appliances.

Extended Warranty Market Segmentation

Grand View Research has segmented the global extended warranty market report based on coverage, distribution channel, application, end use, and region. 

  • Coverage Outlook (Revenue, USD Billion, 2018 - 2030)
    • Standard Protection Plan
    • Accidental Protection Plan
  • Distribution Channel Outlook (Revenue, USD Billion, 2018 - 2030)
    • Manufacturers
    • Retailers
    • Others
  • Application Outlook (Revenue, USD Billion, 2018 - 2030)
    • Automobiles
    • Consumer Electronics
    • Home Appliances
    • Mobile Devices and PCs
    • Others
  • End-Use Outlook (Revenue, USD Billion, 2018 - 2030)
    • Individuals
    • Business
  • Regional Outlook (Revenue, USD Billion, 2018 - 2030)
    • North America
      • U.S.
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
    • Asia Pacific
      • China
      • India
      • Japan
      • South Korea
      • Australia
    • Latin America
      • Brazil
    • Middle East & Africa
      • U.A.E
      • Kingdom of Saudi Arabia
      • South Africa 

Download your FREE sample PDF copy of the Extended Warranty Market today and explore key data and trends.
Targeted Light Therapy: Exploring the Dermatology Excimer Laser Market

Dermatology Excimer Laser Market Growth & Trends

The global Dermatology Excimer Laser Market size is expected to reach USD 1.15 billion by 2030, registering a CAGR of 10.3% from 2024 to 2030, according to a new report by Grand View Research, Inc. Dermatology excimer lasers are a novel form of targeted phototherapy that delivers a specific wavelength (308 nm) of monochromatic UVB radiation using an excimer laser or an excimer lamp. According to NCBI, excimer lasers have been proven effective in treating skin conditions like psoriasis, vitiligo, atopic dermatitis, alopecia area ta, allergic rhinitis, folliculitis, etc.

Factors like the rising prevalence of skin conditions, such as eczema, the non-invasive nature of the procedures, and the advent of technologically advanced treatment systems, offering lower complication risks, are expected to propel market growth. Skin conditions that are generally considered difficult to treat, such as hypopigmented striae and hypopigmented scars, can also be effectively treated using excimers. Technological advancement and availability of an extensive range of devices in the market that offers high patient satisfaction and visible results are expected to boost the market growth.

The global market was adversely affected due to the COVID-19 pandemic as the footfall of patient appointments for skin treatments was temporarily suspended. However, the governments in many countries have allowed dermatology clinics to resume skin treatment consultations and aesthetic procedures by adhering to strict COVID-19 protocols. Moreover, many aesthetic professionals believe that there will be a surge in demand for beauty and aesthetic treatments post-COVID-19 crisis, which is expected to propel market growth.

Curious about the Dermatology Excimer Laser Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Dermatology Excimer Laser Market Report Highlights

  • The trolley-mounted excimer laser segment accounted for a revenue share of 43.6% in 2023 attributed to its versatility and efficiency in treating various skin conditions, including psoriasis, vitiligo, and atopic dermatitis.
  • Psoriasis held the largest market revenue share in 2023. The effectiveness of excimer lasers in targeting and treating localized psoriasis lesions has made them a preferred treatment option.
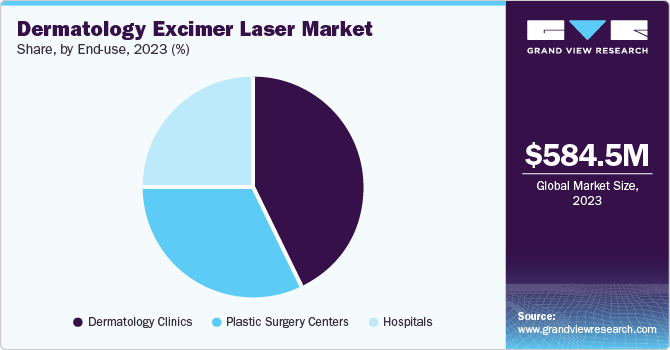
  • Dermatology clinics dominated the market in 2023. The prevalence of skin disorders such as psoriasis, vitiligo, and eczema, along with the increasing demand for effective and minimally invasive treatment methods, has propelled the adoption of excimer lasers in these clinical settings.
  • North America dermatology excimer laser market dominated the global market with a revenue share of 38.2% in 2023 attributed to the high prevalence of skin disorders, advanced healthcare infrastructure, and the presence of key market players in the region.

Dermatology Excimer Laser Market Segmentation

Grand View Research has segmented global dermatology excimer market report based on product, application, end-use, and region:

Dermatology Excimer Laser Product Outlook (Revenue, USD Million, 2018 - 2030)

  • Table top Excimer Lasers
  • Hand-held Excimer Lasers
  • Trolley Mounted Excimer Lasers

Dermatology Excimer Laser Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Psoriasis
  • Vitiligo
  • Atopic Dermatitis
  • Allergic Rhinitis
  • Alopecia Areata
  • Others

Dermatology Excimer Laser End-use Outlook (Revenue, USD Million, 2018 – 2030)

  • Hospitals
  • Dermatology Clinics
  • Plastic Surgery Centers

Dermatology Excimer Laser Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
    • Spain
    • Italy
    • Denmark
    • Sweden
    • Norway
  • Asia Pacific
    • India
    • Japan
    • China
    • Australia
    • South Korea
    • Thailand
  • Latin America
    • Brazil
    • Argentina
  • Middle East & Africa
    • South Africa
    • Saudi Arabia
    • UAE
    • Kuwait

Download your FREE sample PDF copy of the Dermatology Excimer Laser Market today and explore key data and trends.
Shaping the Future of Oncology: Breast Adenocarcinoma Treatment Trends

Breast Adenocarcinoma Treatment Market Growth & Trends

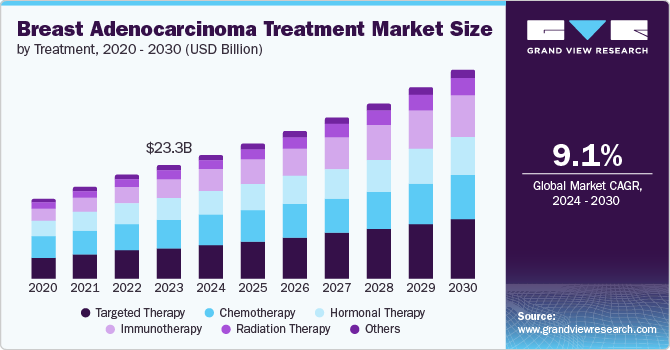
The global Breast Adenocarcinoma Treatment Market size is expected to reach USD 42.87 billion by 2030 and is projected to grow at a CAGR of 9.1% from 2024 to 2030, according to a new report by Grand View Research, Inc. This growth is significantly driven by the advancements in treatment technologies, the increasing prevalence of breast adenocarcinoma, and a growing focus on personalized medicine. According to the National Breast Cancer Foundation, in the U.S., 1 in 8 women will be diagnosed with breast cancer during their lifetime. For 2024, an estimated 310,720 women and 2,800 men are expected to be diagnosed with invasive breast cancer. The 5-year relative survival rate for breast cancer diagnosed at its earliest, localized stage is 99%. Advances in early detection and treatment have markedly improved survival rates in recent years, resulting in over 4 million breast cancer survivors currently living in the U.S.

Breast adenocarcinoma, a common form of breast cancer, is being addressed through a range of innovative treatments that include targeted therapies, immunotherapies, and hormonal therapies. The rise in market size can be attributed to the continual development of new drugs and therapies that enhance treatment efficacy and improve patient outcomes. In addition, the increasing awareness of breast cancer and the importance of early detection are contributing to a higher demand for advanced treatment options.

The increasing global burden of breast cancer, coupled with an aging population and rising incidence rates, is also fueling market expansion. As more patients seek advanced treatment options and healthcare systems invest in cutting-edge technologies, the market for breast adenocarcinoma treatments is set to grow significantly. Technological advancements in precision medicine, such as genomic profiling and biomarker identification, are enabling more personalized treatment approaches. These innovations allow for more effective targeting of cancer cells while minimizing side effects, thus enhancing the overall patient experience. Furthermore, ongoing research and clinical trials are likely to introduce novel therapies and combination treatments that could further drive market growth.

Curious about the Breast Adenocarcinoma Treatment Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Breast Adenocarcinoma Treatment Market Report Highlights

  • The targeted therapy segment held the largest share of 27.6 % in 2023. This prominence underscores the transformative impact of targeted therapies on breast cancer treatment, reflecting a shift towards more precise and effective treatment modalities.
  • The hospitals segment held the largest share of more than 60.0% in 2023. This growth is largely due to the high prevalence of breast cancer, which drives significant demand for hospital-based treatments.
  • Some of the prominent players in market are Merck & Co; Bristol Myers Squibb; Kyowa Kirin; Eisai Co. Ltd; Sanofi; Pfizer Inc; AstraZeneca; Novartis AG; Eli Lilly and Company; F. Hoffmann La Roche AG

Breast Adenocarcinoma Treatment Market Segmentation

Grand View Research has segmented the global breast adenocarcinoma treatment market based on treatment, end use, and region:

Breast Adenocarcinoma Treatment Outlook (Revenue, USD Billion, 2018 - 2030)

  • Chemotherapy
  • Targeted Therapy
  • Hormonal Therapy
  • Immunotherapy
  • Radiation Therapy
  • Other

Breast Adenocarcinoma Treatment End Use (Revenue, USD Billion, 2018 - 2030)

  • Hospitals
  • Specialty Clinics
  • Other

Breast Adenocarcinoma Treatment Regional Outlook (Revenue, USD Billion, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Norway
  • Asia Pacific
    • Japan
    • China
    • India
    • South Korea
    • Singapore
    • Australia
    • Thailand
  • Latin America
    • Brazil
    • Argentina
  • Middle East & Africa
    • South Africa
    • Saudi Arabia
    • UAE
    • Kuwait

Download your FREE sample PDF copy of the Breast Adenocarcinoma Treatment Market today and explore key data and trends.
Pioneering Progress: Artificial Organs and Bionics in the Healthcare Market

Artificial Organ and Bionics Market Growth & Trends

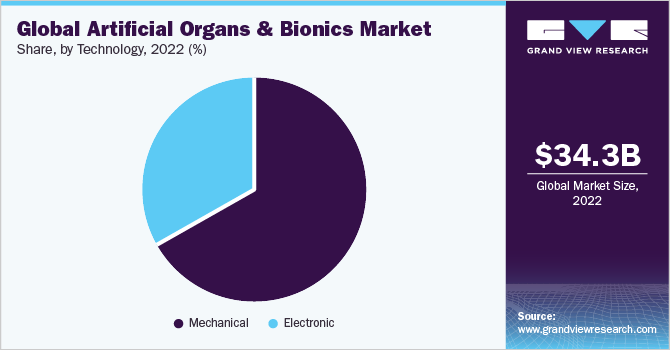
The global Artificial Organs and Bionics Market size is expected to reach USD 70.09 billion by the year 2030, expanding at a compound annual growth rate (CAGR) of 9.3% during the forecast period, according to a new report by Grand View Research, Inc. The increasing prevalence of organ failure has resulted in a massive increase in using human-made organs and bionics devices. The rising demand for donors to transplant kidneys, hearts, lungs, livers, and pancreas is a major factor boosting the market growth. Moreover, many biotechnology and medical device companies have concentrated on developing 3D printed bionic. These devices use myoelectric technology and sensory electric technology that enable the mobility of synthetic human body parts.

The COVID-19 pandemic had a detrimental effect on the artificial organ and bionics market. Patients with impairments and organ failures faced additional challenges due to the pandemic. Due to social distancing, many medical facilities were limited to non-elective procedures and surgeries and instead offered patients with impairments video conferencing to conquer market growth limitations. Moreover, there are treatment limitations that have hampered the growth of the market.

An increasing number of product launches and speedy FDA approval of these devices are bridging the shortage of donors. Rising R&D in synthetic human body parts is also boosting artificial organ and bionics market growth. For instance, on March 31, 2022, Edwards Lifesciences confirmed that the FDA certified the MITRIS RESILIA valve (a tissue valve replacement) that is specifically designed for the mitral position of the heart. Thus, with increasing healthcare expenditure and speedy FDA approval of synthetic human body parts, the market is expected to see robust growth during the forecast period.

Curious about the Artificial Organ and Bionics Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Artificial Organ and Bionics Market Report Highlights

  • The artificial organs segment generated the most revenue among all other segments in 2022 due to an escalating number of transplant procedures. The bionics segment is also expected to witness the highest CAGR owing to advancements in products
  • The kidney segment accounted for the largest market share of approximately 57.3% in the year 2022, owing to increasing kidney failures
  • The cochlear implant segment is expected to register the highest growth rate owing to the increasing geriatric population
  • North America was the leading regional segment in 2022 and is expected to maintain its position during the forecast period owing to the presence of advanced healthcare facilities

Artificial Organ and Bionics Market Segmentation

Grand View Research has segmented the global artificial organ and bionics market based on product, technology, and region:

Artificial Organs & Bionics Product Outlook (Revenue, USD Million, 2018 - 2030)

  • Artificial Organs
    • Kidney
    • Heart
    • Lungs
    • Liver
    • Pancreas
  • Artificial Bionics
    • Cochlear implant
    • Exoskeleton
    • Bionic limbs
    • Vision bionics
    • Brain bionics

Artificial Organs & Bionics Technology Outlook (Revenue, USD Million, 2018 - 2030)

  • Mechanical bionics
  • Electronic bionics

Artificial Organs & Bionics Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
  • Europe
    • U.K.
    • Germany
    • France
    • Italy
    • Spain
    • Denmark
    • Sweden
    • Norway
  • Asia Pacific
    • Japan
    • China
    • India
    • Australia
    • Thailand
    • South Korea
  • Latin America
    • Brazil
    • Mexico
    • Argentina
  • Middle East & Africa
    • South Africa
    • Saudi Arabia
    • UAE
    • Kuwait

Download your FREE sample PDF copy of the Artificial Organ and Bionics Market today and explore key data and trends.
AI in Healthcare Payers: Driving Efficiency and Innovation

AI For Healthcare Payer Market Growth & Trends

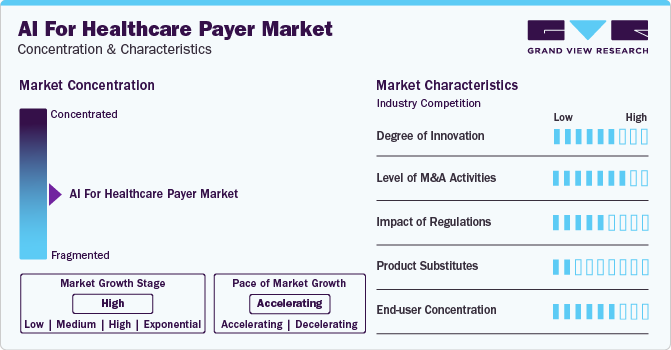
The global AI for Healthcare Payer Market size is expected to reach USD 3.58 billion by 2030 and is projected to grow at a CAGR of 9.40% from 2024 to 2030, according to a new report by Grand View Research, Inc. In the rapidly evolving landscape of healthcare, Artificial Intelligence (AI) is emerging as a transformative force within the healthcare payer market. As insurers and other healthcare payers strive to enhance operational efficiency, reduce costs, and improve patient outcomes, AI's role is becoming increasingly pivotal.

The healthcare industry faces complex challenges such as rising costs, increasing patient expectations, and the demand for higher-quality care. Healthcare payers, situated at the intersection of patients, providers, and stakeholders, manage finances and ensure access to essential services. These entities are leveraging advanced technologies like generative AI to enhance operational efficiency, improve decision-making, and deliver superior value.

Handling healthcare claims often creates significant bottlenecks for payers, with delays, errors, and inefficiencies prevalent. According to a Quantiphi article published in April 2024, the American Medical Association (AMA) reports that the average claim error rate among health insurers is 19.3%, resulting in approximately USD 17 billion in avoidable administrative costs annually. These inefficiencies burden the healthcare system and cause frustration for patients and physicians due to delays and additional administrative work. Technologies such as generative AI offer a solution by analyzing historical data to identify patterns, streamlining the claims process, reducing errors, and enhancing operational efficiency. This technology enables healthcare payers to increase productivity and better meet stakeholders' needs, ultimately improving outcomes for all involved.

The increasing demand for higher auto-adjudication rates, coupled with the need to reduce administrative costs and improve operational efficiency, is driving the adoption of AI solutions among healthcare payers. According to a survey conducted by HealthEdge Software, Inc. in January 2024, 69% of payers experience over 20% of their claims not being auto-adjudicated. This shortfall results in a high volume of claims, necessitating manual processing and secondary editing solutions. By leveraging machine learning and natural language processing, AI can accurately process claims, reduce the need for manual intervention, and minimize errors. This lowers administrative costs and accelerates the claims processing cycle, improving overall efficiency and customer satisfaction.

Companies providing AI-powered claims management and policy editing solutions are well-positioned to capitalize on this demand, offering significant value to payers through enhanced automation and cost savings. Consequently, addressing these inefficiencies and high costs is a critical driver for the growth and adoption of AI technologies in the healthcare payer market.

Curious about the AI for Healthcare Payer Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

AI For Healthcare Payer Market Report Highlights

  • Based on component, the software segment held the largest market share of over 58.0% in 2023. This segment is expected to grow at the fastest CAGR during the forecast period, driven by the increasing demand for automation in claims processing, fraud detection, and personalized member engagement. These advancements enhance operational efficiency, reduce costs, and improve decision-making.
  • Based on deployment, the cloud segment held the largest revenue share in 2023 and is expected to grow at the fastest CAGR over the forecast period. This can be attributed to the growing adoption of cloud-based technologies within the healthcare industry.
  • Based on application, the claims processing optimization segment held the largest revenue share in 2023. This can be attributed to the increasing complexity of claim processing and the demand for efficiency and improved accuracy in healthcare payer operations.
  • In 2023, North America dominated the global AI for healthcare payer industry with the largest revenue share. This growth can be attributed to rising healthcare expenditures, adoption of advanced technologies, and modernization of healthcare infrastructure. The Asia Pacific region is expected to grow at the fastest CAGR over the forecast period.

AI For Healthcare Payer Market Segmentation

Grand View Research has segmented the global AI for healthcare payer market based on component, deployment, application, and region:

AI For Healthcare Payer Component Outlook (Revenue, USD Million, 2018 - 2030)

  • Software
  • Services

AI For Healthcare Payer Deployment Outlook (Revenue, USD Million, 2018 - 2030)

  • Cloud
  • On-premise

AI For Healthcare Payer Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Claims Processing Optimization
  • Fraud Detection And Prevention
  • Revenue Management And Billing
  • Member Engagement And Personalization
  • Others

AI For Healthcare Payer Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Norway
    • Sweden
    • Denmark
  • Asia Pacific
    • Japan
    • China
    • India
    • Thailand
    • Australia
    • South Korea
  • Latin America
    • Brazil
    • Argentina
  • Middle East and Africa
    • Saudi Arabia
    • South Africa
    • UAE
    • Kuwait

Download your FREE sample PDF copy of the AI for Healthcare Payer Market today and explore key data and trends.
Renewable Energy Revolution: Clean Technology Market Insights

Clean Technology Market Growth & Trends

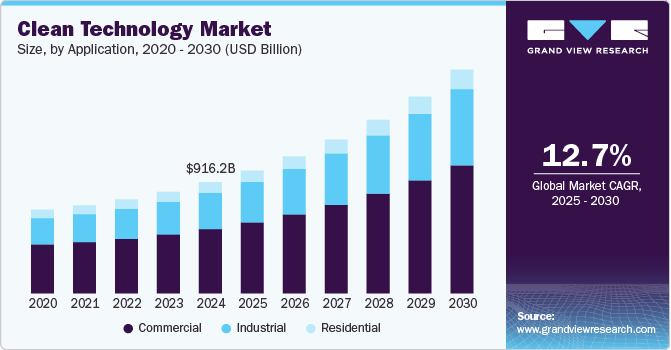
The global Clean Technology Market size was estimated at USD 916.20 billion in 2024 and is expected to grow at a CAGR of 12.7% from 2025 to 2030, driven by the urgent need to combat climate change, reduce environmental degradation, and transition to sustainable energy sources. Cleantech encompasses a wide range of innovations, including renewable energy technologies, energy storage, electric vehicles, water treatment, and waste management solutions. For instance, in October 2024, IBM Corporation acquired Prescinto, asset performance management (APM) software-as-a-service (SaaS) for renewables provider. Prescinto leverages AI to deliver analytics, automation, and advanced monitoring, optimizing operations of renewable energy and efficiently managing storage assets and clean energy.

Declining costs of renewable energy sources, such as solar and wind power, advancements in battery storage, and the proliferation of electric vehicles fuel the market growth. For instance, global solar capacity continues to expand, with technological innovations improving efficiency and affordability. Similarly, the rise of hydrogen as a clean energy vector and carbon capture technologies is transforming the industrial and energy landscapes. Businesses are actively investing in Cleantech not only to comply with regulations but also to capitalize on the growing demand for sustainable products and services. For instance, in March 2024, Ørsted A/S has been selected by the Department of Energy (DOE) Office of Clean Energy Demonstrations to start for federal funding of up to USD 100 million to build Star e-Methanol, a Power-to-X facility along the Texas Gulf Coast.

Supportive government policies, corporate sustainability goals, and increasing consumer awareness about the need for eco-friendly alternatives further accelerate the transition. Clean technologies are no longer niche solutions but have become mainstream, reshaping energy production, transportation, and industrial processes. Key regions such as North America, Europe, and Asia Pacific are leading the way in deploying these technologies, particularly in renewable energy projects and electric mobility. The rise of innovative solutions, such as hydrogen fuel cells, carbon capture, and circular economy practices, is opening new opportunities for growth across various sectors. As clean technologies continue to advance, they are expected to play a crucial role in building a sustainable and resilient global economy, fostering both environmental and economic progress.

Curious about the Clean Technology Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Clean Technology Market Report Highlights

  • The renewable energy technologies segment led the market in 2024, accounting for over 62% share of the global revenue. Renewable energy technologies are advancing due to cost reductions, innovation, and strong policy support.
  • The industrial segment dominated the global clean technology market in 2024. The industrial application segment of the clean technology market is driven by a combination of regulatory pressures, cost efficiencies, technological innovations, and societal demands.
  • Asia Pacific dominated the industry with a revenue share of over 50.0% in 2024. Countries such as China, India, Japan, and South Korea are leading the way in adopting renewable energy technologies, supported by ambitious targets to reduce carbon emissions and transition to sustainable energy systems.

Clean Technology Market Segmentation

Grand View Research has segmented the global clean technology market based on type, application, and region:

Type Outlook (Revenue, USD Million, 2017 - 2030)

  • Renewable Energy Technologies
  • Energy Storage Solutions
  • Energy Storage Solutions
  • Water and Waste Management
  • Agriculture and Food Systems
  • Air and Environment Management

Application Outlook (Revenue, USD Million, 2017 - 2030)

  • Residential
  • Commercial
  • Industrial

Regional Outlook (Revenue, USD Million, 2017 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
  • Asia Pacific
    • China
    • India
    • Japan
    • Australia
    • South Korea
  • Latin America
    • Brazil
  • Middle East and Africa
    • UAE
    • KSA
    • South Africa

Download your FREE sample PDF copy of the Clean Technology Market today and explore key data and trends.
eVTOL Aircraft: Transforming Cargo Delivery and Logistics

eVTOL Aircraft Market Growth & Trends

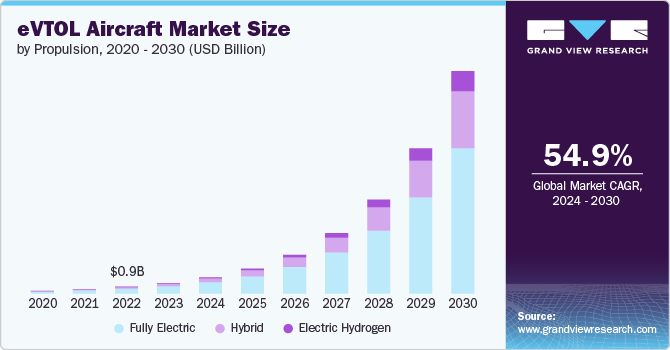
The global eVTOL Aircraft Market size was estimated at USD 1.35 billion in 2023 and is expected to grow at a CAGR of 54.9% from 2024 to 2030. The development and improvement in battery technologies are significant drivers for the eVTOL (electric Vertical Takeoff and Landing) aircraft market growth. As batteries become more powerful, lighter, and capable of faster charging times, eVTOLs can fly longer distances with shorter downtimes, making them more practical and appealing for urban air mobility and other applications. This technological leap enhances operational efficiency and expands the possible use cases for eVTOLs, from passenger drones to cargo delivery systems, thereby driving market growth.

Moreover, with global awareness and governmental policies shifting towards reducing carbon emissions and combating climate change, there's a growing demand for sustainable transport solutions. eVTOL aircraft represent a potential for eco-friendly urban air mobility by considerably reducing the reliance on ground transportation, which is often powered by fossil fuels. The push for more environment-friendly options is guiding financial investments and regulatory backing in favor of the electric aviation industry, which, in turn, is accelerating the expansion of the eVTOL aircraft market.

The integration of autonomous technologies into eVTOL designs is a significant driver for the market growth. Autonomy in aviation can increase safety by reducing human error, enhance efficiency through optimized route planning, and eventually reduce operational costs by potentially eliminating the need for pilots. The ongoing development of Artificial Intelligence (AI) and Machine Learning (ML) algorithms, sensors, and flight control systems paves the way for fully autonomous eVTOL services in the future, contributing to market growth.

Additionally, the establishment of regulatory frameworks and support from aviation authorities is crucial for the growth of the eVTOL market. Regulatory bodies such as the Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA) are working on developing guidelines and certifications specific to eVTOL operations. This regulatory clarity is essential for ensuring safety, standardization, and public trust in eVTOL aircraft. Government initiatives and policies that promote the adoption of innovative aviation technologies are also playing a significant role. As regulations become more defined and supportive, they will facilitate the wider adoption and commercial operation of eVTOL aircraft, driving market expansion in the coming years.

Furthermore, the global increase in urban population and the consequent rise in traffic congestion are increasing demand for eVTOL aircrafts. eVTOL aircraft offer a solution to bypass crowded urban streets, significantly reducing commute times and improving the quality of life for city residents. As cities continue to grow, the demand for efficient, time-saving transportation options like eVTOL aircraft is expected to rise, propelling the market forward.

Curious about the eVTOL Aircraft Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

eVTOL Aircraft Market Report Highlights

  • The propulsion segment dominated the market in 2023 with a market share of around 71%, due to advancements in battery technology, which are increasing energy density and reducing costs.
  • The surveillance & monitoring segment held the highest revenue share in 2023, due to advancements in autonomous technology, which enhance precision and efficiency in various monitoring tasks.
  • The piloted segment held the highest revenue share in 2023, due to increasing urbanization and the subsequent demand for efficient intra-city transportation solutions.
  • The intracity (20km-100km) & monitoring segment held the highest revenue share in 2023, due to increasing urban congestion and the demand for faster, more efficient transportation solutions.
  • The hardware segment accounted for the highest market share in 2023. The segment growth is driven by advancements in battery technology, propulsion systems, and lightweight materials.
  • The eVTOL aircraft market in North America accounted for the highest revenue share of nearly 42% in 2023, driven by the region's strong focus on technological innovation and a significant push towards reducing urban congestion through sustainable means.

eVTOL Aircraft Market Segmentation

Grand View Research has further segmented the global eVTOL aircraft market report based on propulsion, application, operation mode, range, system, and region:

Propulsion Outlook (Revenue, USD Million, 2018 - 2030)

  • Fully Electric
  • Hybrid
  • Electric Hydrogen

Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Cargo Transport
  • Passenger Transport
  • Mapping & Surveying
  • Special Mission
  • Surveillance & Monitoring
  • Others

Operation Mode Outlook (Revenue, USD Million, 2018 - 2030)

  • Piloted
  • Autonomous

Range Outlook (Revenue, USD Million, 2018 - 2030)

  • Intracity (20km-100km)
  • Intercity (Above 100Km)

System Outlook (Revenue, USD Million, 2018 - 2030)

  • Hardware
    • Aerostructure
    • Avionics
    • Electric Motor
    • Batteries and Fuel Cells
    • Others
  • Software

Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • Germany
    • UK
    • France
    • Italy
  • Asia Pacific
    • Japan
    • China
    • India
    • Australia
    • South Korea
  • Latin America
    • Brazil
  • Middle East and Africa (MEA)
    • UAE
    • Saudi Arabia
    • South Africa

Download your FREE sample PDF copy of the eVTOL Aircraft Market today and explore key data and trends.
A Deep Dive into the Electric Bus Battery Pack Market: Key Players and Innovations

Electric Bus Battery Pack Market Growth & Trends

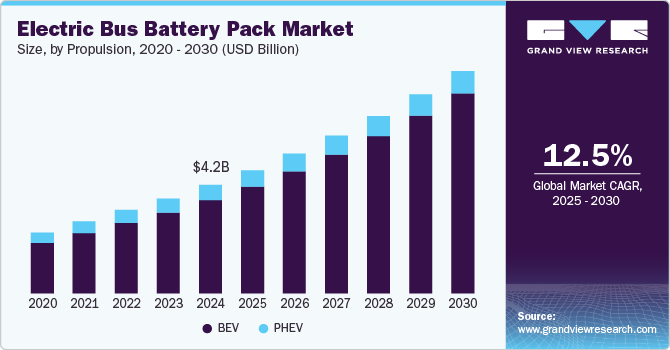
The global Electric Bus Battery Pack Market size was estimated at USD 4,292.2 million in 2024 and is expected to expand at a CAGR of 12.5% from 2025 to 2030. A growing global push for sustainable transportation and reduced emissions in urban areas. Cities worldwide are implementing strict environmental regulations and setting ambitious zero-emission goals, prompting transit authorities to transition their fleets from diesel to electric buses.

Government incentives and subsidies play a crucial role in market growth. Many countries offer substantial financial support to offset the higher initial costs of electric buses and their battery packs. China's New Energy Vehicle (NEV) subsidies have significantly boosted adoption, while the European Union's Clean Vehicles Directive mandates minimum procurement targets for clean buses. In the U.S., the Federal Transit Administration's Low or No Emission Vehicle Program provides funding for state and local governments to purchase electric buses and related infrastructure, thus boosting the market’s growth.

Rapid urbanization has led to a surge in public transportation demand, which necessitates efficient, eco-friendly alternatives to traditional buses. Cities worldwide are adopting electric buses to combat air pollution and reduce operational costs. For instance, Shenzhen, China, became the first city to fully electrify its bus fleet, deploying over 16,000 electric buses. This shift drives the demand for high-performance, long-lasting battery packs, as urban transit authorities prioritize vehicles with higher energy density and extended range.

Technological advancements and declining battery costs are also significantly benefiting the electric bus battery pack industry. The cost of lithium-ion batteries has decreased dramatically over the past decade, making electric buses more commercially viable. Improvements in battery chemistry and energy density have also addressed range anxiety concerns, with modern electric buses capable of operating for entire days on a single charge. For instance, BYD's latest battery packs offer ranges exceeding 300 kilometers, while manufacturers such as CATL and LG Energy Solution continue to develop advanced battery technologies with faster charging capabilities and longer lifespans. Additionally, innovations in battery thermal management systems have enhanced performance and safety, particularly in extreme weather conditions, making electric buses more reliable for year-round operation.

Curious about the Electric Bus Battery Pack Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Electric Bus Battery Pack Market Report Highlights

  • Based on the voltage rating, the electric bus battery pack industry is segmented into BEV and PHEV. BEV segment registered largest revenue market share of over 85.0% in 2024 and is expected to grow at the fastest CAGR of 13.4% during the forecast period.
  • Based on battery chemistry, the market is segmented into LFP, NCA, NCM, MNC, and others. The LFP (Lithium Iron Phosphate) segment accounted for the highest revenue market share of over 60.0% in 2024.
  • Asia Pacific dominated the market and accounted for the largest revenue share of over 55.0% in 2024. The region benefits from robust government support and ambitious clean transportation initiatives.

Electric Bus Battery Pack Market Segmentation

Grand View Research has segmented the global electric bus battery pack market report based on propulsion, battery chemistry, and region:

Propulsion Outlook (Revenue, USD Million, 2018 - 2030)

  • BEV
  • PHEV

Battery Chemistry Outlook (Revenue, USD Million, 2018 - 2030)

  • LFP
  • NCA
  • NCM
  • MNC
  • Others

Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • Germany
    • UK
    • France
    • Italy
    • Spain
    • Russia
  • Asia Pacific
    • China
    • India
    • Japan
    • Australia
  • Central & South America
    • Brazil
    • Argentina
  • Middle East & Africa
    • Saudi Arabia
    • UAE
    • South Africa

Download FREE sample PDF copy of the Electric Bus Battery Pack Market today and explore key data and trends.
The Future of Compression Socks in North America

North America Medical Compression Socks Market Growth & Trends

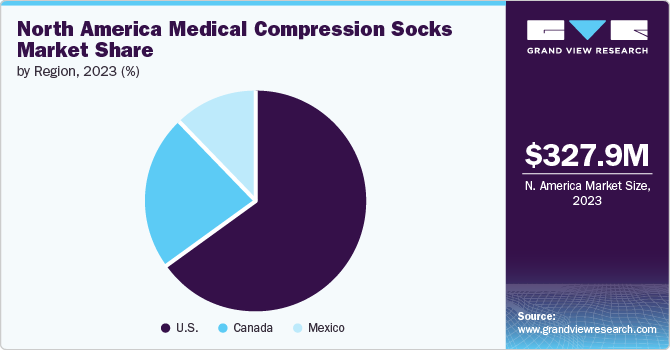
The North America Medical Compression Socks Market size is anticipated to reach USD 460.93 million by 2030, registering a CAGR of 5.07% from 2024 to 2030, according to a new report by Grand View Research, Inc. The demand for medical compression socks in the North American market is attributed to heightened health and wellness awareness. According to information from the American Heart Association, cardiovascular disease claims a life every 33 seconds. Compression socks are recognized for their effectiveness in enhancing blood circulation, reducing swelling, and relieving pain associated with cardiovascular conditions, positioning them as a vital component of preventive healthcare. This amplifies consumer adoption of medical compression socks for daily use. In 2021, according to the CDC, over 38 million Americans were reported to be affected by diabetes, influencing the expansion of the market.

Diabetes complications, such as neuropathy, poor circulation, and ulcers, can be managed with the use of medical compression socks, which improve blood flow and decrease pressure on affected areas, prompting healthcare providers to recommend them to patients with diabetes. North American medical compression socks market is driven by improved online accessibility and a diverse range of products available through e-commerce platforms. This enhanced online presence ensures consumers can easily find products that meet their needs and budgets, driving the demand. In addition, technological advancements in materials, design, and manufacturing processes result in high-quality compression socks offering better comfort, breathability, moisture management, and custom fit options. These innovations increase the appeal of medical compression socks to consumers looking for effective health management solutions.

Curious about the North America Medical Compression Socks Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

North America Medical Compression Socks Market Report Highlights

  • The athletes/sports people segment dominated the market share by the target group of 33.96% due to compression socks boosting performance by enhancing blood circulation, minimizing muscle tiredness, and providing focused support for muscles and joints. They help in quicker recovery after workouts by reducing muscle discomfort and swelling
  • The travelers segment is expected to grow significantly over the forecast period. Travelers prefer compression socks that mitigate risks and hold up well against regular wear and laundering, maintaining their efficacy. They are user-friendly and simple to slide on and off to meet the convenience needs of travelers while on the move
  • In February 2024, Italian socks knitting machine builder Busi Giovanni exhibited at Exintex, the International Textile Exhibition in Mexico at Puebla’s fairgrounds, from 27 February to 1 March 2024. They showcased their range of machines, including those capable of producing medical compression socks

North America Medical Compression Socks Market Segmentation

Grand View Research has segmented the North America medical compression socks marketbased on target group and region:

North America Medical Compression Socks Target Group Outlook (Revenue, USD Million, 2018 - 2030)

  • Athletes/Sports People
  • Travelers
  • Expecting/Young Moms
  • Sedentary Professionals
  • Others

North America Medical Compression Socks Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico

Download your FREE sample PDF copy of the North America Medical Compression Socks Market today and explore key data and trends.
Military Drone Technology Advancements: A Market Analysis

Military Drone Market Growth & Trends

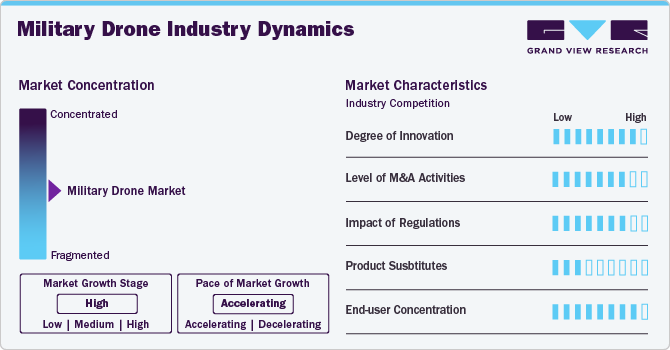
The global Military Drone Market size was estimated at USD 36,140.8 million in 2023 and is projected to grow at a CAGR of 13.8% from 2024 to 2030. The market is witnessing rapid technological advancements, with significant improvements in drone capabilities such as endurance, payload capacity, and stealth features. Innovations in materials science, battery technology, and miniaturization are enabling drones to fly longer, carry heavier loads, and avoid detection more effectively.

Integration of advanced sensors and AI-driven analytics enhances their operational efficiency, providing real-time data processing and decision-making capabilities. These advancements are expanding the adoption of drone applications in military operations, from surveillance and reconnaissance to combat and logistics.

Furthermore, there is a growing trend towards the adoption of autonomous and semi-autonomous drone systems in military operations. Autonomous drones can perform complex missions with minimal human intervention, reducing the risk to personnel and increasing mission success rates. The development of sophisticated algorithms for navigation, target recognition, and obstacle avoidance is driving market growth.

There is a noticeable shift towards smaller, tactical drones. These drones are designed for short-range missions and can be deployed quickly and discreetly. They are used extensively for intelligence, surveillance, and reconnaissance (ISR) missions, providing real-time situational awareness to ground troops. Their portability and ease of use make them ideal for urban warfare and counter-insurgency operations, where flexibility and rapid deployment are crucial.

Military drones are increasingly being integrated with other defense systems to create a cohesive and interconnected battlefield environment. This integration includes linking drones with ground-based radar systems, manned aircraft, and naval vessels, enabling seamless data sharing and coordinated operations. The concept of network-centric warfare, where various military assets are interconnected through a robust communication network, is driving market growth.

Moreover, as the use of military drones becomes more widespread, there is an increased focus on developing counter-drone technologies. These technologies aim to detect, identify, and neutralize hostile drones, protecting critical infrastructure and military assets. Counter-drone systems employ a variety of methods, including radar, RF jamming, and kinetic interception, to mitigate the threat posed by enemy drones. The rise in asymmetric warfare, where non-state actors and insurgent groups use commercial drones for attacks, has further accelerated the development and deployment of counter-drone solutions.

Curious about the Military Drone Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Military Drone Market Report Highlights

  • The rotary blade segment dominated the market in 2023 with a market share of around 78% due to its superior versatility and operational capabilities.
  • The remotely piloted segment held the largest revenue share in 2023 due to its established reliability and widespread adoption in military operations.
  • The intelligence, surveillance, and reconnaissance (ISR) segment accounted for the highest market share in 2023, driven by drones' critical role in gathering real-time data and enhancing situational awareness on the battlefield.
  • The visual line of sight (VLOS) segment held the largest revenue share in 2023 due to its simplicity, reliability, and ease of use in various operational scenarios.
  • The military drone market in North America accounted for a significant revenue share of over 40% in 2023, owing to the region's advanced defense infrastructure, substantial military budgets, and ongoing investments in cutting-edge technology.

Military Drone Market Segmentation

Grand View Research has further segmented the global military drone market report based on type, operation mode, range, application, and region.

Type Outlook (Revenue, USD Million, 2018 - 2030)

  • Fixed-Wing
  • Rotary Blade
  • Hybrid

Operation Mode Outlook (Revenue, USD Million, 2018 - 2030)

  • Remotely Piloted
  • Partially Autonomous
  • Fully Autonomous

Range Outlook (Revenue, USD Million, 2018 - 2030)

  • Visual Line of Sight (VLOS)
  • Extended Visual Line of Sight (EVLOS)
  • Beyond Visual Line of Sight (BVLOS)

Application Outlook (Revenue, USD Million, 2018 - 2030)

  • Intelligence, Surveillance and Reconnaissance (ISR)
  • Logistics & Supply
  • Others

Regional Outlook (Revenue, USD Million, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • Germany
    • UK
    • France
  • Asia Pacific
    • Japan
    • China
    • India
    • Australia
    • South Korea
  • Latin America
    • Brazil
  • Middle East and Africa (MEA)
    • UAE
    • Saudi Arabia
    • South Africa

Download your FREE sample PDF copy of the Military Drone Market today and explore key data and trends.
Unlocking the Potential of the Vanadium Market: Opportunities & Trends

Vanadium Market Growth & Trends

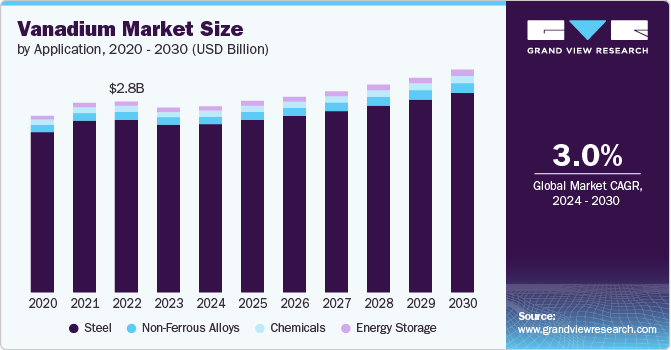
The global Vanadium Market size was estimated at USD 2.73 billion in 2023 and is estimated to grow at a CAGR of 3.0% from 2024 to 2030. Growing crude steel production on account of demand from construction, automotive, machinery, and transportation industries is expected to fuel the demand for vanadium over the coming years.

Vanadium is primarily used as an alloy in steel manufacturing, where it increases the strength, toughness, and wear resistance of steel. The global demand for high-strength steel in the construction, automotive, and aerospace sectors is on the rise, driving the demand for vanadium. As countries and companies invest in infrastructure and manufacturing, demand for vanadium is expected to observe growth. For instance, as reported by the World Steel Association, global crude steel production reached 1,892.6 million tons in 2023 from 1,878.6 million tons in 2019.

Vanadium is a key component in vanadium redox flow batteries (VRFBs), which are used for energy storage systems. Owing to shifts toward renewable energy sources, the demand for efficient, large-scale energy storage solutions is increasing. VRFBs are particularly suited for grid storage due to their scalability, long lifespan, and ability to discharge over a long period, making vanadium an essential material for the emerging clean energy economy. This shift represents a significant growth driver for the vanadium market as energy storage technologies become increasingly vital.

The nuclear energy sector represents a significant opportunity for vanadium products. In nuclear energy, vanadium alloys are highly valuable due to their low neutron-absorption characteristics and high temperature and corrosion resistance. These properties make vanadium-based alloys ideal for use in nuclear reactors, particularly in the construction of pressure vessels and structural components. The ability of vanadium alloys to withstand the harsh operating environments inside a nuclear reactor without significant degradation extends the service life of these components, enhancing the overall safety and efficiency of nuclear power plants.

Curious about the Vanadium Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Vanadium Market Report Highlights

  • Steel held the largest revenue share of over 90% in 2023. In superconducting magnets, vanadium plays a crucial role, especially in the form of Vanadium Gallium (V3Ga) superconductors.
  • Asia Pacific held over 62% revenue share of the global vanadium market. North America vanadium market is primarily driven by a strong focus on the aerospace and defense industry, which requires high-strength steel alloys.

Vanadium Market Segmentation

Grand View Research has segmented the global vanadium market report on the basis of application, and region.

Application Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)

  • Steel
  • Non-Ferrous Alloys
  • Chemicals
  • Energy Storage

Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)

  • Europe
    • Germany
    • UK
    • Russia
  • North America
    • U.S.
    • Canada
    • Mexico
  • Asia Pacific
    • China
    • India
    • Japan
    • South Korea
  • Central & South America
    • Brazil
  • Middle East & Africa

Download your FREE sample PDF copy of the Vanadium Market today and explore key data and trends.
Unlocking Opportunities in the HVAC Maintenance Services Market

HVAC Maintenance Services Market Growth & Trends

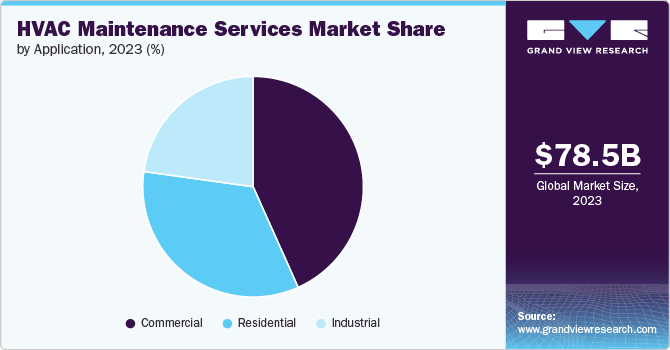
The global HVAC Maintenance Services Market size was estimated at USD 78.54 billion in 2023 and is projected to grow at a CAGR of 5.8% from 2024 to 2030. The market is currently experiencing robust growth, driven by several key factors. Firstly, the increasing awareness among consumers and businesses about the importance of maintaining HVAC systems for energy efficiency, longevity, and health benefits has significantly contributed to the market's expansion. Regular maintenance ensures that HVAC systems operate at optimum efficiency, leading to reduced energy consumption and lower utility bills. Additionally, well-maintained systems are less likely to suffer from unexpected breakdowns, reducing the need for costly repairs and replacements.

The rising demand for HVAC systems in the residential, commercial, and industrial sectors is also propelling the growth of the maintenance services market. The rapid urbanization and infrastructure development worldwide has resulted in an increased installation of HVAC systems in new buildings and facilities. This surge in installations has, in turn, led to a greater demand for professional maintenance services to keep these systems in prime condition. Furthermore, advancements in technology and the introduction of smart HVAC systems have made maintenance services more critical than ever, as these high-tech systems require specialized knowledge and skills for proper care and upkeep.

The regulatory changes and government initiatives aimed at promoting energy efficiency are likely to increase the demand for professional maintenance services that can ensure compliance with new standards. As the market continues to evolve, service providers who can offer innovative, cost-effective, and environmentally friendly maintenance solutions are expected to gain a competitive edge.

Curious about the HVAC Maintenance Services Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

HVAC Maintenance Services Market Report Highlights

  • The demand for repair segment is expected to grow at a CAGR of 6.3% from 2024 to 2030 in terms of revenue
  • The demand for heat pump segment is expected to grow at a CAGR of 6.6% from 2024 to 2030 in terms of revenue
  • The demand from the industrial application segment is expected to grow at a significant CAGR of 6.0% from 2024 to 2030 in terms of revenue
  • The Asia Pacific HVAC maintenance services market holds a significant share in the global HVAC market, primarily due to its expanding construction sector, increasing urbanization, and the rising demand for energy-efficient buildings.

HVAC Maintenance Services Market Segmentation

Grand View Research has segmented the global HVAC maintenance services market based on the service, product, application and region:

Service Outlook (Revenue, USD Billion; 2018 - 2030)

  • Repair 
  • Upgrade/Replacement

Product Outlook (Revenue, USD Billion; 2018 - 2030)

  • Air Handling Units
  • AC System
  • Air purifier
  • Heat Pump
  • Others

Application Outlook (Revenue, USD Billion; 2018 - 2030)

  • Residential
  • Commercial
  • Industrial

Regional Outlook (Revenue, USD Billion; 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
    • Italy
    • Spain
  • Asia Pacific
    • Japan
    • China
    • India
    • Australia
    • South Korea
  • Latin America
    • Brazil
    • Argentina
  • Middle East & Africa
    • South Africa
    • Saudi Arabia
    • UAE

Download your FREE sample PDF copy of the HVAC Maintenance Services Market today and explore key data and trends.

Impact of Construction Boom on U.S. Roofing Materials Industry

U.S. Residential and Commercial Roofing Materials Market Growth & Trends

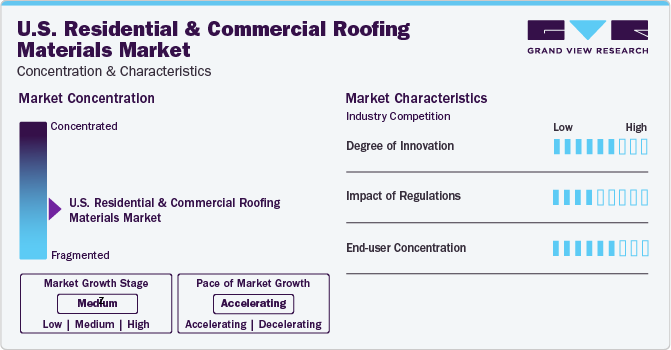
The U.S. Residential and Commercial Roofing Materials Market size is anticipated to reach USD 21.69 billion by 2030 and is projected to grow at a CAGR of 4.5% from 2024 to 2030, according to a new report by Grand View Research, Inc. The growth of the market may be attributed to a booming worldwide construction sector as a result of increased public and private investments in the creation of new residential spaces, and commercial spaces in the U.S. Roofing materials demand is increasing on account of stringent rules and regulations regarding the building codes and energy efficiency.

With a rise in severe weather conditions, there is a rise in demand for impact-resistant roofing materials, and this trend is expected to grow at a moderate pace during the forecast period. The surge in demand for single-family homes and commercial spaces is driving the need for roofing materials in the U.S. The growing emphasis on energy-efficient and sustainable building practices is further contributing to the growing demand for roofing materials. Additionally, factors such as a flourishing regional economy, population growth, higher investments in the renovation and redevelopment of both residential and commercial structures, and a strong recovery in the construction sector following the COVID-19 pandemic are fueling the demand for roofing materials throughout the forecast period.

Oxford Economics reported that the global construction industry's overall output reached USD 10.7 trillion in 2020, and it's anticipated to grow by approximately 42% in the coming years, reaching a projected size of USD 15.2 trillion by 2030. According to data from the U.S. Census Bureau, construction spending in the U.S. hit a seasonally adjusted annual rate (SAAR) of USD 1,844.1 billion in February 2023, growing at a 5.2% compared to the USD 1,753.1 billion SAAR recorded in February 2022. This growing trend is expected to continue in the coming years, contributing to the increased demand for U.S. residential and commercial roofing materials from 2024 to 2030.

In addition, the use of asphalt shingles in roofing materials is surging in the states across the U.S., owing to the prevailing trend of developing sustainable and green buildings for achieving energy efficiency through lower consumption for temperature control in the buildings. The utilization of asphalt shingles in roofing applications is cost-effective and results in low energy utilization. Lower installation cost and higher durability of the asphalt shingles tiles as compared to the other roofing materials makes it as an ideal choice for building roofing materials. The installation of asphalt shingles is easy, which further reduces the overall budget of construction projects across the U.S.

Curious about the U.S. Residential and Commercial Roofing Materials Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Residential and Commercial Roofing Materials Market Report Highlights

  • Asphalt shingles segment dominated the market and accounted for a share of 55.0% in terms of revenue in 2023. Asphalt shingles are extensively used in residential and commercial buildings to ensure increased energy efficiency. The lower installation and material cost of asphalt shingles as compared to the other roofing materials makes it an ideal choice for roofing materials in most of the states in the U.S.
  • Metal roofs segment is witnessing surged demand for use in commercial spaces owing to the increased durability and easier lower slope roof installation. They are used at low slope roofs where the installation of HVAC in larger spaces could be done on the roof saving the internal space
  • The residential end-use segment accounted for USD 15.72 billion in revenue share in 2023 and is anticipated to witness significant growth at a CAGR of 4.5% over the forecast period. The growth in the number of nuclear families in developing and developed states such as Texas, California, Florida, and Arizona is resulting in the growth of residential end-use
  • The commercial end use is anticipated to grow at a CAGR of 4.4% over the forecast period. This growth can be attributed to the rising demand for commercial spaces such as offices, warehouses, hotels & restaurants, shopping malls, and supermarkets
  • California dominates the market, accounting for USD 1.70 billion in 2023. The state’s flourishing economic growth, increased construction activities, and rising awareness regarding eco-friendly insulating roofing materials drive the growth.Moreover, the region is one of the largest consumers of U.S. residential & commercial roofing materials in the world. Factors such as increasing investment in affordable housing, smart city construction, and investment in the tourism sector are expected to boost the demand for U.S. residential & commercial roofing materials over the forecast period.

U.S. Residential and Commercial Roofing Materials Market Segmentation

Grand View Research has segmented the U.S. residential and commercial roofing materials market based on product, application, construction type, and region:

U.S. Residential & Commercial Roofing Materials Product Outlook (Volume, Million Square Feet; Revenue, USD Million, 2018 - 2030)

  • Asphalt Shingles
  • Metal Roofs
  • Plastics
  • Concrete Tiles
  • Clay Tiles
  • Others

U.S. Residential & Commercial Roofing Materials Application Outlook (Volume, Million Square Feet; Revenue, USD Million, 2018 - 2030)

  • Residential
  • Commercial

U.S. Residential & Commercial Roofing Materials Construction Type Outlook (Volume, Million Square Feet; Revenue, USD Million, 2018 - 2030)

  • New Construction
  • Re-roofing

U.S. Residential & Commercial Roofing Materials Regional Outlook (Volume, Million Square Feet; Revenue, USD Million, 2018 - 2030)

  • U.S.
    • California
    • Texas
    • Florida
    • Arizona
    • North Carolina
    • South Carolina
    • New Jersey
    • New York
    • Colorado
    • Georgia
    • Utah

Download your FREE sample PDF copy of the U.S. Residential and Commercial Roofing Materials Market today and explore key data and trends.

Thermoform Packaging Market: Key Statistics You Should Know

From ready-to-eat meals and supermarket meat trays to pharmaceutical blisters and electronics clamshells, thermoformed packaging sits quietl...