Lithium-Sulfur Battery Market Report Highlights Global Expansion

The global lithium-sulfur (Li-S) battery market size was estimated at USD 33.80 million in 2023 and is projected to reach USD 165.40 million by 2030, growing at a CAGR of 25.5% from 2024 to 2030. Market growth is driven by the rising demand for high-energy-density storage solutions, particularly in electric vehicles (EVs) and portable electronics. Li-S batteries offer significantly higher energy density than traditional lithium-ion batteries, enabling longer EV ranges and extended battery life for devices. The use of abundant and inexpensive sulfur also provides a potential cost advantage, making Li-S batteries an attractive and sustainable alternative for large-scale energy storage applications.
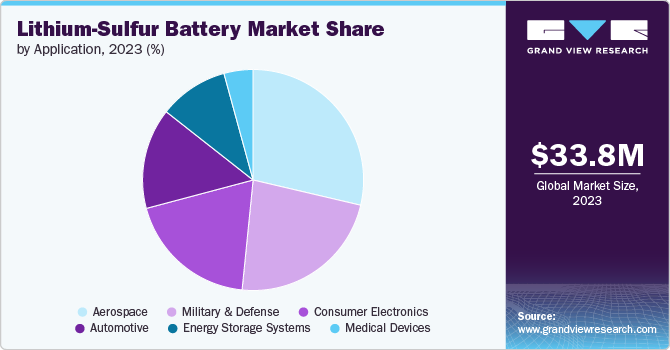
Despite strong growth prospects, the market faces technical challenges, such as the shuttle effect and structural degradation of the sulfur cathode during cycling. Ongoing research and advanced material innovations are addressing these issues, improving the performance and longevity of Li-S batteries.

Key Market Trends & Insights

  • Asia Pacific held the largest revenue share of 48.0% in 2023.
  • By battery capacity, the above 1000 mAh segment accounted for over 53.0% of revenue in 2023.
  • By type, the high energy density segment led with over 67.0% revenue share in 2023.
  • By application, the aerospace segment dominated with 28.0% revenue share in 2023.

Download a free sample PDF of the Lithium-Sulfur Battery Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 33.80 Million
  • 2030 Projected Market Size: USD 165.40 Million
  • CAGR (2024–2030): 25.5%
  • Asia Pacific: Largest market in 2023

Competitive Landscape

The lithium-sulfur battery market is highly competitive, driven by rapid technological advancements. Leading players include established battery manufacturers, automotive companies, and startups focused on Li-S innovation. Market share is influenced by R&D capabilities, partnerships with automotive or electronics firms, and efficient scalability of production.

Key Companies

  • PolyPlus Battery Company
  • NexTech Batteries Inc.
  • Li-S Energy Limited
  • Zeta Energy LLC
  • GS Yuasa Corporation
  • LG Energy Solutions Ltd.
  • Saft Groupe SA
  • Gelion PLC
  • Sion Power Corporation

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The lithium-sulfur battery market is poised for rapid growth, fueled by the need for high-energy-density, lightweight, and cost-effective storage solutions. Advances in materials and cell design are helping overcome technical challenges, while applications across EVs, aerospace, and portable electronics are expanding. With ongoing innovation and increasing adoption, the market is set to become a critical component of future energy storage technologies.
 

Juicer Market Regional Analysis Highlighting Emerging Growth Hotspots

The global juicer market size was estimated at USD 2.65 billion in 2023 and is projected to reach USD 4.37 billion by 2030, growing at a CAGR of 7.4% from 2024 to 2030. Market growth is driven by increasing health consciousness among consumers, particularly millennials, who are incorporating fresh juices into their diets as part of a wellness-focused lifestyle. Rising awareness of the benefits of fruits and vegetables, combined with convenience, has significantly boosted demand for juicers.

Technological advancements and product innovations are further fueling market expansion. Modern juicers offer higher efficiency, ease of use, enhanced nutritional retention, and smart features, making them accessible to a broader range of consumers. However, intense competition among manufacturers and quality control issues, such as motor failures, remain challenges that companies must navigate to maintain consumer trust and profitability.

Key Market Trends & Insights

  • Europe accounted for 36.7% of market share in 2023.
  • By product, centrifugal juicers led the market with USD 1.27 billion in revenue in 2023.
  • By technology, electric juicers held 75% revenue share in 2023.
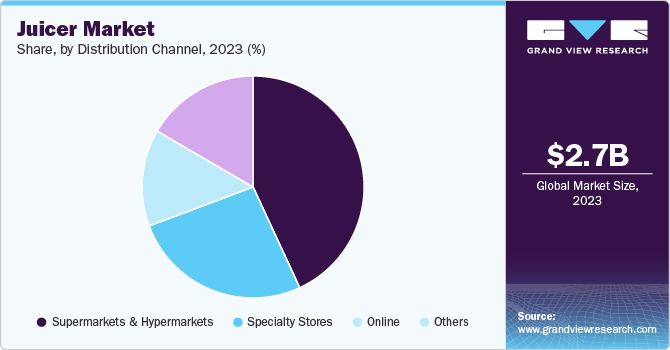
  • By distribution channel, supermarkets & hypermarkets generated the highest revenue of USD 1.14 billion in 2023.

Download a free sample PDF of the Juicer Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 2.65 Billion
  • 2030 Projected Market Size: USD 4.37 Billion
  • CAGR (2024–2030): 7.4%
  • Europe: Largest market in 2023

Competitive Landscape

The juicer market is highly competitive, with companies focusing on product innovation, multi-functionality, ease of cleaning, and smart integrations with mobile apps. Manufacturers are also emphasizing sustainability by incorporating eco-friendly materials into their products. Continuous investment in R&D is crucial for companies to differentiate their offerings and meet evolving consumer expectations.

Key Companies

  • Breville Group Ltd
  • Cuisinart Inc.
  • Electrolux AB
  • Omega Juicers
  • Hamilton Beach Brands Holding Co.
  • Koninklijke Philips N.V.
  • Panasonic Corporation
  • Hurom America Inc.

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The juicer market is poised for steady growth, driven by health-conscious consumer trends, technological innovation, and increasing demand for convenient and efficient juice preparation solutions. Companies focusing on smart, durable, and sustainable products are well-positioned to capitalize on this growth. Despite challenges from intense competition and quality control issues, the market outlook remains positive with continued expansion expected globally.


Iron Casting Market Size, Share, and Forecast Analysis to 2030

The global iron casting market size was estimated at USD 117.4 billion in 2024 and is projected to reach USD 172.4 billion by 2030, growing at a CAGR of 6.8% from 2025 to 2030. Market growth is primarily driven by rising investments in the railway sector and increasing demand for iron cast pipes in water infrastructure and oil & gas projects. Cast iron’s compressive strength and moldability make it a preferred material in industrial applications, while innovations in cookware and toxin-free kitchen products are supporting the gray cast iron segment.

The railway industry is expected to register a strong growth rate, with modernization projects replacing older cast-iron structures, such as the historic Mithi River Bridge in Mumbai, reflecting a broader industry shift toward more durable materials. Meanwhile, growing consumer preference for safe and durable cookware has prompted companies to expand production of enameled and toxin-free cast iron kitchenware.

Key Market Trends & Insights

  • Asia Pacific dominated the market with a 66.9% revenue share in 2024.
  • By product, gray cast iron accounted for over 64.0% of revenue in 2024.
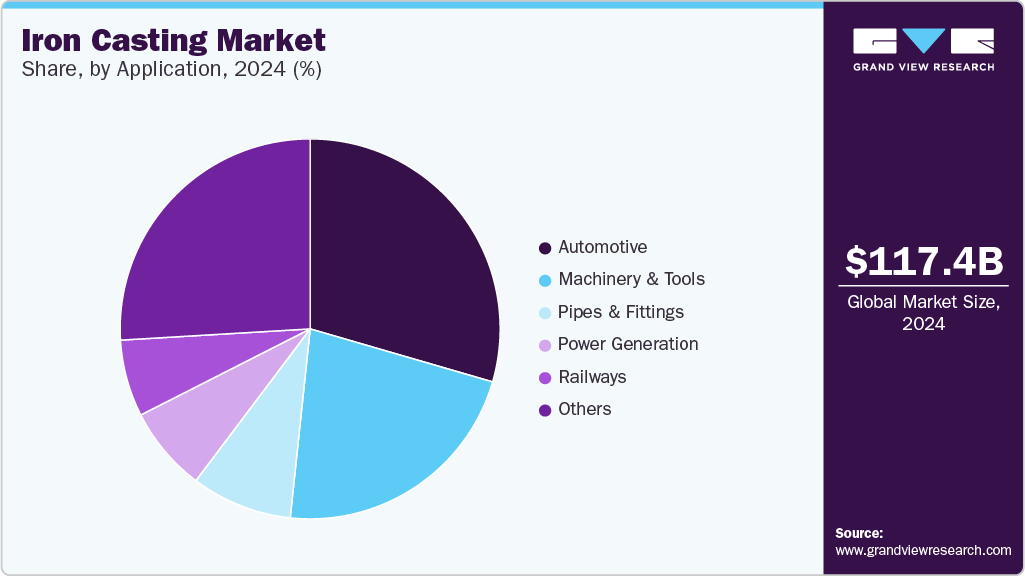
  • By application, the automotive industry held over 29% of revenue in 2024.

Download a free sample PDF of the Iron Casting Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 117.4 Billion
  • 2030 Projected Market Size: USD 172.4 Billion
  • CAGR (2025–2030): 6.8%
  • Asia Pacific: Largest market in 2024

Competitive Landscape

The iron casting market is competitive, with established global players leveraging technological expertise and expanding production capacities.

  • Proterial Ltd., founded in 1910 as Tobata Foundry, is a leader in high-performance materials with a history of strategic mergers and collaborations.
  • Dandong Foundry has nearly 70 years of experience producing gray and ductile iron castings, exporting half its output to countries including the U.S., Germany, and Japan.
  • Brakes India and other companies focus on innovation and global market expansion to maintain competitiveness.

Key Companies

  • Proterial Ltd.
  • LIAONING BORUI MACHINERY CO., LTD (DANDONG FOUNDRY)
  • Brakes India
  • OSCO Industries Inc.
  • Chamberlin
  • Crescent Foundry
  • Georg Fischer Ltd
  • Grupo Industrial Saltillo (GIS)
  • Newby Holdings Limited
  • Castings P.L.C.
  • CALMET

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The iron casting market is poised for steady growth, driven by increasing infrastructure investments, rising demand in the automotive sector, and growing consumer interest in durable and toxin-free kitchenware. Technological advancements, modernization of railway infrastructure, and expansion into global markets are expected to sustain market momentum. With a focus on quality, innovation, and efficiency, the industry is well-positioned to meet evolving industrial and consumer demands.


Image-Guided And Robot-Assisted Surgical Procedures Market Trends

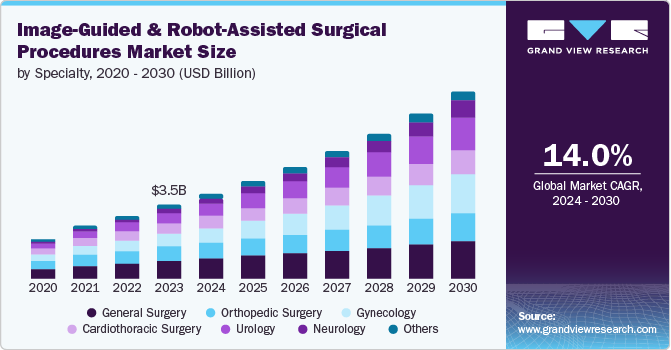
The global image-guided and robot-assisted surgical procedures market size was valued at USD 3.5 billion in 2023 and is projected to reach USD 8.9 billion by 2030, growing at a CAGR of 14.0% from 2024 to 2030. The market growth is driven by the rising incidence of chronic diseases, particularly cancer, and the increasing demand for advanced healthcare services. Technological advancements, such as the integration of robotics, augmented reality, and IoT-connected surgical instruments, are creating new opportunities and improving surgical precision.

The increasing number of complex surgeries, trauma cases, and a growing geriatric population are also contributing to market expansion. Hospitals and healthcare providers are investing heavily in state-of-the-art surgical equipment to ensure better patient outcomes, minimize errors, and enhance procedural efficiency. Image-guided and robot-assisted systems provide surgeons with enhanced visualization and accuracy, improving surgical results and patient safety.

Key Market Trends & Insights

  • North America dominated the market with a 50.5% revenue share in 2023.
  • The U.S. accounted for 88.2% of North America’s market.
  • By specialty, the general surgery segment held 24.2% of global revenue.
  • By end-use, hospitals led the market with a 56.4% share.

Download a free sample PDF of the Image-Guided And Robot-Assisted Surgical Procedures Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 3.5 Billion
  • 2030 Projected Market Size: USD 8.9 Billion
  • CAGR (2024–2030): 14.0%
  • North America: Largest market in 2023

Competitive Landscape

The market is highly competitive, with healthcare providers and hospitals investing in advanced surgical technologies to enhance patient care and operational efficiency.

  • Crouse Health operates multiple acute-care facilities serving thousands of inpatients and outpatients annually.
  • Apollo Hospitals Enterprise Ltd. provides integrated healthcare services including hospitals, diagnostic clinics, pharmacies, and telemedicine across multiple countries.
  • Other key players focus on developing innovative image-guided and robot-assisted procedures to strengthen their market presence.

Key Companies

  • Crouse Health
  • TH Medical
  • St. Clair Hospital
  • University of Washington
  • Atlantic Health System
  • HCA Healthcare UK
  • Apollo Hospitals Enterprise Ltd.
  • Medanta The Medicity
  • George Washington University Hospital
  • Charité - Universitätsmedizin Berlin

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The image-guided and robot-assisted surgical procedures market is poised for significant growth due to rising chronic disease prevalence, technological advancements, and increasing demand for precise and minimally invasive surgeries. Investments by hospitals and healthcare providers in advanced surgical systems are enhancing patient outcomes and procedural efficiency. As the adoption of robotic and image-guided solutions expands globally, the market is expected to continue its strong upward trajectory in the coming years.

Hybrid Cars Market Adoption of Automated Testing Boosts Product Quality

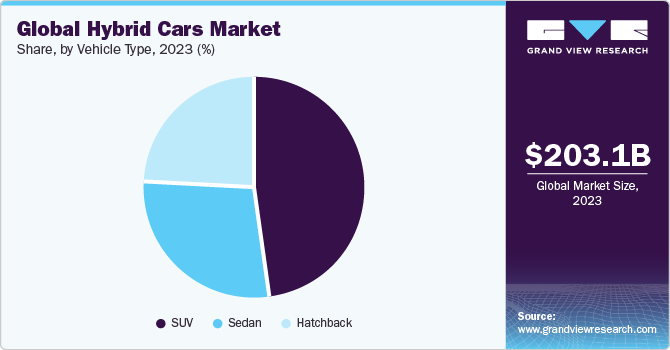
The global hybrid cars market size was estimated at USD 203.09 billion in 2023 and is projected to reach USD 457.27 billion by 2030, growing at a CAGR of 11.7% from 2024 to 2030. Market growth is driven by rising fuel price volatility and increasing consumer demand for vehicles that offer better fuel efficiency and lower operating costs. Hybrid cars, capable of switching between gasoline and electric power, allow drivers to reduce reliance on traditional fossil fuels while navigating fluctuating fuel prices.

Government incentives and subsidies promoting clean transportation are further fueling adoption. Tax credits, rebates, reduced registration fees, carpool lane access, and exemptions from congestion charges encourage consumers to choose hybrid vehicles. For example, in December 2023, the Japanese government announced a decade-long incentive program providing financial benefits for battery electric, hydrogen fuel-cell, and plug-in hybrid vehicles, promoting production and consumer adoption.

However, the higher upfront cost of hybrid cars remains a restraint, as it may deter price-sensitive consumers despite potential long-term fuel savings.

Key Market Trends & Insights

  • Asia Pacific dominated the global market with a 62.2% revenue share in 2023.
  • China is a key growth driver due to the focus on energy security and reduced reliance on imported oil.
  • By degree of hybridization, the full-hybrid segment held 47.2% of revenue in 2023.
  • By vehicle type, SUVs accounted for the largest revenue share.

Download a free sample PDF of the Hybrid Cars Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 203.09 Billion
  • 2030 Projected Market Size: USD 457.27 Billion
  • CAGR (2024–2030): 11.7%
  • Asia Pacific: Largest market in 2023

Competitive Landscape

The hybrid cars market is highly competitive, with leading players investing in technological advancements, efficiency improvements, and luxury innovations.

  • Toyota continues to advance its Hybrid Synergy Drive system, including models like the Prius with regenerative braking and efficient powertrain designs.
  • Tesla has introduced plug-in hybrid models such as the Model S and Model X, combining electric powertrains with extended range capabilities.
  • BMW focuses on luxury hybrids through its iPerformance lineup, including models like the i8, incorporating lightweight materials and advanced plug-in hybrid technology.

Key Companies

  • TOYOTA MOTOR CORPORATION
  • Lexus
  • Honda
  • BMW AG
  • Tesla
  • Volkswagen Group
  • Chevrolet
  • AUDI AG
  • Mercedes-AMG GmbH
  • Porsche
  • Kia Corporation

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The hybrid cars market is set for strong growth driven by increasing fuel efficiency concerns, government incentives, and rising consumer preference for environmentally friendly transportation. Technological advancements in hybrid powertrains, combined with innovation in luxury and SUV segments, are enhancing market appeal. Despite higher upfront costs, long-term savings and supportive policies are expected to encourage widespread adoption, positioning the market for sustained expansion globally.


Hummus Market Driven by Rising Awareness of Gluten-Free Products

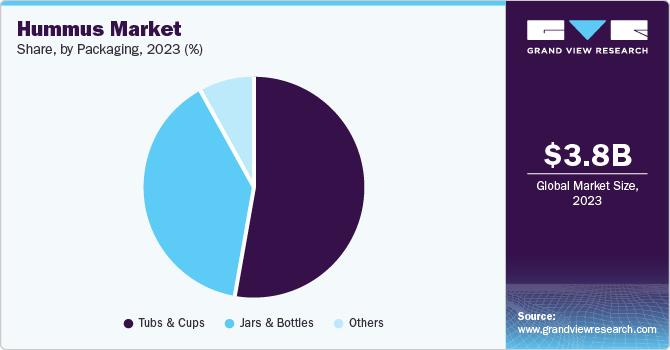
The global hummus market size was estimated at USD 3.85 billion in 2023 and is projected to reach USD 8.03 billion by 2030, growing at a CAGR of 11.1% from 2024 to 2030. The market is witnessing strong growth, driven by changing consumer preferences and lifestyle trends. Increasing health consciousness is encouraging consumers to opt for nutritious, plant-based foods, and hummus—rich in protein and fiber—has emerged as a popular choice among vegetarians, vegans, and health-focused individuals seeking convenient and wholesome dietary options.

However, the market faces challenges that could impact growth. Product adulteration, including contamination with harmful ingredients or improper labeling, has led to recalls and affected consumer trust. Notable instances, such as salmonella contamination and undeclared allergens, involving major brands like Sabra and Wegmans, have underscored the importance of stringent quality control. Additionally, competition from alternative plant-based dips, such as tahini and salsa, may divert consumer attention and sales away from hummus products.

Key Market Trends & Insights

  • North America was the largest revenue-generating market, accounting for nearly USD 1.95 billion in 2023.
  • The U.S. hummus market is expected to register the fastest CAGR during the forecast period.
  • By product, the classic hummus segment generated USD 1.62 billion in 2023.
  • By packaging, the tubs & cups segment held the largest market share of over 50% in 2023.

Download a free sample PDF of the Hummus Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 3.85 Billion
  • 2030 Projected Market Size: USD 8.03 Billion
  • CAGR (2024–2030): 11.1%
  • North America: Largest market in 2024

Competitive Landscape

The hummus market is highly competitive, with both established and emerging brands striving to capture market share. Companies are focusing on innovative flavors, enhanced packaging, partnerships with retailers and foodservice providers, and strategic marketing campaigns to increase brand visibility and drive growth.

Key Companies

  • Bakkavor Group Plc
  • Cedar’s Mediterranean Foods, Inc.
  • Haliburton International Foods
  • Strauss Group
  • Tribe Hummus
  • Hope Foods, LLC
  • Fountain of Health
  • Hummus Goodness
  • Boar’s Head Brand
  • Lantana Foods

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The hummus market is set for robust growth, driven by rising health consciousness, the popularity of plant-based diets, and increasing demand for convenient and nutritious snacks. While product safety concerns and competition from alternative dips present challenges, continuous innovation, quality control, and strategic marketing are expected to sustain market expansion. The market is poised to capitalize on evolving consumer preferences and the global shift toward healthier eating habits.


Hoverboard Market Regional Insights: Europe Leads in Safety Features

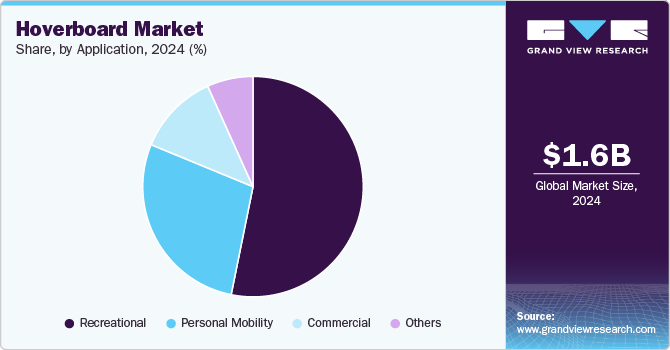
The global hoverboard market size was estimated at USD 1.62 billion in 2024 and is projected to reach USD 2.35 billion by 2030, growing at a CAGR of 6.6% from 2025 to 2030. Hoverboards are increasingly popular among younger consumers as fun, trendy, and compact mobility devices. Rising urban congestion, environmental awareness, and the desire for emission-free short-distance travel are driving demand.

Technological advancements, including improved battery life, motor power, safety features, self-balancing technology, and smart connectivity, are enhancing the riding experience. Ruggedized models with off-road capabilities are expanding appeal among adventure enthusiasts. The availability of hoverboards through online platforms, coupled with competitive pricing, detailed product information, and influencer marketing, has further accelerated adoption globally.

Key Market Trends & Insights

  • Asia Pacific dominated with a 34.99% share in 2024.
  • Double-wheel type accounted for 67.13% of global revenue.
  • 6.5-inch wheel size held a 62.81% revenue share.
  • Offline distribution represented 62.82% of revenue.
  • Recreational applications contributed 53.18% of revenue.

Download a free sample PDF of the Hoverboard Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 1.62 Billion
  • 2030 Projected Market Size: USD 2.35 Billion
  • CAGR (2025–2030): 6.6%
  • Asia Pacific: Largest market in 2024

Competitive Landscape

The hoverboard market is competitive, with manufacturers focusing on product innovation, regional production, and consumer-centric features. Companies pursue joint ventures, partnerships, mergers, and acquisitions to expand reach and strengthen their market position while complying with international regulatory standards and raising consumer awareness.

Key Companies

  • Ninebot Inc.
  • HaloBoard
  • Segway Inc.
  • TOMOLOO Technology Industrial Co. Ltd.
  • SURFUS
  • Hangzhou Chic Intelligent Technology Co.
  • Shenzhen Rooder Technology Co. Ltd.
  • JIALIKE Electronic Company Ltd.
  • Airwheel Technology Co. Ltd.
  • Razor USA LLC

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The hoverboard market is poised for steady growth, fueled by the demand for convenient, eco-friendly, and recreational mobility solutions. Technological advancements and smart features are enhancing user experience, while offline and online distribution channels ensure broad accessibility. Marketing initiatives, influencer collaborations, and product innovation continue to drive consumer adoption, supporting sustained market expansion worldwide.


Horse Riding Equipment Market Leaders Focus on Smart Gear Design

The global horse riding equipment market size was estimated at USD 1.60 billion in 2023 and is projected to reach USD 2.72 billion by 2030, growing at a CAGR of 7.8% from 2024 to 2030. Market growth is driven by the rising popularity of equestrian activities, increasing disposable incomes, and a growing focus on safety and comfort for both riders and horses. Innovations in product design, marketing strategies, and distribution networks are enabling manufacturers to cater to evolving consumer preferences.

Technological advancements, such as the use of lightweight and durable materials, smart features, and sustainable production practices, are shaping the market. Collaborations with equestrian associations, event organizers, technology firms, and fashion brands are further enhancing product offerings and market reach. The emphasis on safety, performance, and style is encouraging consumer adoption, while eco-friendly initiatives are contributing to sustainable growth.

Key Market Trends & Insights

  • North America captured over 35.24% revenue share in 2023.
  • The U.S. market is projected to grow at a significant CAGR from 2024 to 2030.
  • Helmet segment accounted for 27.05% of global revenue in 2023.
  • Mass price range contributed 80.52% of global revenue in 2023.
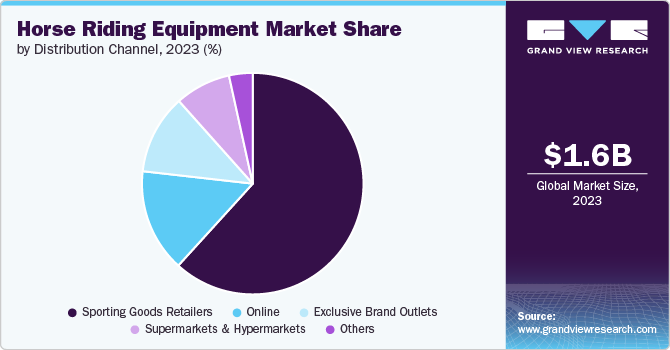
  • Sporting goods retailers accounted for 61.75% of sales in 2023.

Download a free sample PDF of the Horse Riding Equipment Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 1.60 Billion
  • 2030 Projected Market Size: USD 2.72 Billion
  • CAGR (2024–2030): 7.8%
  • North America: Largest market in 2023

Competitive Landscape

The horse riding equipment market is highly competitive, driven by product innovation, regional production capabilities, and changing consumer preferences. Leading companies invest in R&D, technological advancements, and strategic collaborations, including joint ventures, partnerships, and acquisitions, to expand their geographical presence and strengthen market positions. By focusing on quality, performance, and regional preferences, key players maintain a strong foothold in international markets.

Key Companies

  • Colonial Saddlery
  • Dainese
  • Georg Kieffer Sattlerwarenfabrik GmbH
  • Decathlon
  • Cavallo GmbH
  • Antares Sellier
  • Fabtron Inc.
  • Mountain Horse
  • HKM Sports Equipment
  • Charlie1Horse

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The horse riding equipment market is poised for steady growth, fueled by increasing participation in equestrian sports and rising consumer demand for safety, comfort, and style. Technological innovations, sustainable practices, and strategic collaborations are driving product development and market expansion. With growing awareness of performance and eco-friendly solutions, the market is expected to continue evolving and capturing new opportunities worldwide.


Honeymoon Tourism Market Poised for Growth with Digital Bookings

The global honeymoon tourism market size was estimated at USD 131.56 billion in 2024 and is projected to reach USD 191.85 billion by 2030, growing at a CAGR of 6.6% from 2025 to 2030. The market is driven by the growing influence of social media and travel influencers, which inspire couples to explore new destinations and luxury experiences. Increasing demand for personalized and experiential travel, including adventure, eco-friendly, and culturally immersive options, is also propelling market growth.

The proliferation of online travel agencies (OTAs) has made honeymoon planning more convenient and accessible, offering curated packages, exclusive deals, and destination guidance. Additionally, the rising trend of destination weddings is boosting demand, as couples often combine their wedding and honeymoon into a single extended trip, leading to seamless, all-inclusive travel experiences.

Key Market Trends & Insights

  • Europe dominated the global market with a 39.3% revenue share in 2024.
  • By type, beach honeymoon led the market with 26.3% revenue share.
  • 7 to 10-day trips held the largest duration segment.
  • 25–35 years age group accounted for the largest share.
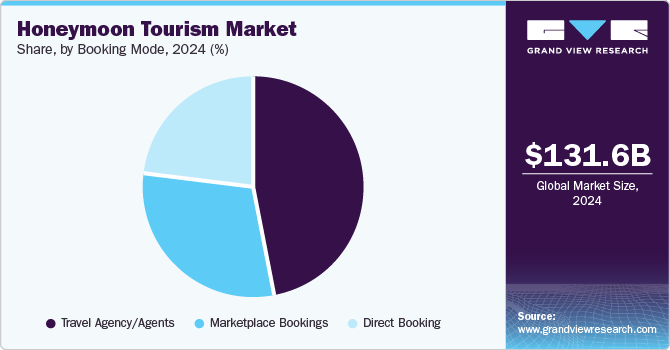
  • Travel agency/agents dominated the booking mode segment.

Download a free sample PDF of the Honeymoon Tourism Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 131.56 Billion
  • 2030 Projected Market Size: USD 191.85 Billion
  • CAGR (2025–2030): 6.6%
  • Europe: Largest market in 2024

Competitive Landscape

Key players in the honeymoon tourism market include Booking.com, Marriott International, Inc., and Thomascook.in, among others. These companies focus on offering tailored experiences, luxury accommodations, and curated packages for newlyweds. Through digital platforms and strategic partnerships, they enhance convenience, personalization, and customer engagement, catering specifically to the needs of honeymooners.

Key Companies

  • Booking.com
  • Abercrombie & Kent Ltd.
  • Flight Centre Travel Group Limited
  • Marriott International, Inc.
  • Thomascook.in
  • MakeMyTrip Limited
  • Expedia, Inc.
  • Bookmundi.com
  • Exodus Travels

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The honeymoon tourism market is experiencing steady growth fueled by rising demand for personalized, experiential travel and the influence of social media and travel influencers. Online travel platforms and OTAs are making planning and booking seamless, while the trend of destination weddings is creating integrated travel opportunities. Luxury and tailored experiences, along with technology-enabled services, continue to enhance customer satisfaction and market expansion. The combination of evolving consumer preferences and innovative offerings positions the market for sustained growth in the coming years.


Home Insurance Market Expands with Blockchain-Enabled Solutions

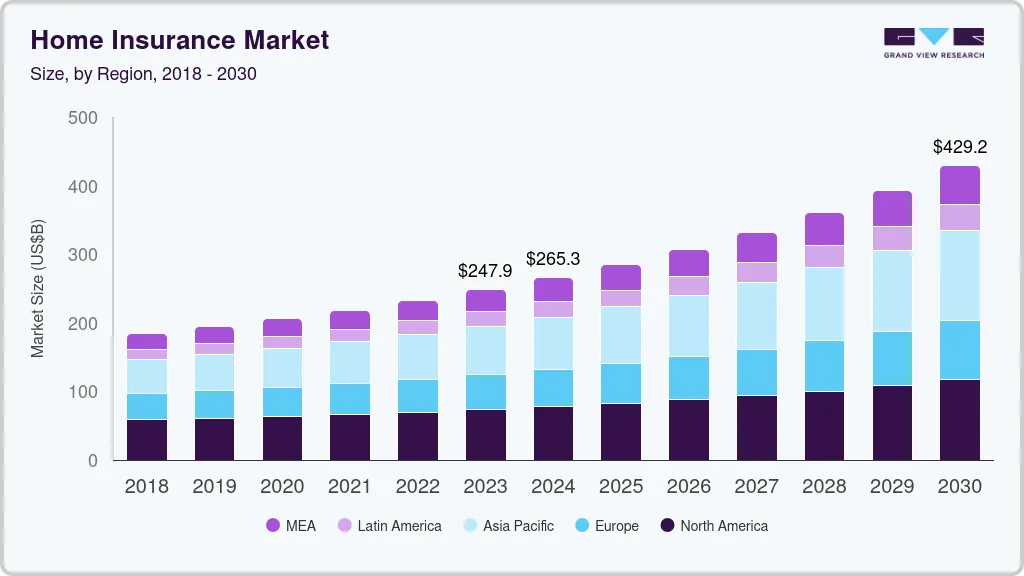
The global home insurance market size was estimated at USD 247.92 billion in 2023 and is projected to reach USD 429.24 billion by 2030, growing at a CAGR of 8.3% from 2024 to 2030. Home insurance, also referred to as household or homeowner’s insurance, provides financial protection against property damage, loss, and liability. The market is driven by growing demand for customized insurance products, rising awareness of homeownership risks, and the adoption of technology-enabled solutions such as AI, blockchain, data analytics, and geolocation to enhance services and customer experience.

Urbanization and the expansion of residential real estate, especially in developing regions, are further boosting demand for home insurance. Insurance providers are offering flexible coverage options and leveraging digital transformation to improve distribution, manage renter’s insurance, and provide personalized services.

Key Market Trends & Insights

  • North America home insurance market is expected to experience significant growth.
  • The U.S. market is projected to register substantial growth.
  • Comprehensive coverage led the market with 38.2% of global revenue in 2023.
  • Brokers accounted for the largest distribution channel revenue share.
  • Landlords held a significant end-use market revenue share.

Download a free sample PDF of the Home Insurance Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 247.92 Billion
  • 2030 Projected Market Size: USD 429.24 Billion
  • CAGR (2024–2030): 8.3%

Competitive Landscape

The home insurance market is highly competitive, with traditional insurers and new entrants offering innovative, technology-driven, and customer-focused solutions. Expansion strategies include entering new regions and gaining regulatory approvals to write multi-peril insurance lines, as exemplified by Tailrow Insurance Company’s entry into Florida in April 2023.

Key Companies

  • Zurich
  • Chubb
  • American International Group, Inc.
  • Liberty Mutual Insurance
  • Admiral
  • State Farm Mutual Automobile Insurance Company
  • Allstate Insurance Company
  • Allianz
  • PICC
  • Nationwide

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The home insurance market is witnessing robust growth driven by increasing homeownership, urbanization, and demand for tailored insurance solutions. Technological innovations are enhancing service delivery and customer engagement, while competition among insurers is expanding coverage options and improving accessibility. Ongoing digital transformation and strategic market expansions are expected to further strengthen the market landscape and provide consumers with more comprehensive protection.

Holter Monitor Market Poised for Expansion Amid Rising Heart Diseases

The global holter monitors market size was estimated at USD 1.45 billion in 2022 and is projected to reach USD 3.05 billion by 2030, growing at a CAGR of 9.7% from 2023 to 2030. The market growth is driven by the increasing prevalence of atrial fibrillation (AFib), an aging population, and a rising incidence of cardiovascular diseases (CVD). Additionally, a growing preference for ambulatory monitoring, technological innovations, enhanced arrhythmia detection capabilities, and supportive regulatory policies are further propelling market expansion.

AFib, a common and often underdiagnosed heart rhythm disorder, requires continuous monitoring for accurate diagnosis and management. The European Society of Cardiology (ESC), in its 2023 guidelines, recommended 24–48-hour Holter monitoring for identifying AFib and non-sustained ventricular tachycardia (NSVT) in hypertrophic cardiomyopathy (HCM) patients, fueling demand. Moreover, extended ECG monitoring has proven effective in detecting AFib in individuals with cryptogenic stroke or post-pulmonary vein isolation, strengthening market momentum.

According to the Centers for Disease Control and Prevention (CDC), in 2021, coronary artery disease (CAD) accounted for 375,476 deaths, with about 5% of adults aged 20 and above suffering from CAD. Nearly 20% of CAD-related deaths occurred in individuals under 65, underscoring the need for continuous heart monitoring. Similarly, the American Heart Association (AHA) reported in 2023 that 70% of the elderly population is at risk of CVD, creating demand for pacemakers and complementary monitoring devices such as Holter monitors. These devices also play a vital role in evaluating the performance of leadless pacemakers and detecting irregularities during daily activities.

Key Market Trends & Insights

  • North America dominated the market with the largest share of 42.8% in 2022.
  • By component, the wired segment led with a 63.54% revenue share in 2022.
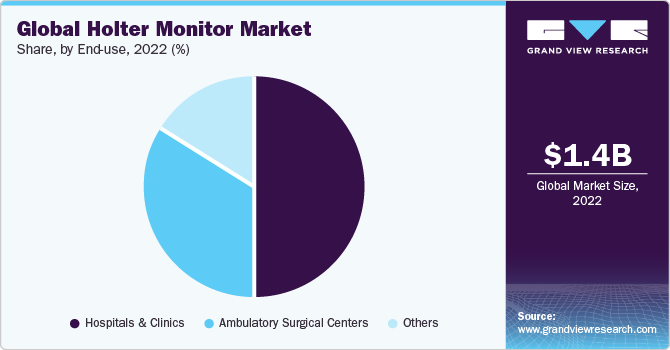
  • By end-use, hospitals & clinics held the largest share at 50.42% in 2022.
    Download a free sample PDF of the Holter Monitor Market Intelligence Study, published by Grand View Research.

Download a free sample PDF of the Holter Monitor Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2022 Market Size: USD 1.45 Billion
  • 2030 Projected Market Size: USD 3.05 Billion
  • CAGR (2023–2030): 9.7%
  • North America: Largest market in 2022
  • Asia Pacific: Fastest growing market

Competitive Landscape

Key players are pursuing strategies such as new product launches, expansions, acquisitions, collaborations, and product upgrades. In March 2023, Koninklijke Philips N.V. presented research findings at the World Congress of Cardiology demonstrating that extending monitoring duration using its ePatch Holter device increased clinically actionable findings by two times after 7 days and 2.5 times after 14 days. This underscores the strong growth potential of extended monitoring technologies, prompting further investigation into their diagnostic impact.

Key Companies

  • Koninklijke Philips N.V.
  • GE HealthCare
  • Hill-Rom Holdings, Inc.
  • Spacelabs Healthcare (OSI Systems, Inc.)
  • SCHILLER AG
  • Bittium
  • Lepu Medical Technology (Beijing) Co., Ltd.
  • BPL Medical Technologies
  • Biotricity
  • Nitto Denko Corporation

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The holter monitors market is witnessing strong momentum due to the growing global burden of heart-related disorders and the need for real-time cardiac monitoring. Continuous advancements in wearable and wireless monitoring technologies are enhancing diagnostic accuracy and patient comfort. Supportive healthcare policies, expanding geriatric populations, and increased awareness of preventive cardiac care further strengthen market potential. Moreover, ongoing research and product innovation by leading players are set to make Holter monitoring an indispensable tool in modern cardiovascular diagnostics.


Facial Massager Market Trends Shaping the Beauty Device Industry

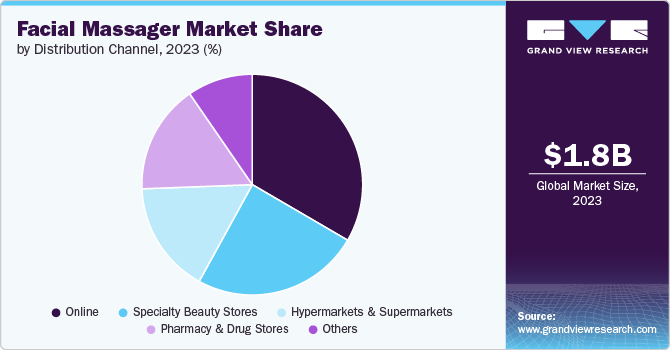
The global facial massager market was valued at USD 1.79 billion in 2023 and is projected to escalate to USD 3.55 billion by 2030, reflecting a Compound Annual Growth Rate (CAGR) of 10.7% over the forecast period from 2024 to 2030. This robust expansion is primarily fueled by a heightened consumer focus on anti-aging, comprehensive skincare, and facial well-being.

Consumers are increasingly appreciating the therapeutic benefits of these devices, such as improved blood circulation, the reduction of facial puffiness, and enhanced skin tone. This aligns perfectly with the rising market preference for non-invasive, convenience-driven, at-home beauty treatments. This behavioral shift is notably pronounced among younger demographics who are adopting proactive and preventative skincare regimes, thereby accelerating the market’s growth trajectory.

The persistent quest for vibrant, youthful skin is a key factor driving innovation within the facial massager sector. Manufacturers are focusing on products that significantly boost skin vitality and elasticity. Consequently, advanced technologies—including microcurrent, vibration, and heat therapy—are being integrated as standard features. These technological enhancements not only stimulate collagen synthesis and microcirculation but also offer professional-grade treatment results in a home setting. This evolution makes facial massagers highly appealing to a demographic of tech-savvy, beauty-conscious individuals who are prepared to invest in premium, multi-benefit devices, which, in turn, intensifies competition and market expansion.

Social media platforms and beauty influencers wield significant power in the facial massager market, successfully positioning these tools as indispensable elements of a modern skincare routine. By consistently sharing usage tutorials, personal product experiences, and visible results, influencers generate substantial consumer demand, especially among younger, appearance-focused audiences. Key platforms like YouTube, Instagram, and TikTok maximize product visibility, while influencer endorsements establish credibility, making facial massagers more sought-after. This trend encourages consumers to purchase and experiment with the devices, substantially increasing both sales and global brand awareness.

Key Market Trends & Insights

  • North America accounted for a market share of around 35% in 2023.
  • By type, the manual segment accounted for a share of around 65% in 2023.
  • By end-use, the women segment accounted for a market share of about 60% in 2023.
  • By application, the face lifting segment accounted for a market share of about 31% in 2023.
  • By distribution channel, specialty beauty stores segment accounted for a market share of around 25% in 2023.

Download a free sample PDF of the Facial Massager Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 1.79 Billion
  • 2030 Projected Market Size: USD 3.55 Billion
  • CAGR (2024-2030): 10.7%
  • North America: Largest market in 2023

Competitive Landscape

The market for facial massagers is exceptionally dynamic, featuring a mix of established international corporations and aggressive new entrants. The foremost competitors are differentiated by consistent product innovation, technological breakthroughs, and impactful marketing strategies designed to capture consumer attention. Market rivalry is driven by major companies offering sophisticated, high-tech devices incorporating features like microcurrent, heat, and vibration, competing with brands that prioritize cost-effectiveness and user simplicity. Factors such as design aesthetics, proven efficacy, and seamless integration into daily skincare rituals further define brand differentiation. Furthermore, companies are strategically leveraging digital channels and social media to boost visibility and connect with a broader consumer base, thereby escalating the competitive environment in this expanding sector.

Recent Developments

  • In July 2024, Foreo unveiled its newest microcurrent skin-firming device, the BEAR. This state-of-the-art facial massager is engineered to boost skin firmness and elasticity using advanced microcurrent technology. The BEAR integrates a patented Anti-Shock System to guarantee safe and effective use, offers adjustable intensity settings for personalized treatments, and includes a distinctive T-Sonic pulsation function aimed at improving overall skin texture and tone. This launch highlights Foreo's dedication to innovation in beauty technology, catering to the growing consumer demand for high-performance, accessible at-home skincare solutions.
  • In January 2024, NuFace launched its new Fitness for Your Face facial and a corresponding in-app treatment, designed to complement users' wellness goals for the year. This novel offering blends the company's acclaimed microcurrent technology with a customized app experience, allowing users to tailor their facial treatments and monitor their results. The device aims to enhance facial contouring, diminish signs of aging, and promote overall skin health via targeted microcurrent stimulation. This introduction underscores NuFace's strategy of merging leading-edge technology with user-centric features, meeting the accelerating consumer demand for effective and highly personalized at-home skincare solutions.

Key Companies

  • FEREO
  • NuFACE
  • ReFa
  • L'Oreal S.A. (Clarisonic)
  • SHANI DARDEN SKIN CARE
  • Jade Roller
  • KORA Organics
  • Herbivore Botanicals
  • Yeamon Beauty
  • YA-MAN Ltd.

Explore Horizon Databook – the world's most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global facial massager market is positioned for sustained, strong growth, projected to achieve a market size of USD 3.55 billion by 2030 with a 10.7% CAGR. This trajectory is fundamentally driven by the confluence of increasing consumer focus on proactive anti-aging and skincare wellness, and a pronounced shift toward convenient, non-invasive at-home beauty solutions. Key drivers include significant technological innovation, particularly in microcurrent and heat therapy devices that deliver professional-level results, and the amplifying effect of social media and beauty influencers in driving awareness and sales. While the manual segment holds the largest share, the competition remains fierce, characterized by strategic product launches from key players like Foreo and NuFace. North America, the leading regional market, demonstrates the high consumer adoption of these tools, underscoring the facial massager's evolution from a niche item to a staple device in the modern, personalized skincare routine.

Exotic Pets Market: Growing Interest in Exotic Aquatic Pets Boosts Demand

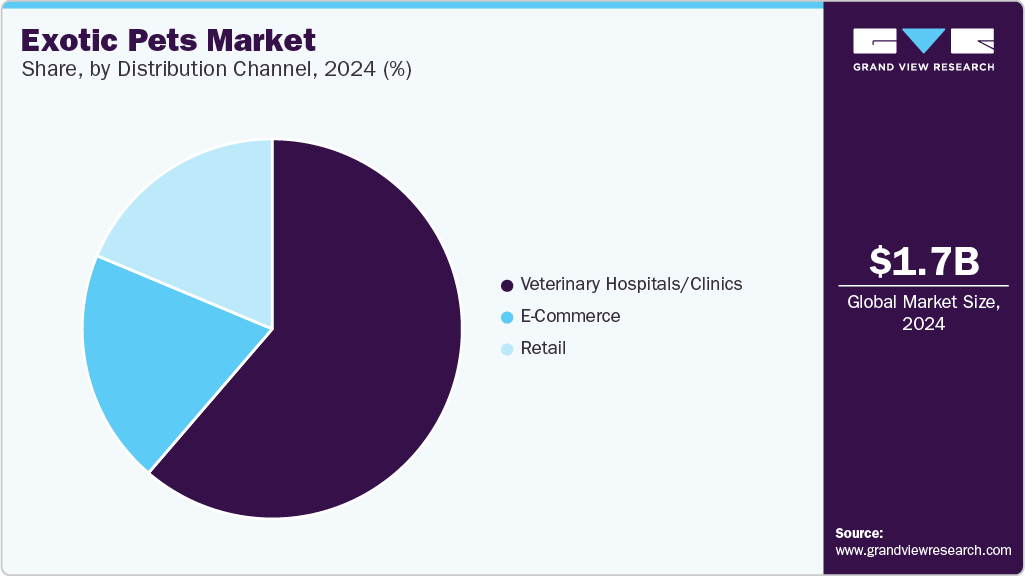
The global exotic pets market size was estimated at USD 1.65 billion in 2024 and is expected to reach USD 2.49 billion by 2030, registering a CAGR of 7.3% from 2025 to 2030. The market is primarily driven by increased awareness of species-specific health issues and the growing demand for specialized care, including veterinary services, diagnostics, and insurance.

Additionally, the rise of personalized wellness products and responsible pet ownership is fueling market growth. For instance, amyloidosis, a common condition in birds associated with chronic inflammation, stress, and vaccination, can lead to amyloid deposits in organs such as the spleen, liver, and respiratory system. In January 2025, a report by the World Organization for Animal Health (WOAH) highlighted cases of West Nile virus in wild birds from Estonia and Germany, further emphasizing the need for specialized care for exotic species.

Product expansion is another key growth driver, addressing the evolving needs of non-traditional companion animals. As manufacturers and retailers expand offerings—including specialized food, habitat enrichment tools, grooming products, supplements, and medical kits—they enhance the pet ownership experience. The increased availability of diverse, high-quality products, both online and offline, lowers entry barriers for new pet owners, supports long-term care, and drives market demand. For example, Mazuri, a leading exotic animal nutrition company based in Minnesota, offers a portfolio of over 500 products. In 2023, the company reported a 5% increase in net sales through pet specialty retailers and a 19% rise via online platforms. Mazuri also partnered with Chewy in 2019, providing more than 50 food options for exotic animals, and plans to expand its reach further across Canada, Latin America, Asia-Pacific, the Middle East, and Europe.

Key Market Trends & Insights

  • North America dominated the market with the largest revenue share of 50.27% in 2024.
  • By animal type, the small mammals segment led the market with a share of 31.4% in 2024.
  • By route of administration, the oral segment held the largest share of 45.9% in 2024.
  • By product, the pharmaceuticals segment accounted for the largest share of 69.6% in 2024.
  • By distribution channel, the veterinary hospitals/clinics segment dominated with a share of 61.3% in 2024.

Download a free sample PDF of the Exotic Pets Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 1.65 Billion
  • 2030 Projected Market Size: USD 2.49 Billion
  • CAGR (2025–2030): 7.3%
  • North America: Largest market in 2024
  • Asia Pacific: Fastest growing market

Competitive Landscape

The global exotic pet market is driven by growing consumer interest in non-traditional companion animals, urbanization, and increasing demand for specialized pet care products. Popular exotic pets include reptiles, amphibians, ornamental birds, small mammals, and unique aquatic species, with owners seeking distinctiveness and personality.

Major market players include AdvaCare Pharma, VETARK (Candioli Srl), Vetafarm, Mazuri, Versele Laga, CROCdoc (a sister company of The Birdcare Company), Zoetis Inc., Merck & Co., Inc., Vetnil, and Pet King Brands. These companies are innovating in areas such as nutrition, supplements, disease prevention, and habitat enrichment. The proliferation of online pet retail platforms and educational content has enhanced accessibility and appeal of exotic pet ownership globally. As awareness of ethical sourcing, proper veterinary care, and high-quality species-specific products rises, market demand is expected to increase.

Market leaders are expanding globally by tailoring offerings to regional needs and enhancing distribution networks. Companies like Mazuri, Vetafarm, and Versele Laga are recognized for their science-backed nutrition formulations for birds, reptiles, and rodents. Zoetis Inc. and Merck & Co., Inc. contribute pharmaceutical expertise, providing products for parasitic infections and immune deficiencies. AdvaCare Pharma and VETARK focus on affordable, specialized health products in emerging markets, while CROCdoc and Pet King Brands focus on holistic care and natural formulations. With rising awareness of animal welfare and increased veterinary specialization, the exotic pet market is poised for continued growth through innovation, education, and evolving consumer preferences.

Key Companies

  • AdvaCare Pharma
  • VETARK (Candioli Srl)
  • Vetafarm
  • Mazuri
  • Versele Laga
  • CROCdoc (a sister company of The Birdcare Company)
  • Zoetis Inc.
  • Merck & Co., Inc.
  • Vetnil
  • Pet King Brands

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The global exotic pet market is projected to witness steady growth, driven by increased consumer awareness of species-specific health issues, specialized care demand, and the expansion of high-quality products and veterinary services. As the adoption of non-traditional companion animals rises worldwide, the market is set for continued expansion through 2030.

Chicory Market: Growing Demand for Natural Ingredients Fuels Expansion

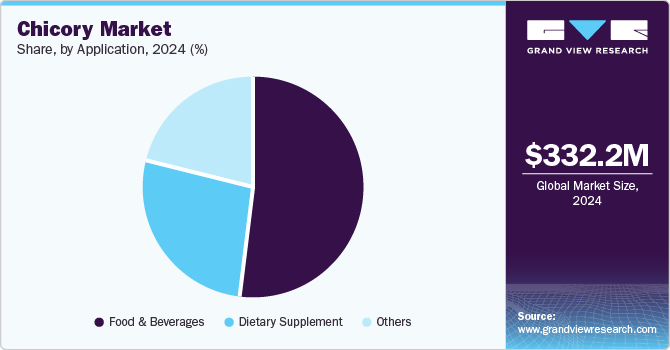
The global chicory market size was valued at USD 332.2 million in 2024 and is estimated to reach USD 523.3 million by 2030, registering a CAGR of 7.9% from 2025 to 2030. The market growth is primarily driven by increasing awareness of chicory’s health benefits.

Chicory is used to address constipation, high blood pressure, loss of appetite, gallbladder disorders, and cancer, among other health conditions. The paste of chicory leaves can also be applied topically for swelling and inflammation. Beyond its medicinal uses, application in the food and beverage industry is anticipated to further drive product demand.

Chicory is increasingly used as a coffee substitute, appealing to consumers seeking caffeine-free alternatives. The rising popularity of plant-based and functional foods, which often incorporate chicory as an ingredient, supports market expansion. Additionally, technological advancements in extracting and processing chicory extracts have improved product quality and availability, further stimulating consumer demand.

Rising demand for gluten-free appetizers is expected to boost chicory consumption in Europe. The introduction of innovative chicory recipes, along with its use in salads, appetizers, and as a substitute for crackers and gluten-containing products, is projected to further increase consumption. Market players are expanding operations and storage capacity to meet rising demand, while retailers are developing more pre-packaged options to capitalize on growth opportunities.

Key Market Trends & Insights

  • Asia Pacific dominated the global chicory market with the largest revenue share of 31.7% in 2024.
  • By product, the chicory root segment led the market with the largest revenue share of 74.2% in 2024.
  • By application, the food and beverages segment held the largest revenue share in 2024.

Download a free sample PDF of the Chicory Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 332.2 Million
  • 2030 Projected Market Size: USD 523.3 Million
  • CAGR (2025–2030): 7.9%
  • Asia Pacific: Largest market in 2024
  • North America: Fastest growing market

Competitive Landscape

Key companies in the chicory market include Cargill, Incorporated, Delecto Foods Pvt Ltd., Starwest Botanicals, Leroux Flavored Brandies, Pioneer Chicory, and Farmvilla Food Industries Private Limited. Companies focus on organic and non-GMO products to meet growing consumer demand. Additionally, several players adopt strategies such as new product launches, mergers, and acquisitions to maintain competitiveness.

  • Cargill, Incorporated is a major market player offering a wide range of chicory-based products, including Chicory Root Fiber, Chicory Extracts, Roasted Chicory, and Inulin. The company emphasizes high-quality, health-promoting ingredients.
  • Delecto Foods Pvt Ltd. is another prominent player, known for products such as Chicory Root, Roasted Chicory Cubes, Liquid Chicory, and Spray Dried Instant Chicory Powder.

Recent Developments

  • May 2024: PJ’s Coffee reintroduced its popular Southern Wedding Cake flavor and launched a chicory-infused beverage. Products include the Southern Wedding Cake Iced Latte (espresso with almond and vanilla syrups), the Southern Wedding Cake Velvet Ice (cold brew with whipped cream), and the Southern Charm Chicory Cold Brew featuring chicory and black sugar cold foam, celebrating the brand’s New Orleans heritage.

Key Companies

  • Cargill, Incorporated
  • Delecto Foods Pvt Ltd.
  • Starwest Botanicals
  • Leroux Flavored Brandies
  • Pioneer Chicory
  • Natures Gold
  • Organic Herb Trading
  • Jamnagar Chicory Industries
  • STOKROS Company Ltd
  • Farmvilla Food Industries Private Limited

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The chicory market is expected to witness steady growth, driven by rising health awareness, increased application in food and beverages, and technological advancements in product extraction and processing. As consumer demand for natural, functional, and plant-based products continues to rise, the market is poised for sustained expansion through 2030.

Canes and Crutches Market: Rising Elderly Population Boosts Demand

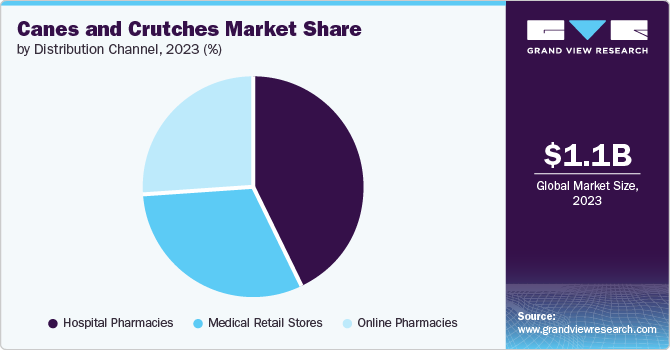
The global canes and crutches market size was estimated at USD 1.07 billion in 2023 and is expected to reach USD 1.49 billion by 2030, growing at a CAGR of 4.9% from 2024 to 2030. The rising prevalence of musculoskeletal conditions is a major factor driving market growth.

According to a WHO article published in November 2022, approximately 1.71 billion people globally live with musculoskeletal conditions, including fractures, osteoarthritis, and rheumatoid arthritis, which collectively rank among the leading causes of disability worldwide. Low back pain is the single most significant contributor to disability in 160 countries, with 570 million established cases globally. Other contributors include fractures affecting 440 million people, osteoarthritis affecting 528 million, amputations at 180 million, rheumatoid arthritis with 18 million cases, and gout affecting 54 million people.

Advancements in materials and design are further propelling market growth. According to an NCBI article published in February 2024, recent innovations in canes for individuals with visual impairments include the integration of sonars and sensors to detect obstacles. These devices are designed to be rechargeable, universally mountable, and long-lasting on ordinary white canes. One notable development, the Mobility Assistant for Visually Impaired (MAVI) project, aims to upgrade canes to detect and describe obstacles, including pedestrians, signboards, animals, and text through optical character recognition (OCR).

The design of crutches has evolved significantly, moving from heavy wooden models to lighter, ergonomic versions made from aluminum, titanium, and carbon fiber. Modern crutches feature contoured arm pads, improved tips, and enhanced ergonomics, improving comfort and mobility. Companies like Ergoactive offer crutches with enhanced range of motion and rubber tips for shock absorption, reducing secondary injuries associated with traditional underarm crutches while increasing weight-bearing capacity.

Key Market Trends & Insights

  • North America dominated the global industry with a share of around 36.0% in 2023.
  • The U.S. canes and crutches market accounted for the largest share of 82.4% in 2023.
  • By product, the canes segment held the largest share of over 52.07% in 2023.
  • By distribution channel, the hospital pharmacies segment accounted for the largest share of 43.19% in 2023.

Download a free sample PDF of the Canes And Crutches Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 1.07 Billion
  • 2030 Projected Market Size: USD 1.49 Billion
  • CAGR (2024–2030): 4.9%
  • North America: Largest market in 2023
  • Asia Pacific: Fastest growing market

Competitive Landscape

Key players in the canes and crutches market include Drive DeVilbiss Healthcare, Ossenberg GmbH, and Ergoactives. These companies adopt strategies such as market analysis, anticipating trends, leveraging emerging technologies, and understanding consumer preferences to strengthen market presence and remain competitive.

Recent Developments

  • May 2024: The British Red Cross in Taunton launched a mobility aid service, providing a range of aids to help individuals with mobility challenges improve daily life.
  • January 2024: The Royal Shrewsbury Hospital (RSH) introduced a walking aid return and reuse scheme, enabling patients to return aids for recycling and sustainability purposes.
  • August 2023: Alumni from IIT Delhi developed the world’s first automotive crutches that can stand independently, designed for older adults and people with locomotive disabilities, suitable for various terrains including trekking.
  • August 2023: Cool Crutches and Walking Sticks launched the first walking aid recycling scheme in the UK, promoting reuse and sustainability in mobility support.

Key Companies

  • Drive DeVilbiss Healthcare
  • Ossenberg GmbH
  • Ergoactives
  • NOVA Medical Products
  • GF Health Products Inc
  • Sunrise Medical Limited
  • Besco Medical Co., Ltd
  • Invacare Corporation
  • Medline Industries, Inc
  • Cardinal Health, Inc.

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The canes and crutches market is expected to witness steady growth driven by rising musculoskeletal conditions, innovative product designs, and advancements in materials. As demand for ergonomic, lightweight, and technologically enhanced mobility aids increases, the market is poised for consistent expansion through 2030.

Anti-Pollution Nasal Spray Market: Key Players Lead with Innovation

The global anti-pollution nasal spray market size was valued at USD 7.94 billion in 2024 and is anticipated to reach USD 10.91 billion by 2030, growing at a CAGR of 5.51% from 2025 to 2030. The market growth is largely driven by rising global air pollution, fueled by industrialization, urbanization, and increasing vehicular emissions.

Exposure to pollutants such as particulate matter (PM2.5 and PM10), nitrogen dioxide, sulfur dioxide, and ozone significantly irritates and inflames nasal passages. This contributes to higher incidences of respiratory conditions like allergic rhinitis, sinusitis, and asthma, prompting individuals to adopt preventive and protective solutions.

According to the European Environment Agency, air pollutant levels in 2021 exceeded the levels recommended by the World Health Organization (WHO). Meeting these guidelines could have prevented numerous deaths across EU Member States (EU-27), including 253,000 deaths linked to fine particulate matter (PM2.5), 52,000 deaths due to nitrogen dioxide (NO2), and 22,000 deaths related to short-term ozone (O3) exposure.

Similarly, the report Integrated Assessment of Air Pollution and Climate Change for Sustainable Development in Africa, published by the Climate and Clean Air Coalition (CCAC), the African Union Commission, and the United Nations Environment Programme (UNEP) in November, highlights that implementing recommended actions could prevent 200,000 premature deaths annually by 2030 and 880,000 deaths per year by 2063. Consequently, the rising pollution levels are expected to drive market growth during the forecast period.

Key Market Trends & Insights

  • North America dominated the global anti-pollution nasal spray market with a share of 38.54% in 2024.
  • The U.S. held a market share of 74.85% within the North American region in 2024.
  • By product, the pollution defense products segment accounted for the largest revenue share of 28.54% in 2024.
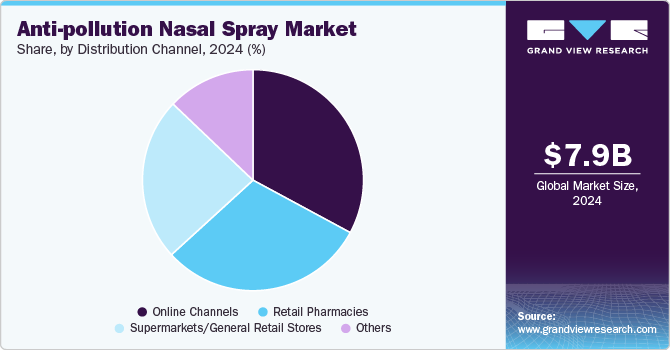
  • By distribution channel, the retail pharmacies segment held the largest revenue share of 32.87% in 2024.

Download a free sample PDF of the Anti-pollution Nasal Spray Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 7.94 Billion
  • 2030 Projected Market Size: USD 10.91 Billion
  • CAGR (2025–2030): 5.51%
  • North America: Largest market in 2024

Competitive Landscape

Key players in the anti-pollution nasal spray market include Haleon plc, GSK plc, Merck & Co., Inc., and Himalaya Wellness Company. These companies are investing in research and development, manufacturing capacity expansion, and global distribution networks to meet rising demand.

Product innovation and regulatory approvals are critical strategies for established companies to maintain a competitive edge. Leading players focus on advanced formulations and therapeutic product expansion, while emerging companies explore niche areas, such as novel delivery mechanisms to address unmet medical needs.

Recent Developments

  • January 2025: NeilMed Pharmaceuticals launched a program to donate Sinus Rinse products to firefighters in Los Angeles battling wildfires. The initiative provides relief from nasal discomfort caused by dust, smoke, and airborne pollutants.
  • March 2024: Aurobindo Pharma Limited received final FDA approval to manufacture and market Mometasone Furoate Monohydrate Nasal Spray (50 mcg), bioequivalent to Nasonex Nasal Spray.
  • October 2024: Haleon, in collaboration with Aptar Pharma, introduced Otrivin Nasal Mist, a next-generation nasal spray designed for enhanced comfort and ease of use. Utilizing advanced microdroplet technology, it provides full yet gentle mist coverage for inflamed nasal areas without dripping or discomfort.

Key Companies

  • Haleon plc
  • GSK plc
  • Merck & Co., Inc.
  • Himalaya Wellness Company
  • Jadran-galenski laboratorij d.d. JGL d.d.
  • NeilMed Pharmaceuticals, Inc.
  • Aurena Laboratories AB
  • Church & Dwight Co., Inc.
  • Xlear, Inc.
  • Sandoz International GmbH

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The anti-pollution nasal spray market is poised for steady growth, driven by rising air pollution, increasing awareness of respiratory health, and innovative product launches. As demand for preventive nasal care solutions continues to rise globally, the market is expected to expand consistently through 2030.


AI Voice Agents in Healthcare Market: Key Players Redefine Care

The global AI voice agents in healthcare market size was estimated at USD 468.00 million in 2024 and is projected to reach USD 3,175.9 million by 2030, growing at a CAGR of 37.79% from 2025 to 2030. The market growth is primarily driven by the increasing automation of clinical documentation and workflows, a rising focus on patient engagement, chronic disease management, call center optimization, and frontline triage automation.

Moreover, the ability of AI voice agents to seamlessly integrate with existing electronic health record (EHR) systems is further fueling market expansion. A key growth driver is the capability of AI voice agents to streamline clinical documentation. Built on advanced natural language processing (NLP) and voice recognition technologies, these systems can transcribe doctor-patient interactions in real time, automate SOAP note generation, and update electronic medical records (EMRs) with minimal human intervention. Increasing integration into EHR systems allows physicians to document patient encounters via voice commands, reducing manual data entry and enabling them to focus more on patient care.

This shift from manual to automated documentation is accelerating adoption, particularly among hospitals and private practices in developed markets, where compliance with documentation standards is stringent. For instance, in February 2025, VoiceCare AI launched a pilot program with the Mayo Clinic to automate back-office operations using AI voice agent technology.

Furthermore, AI voice agents are advancing disease diagnosis through the analysis of vocal biomarkers to detect various health conditions. This non-invasive diagnostic approach leverages subtle variations in speech patterns, pitch, and tone to identify early indicators of disease. Specialized voice agents designed for conditions such as diabetes, hypertension, and mental health disorders provide disease-specific interactions that support behavioral change and treatment adherence, enhancing overall patient outcomes.

Key Market Trends & Insights

  • North America dominated the AI voice agents in healthcare market with the largest revenue share of 54.17% in 2024.
  • Based on application, the clinical documentation segment led the market with a revenue share of 17.54% in 2024.
  • Based on deployment mode, the cloud-based segment held the largest revenue share of 85% in 2024.
  • Based on technology, the NLP-powered conversational agents segment accounted for the largest revenue share of 32% in 2024.
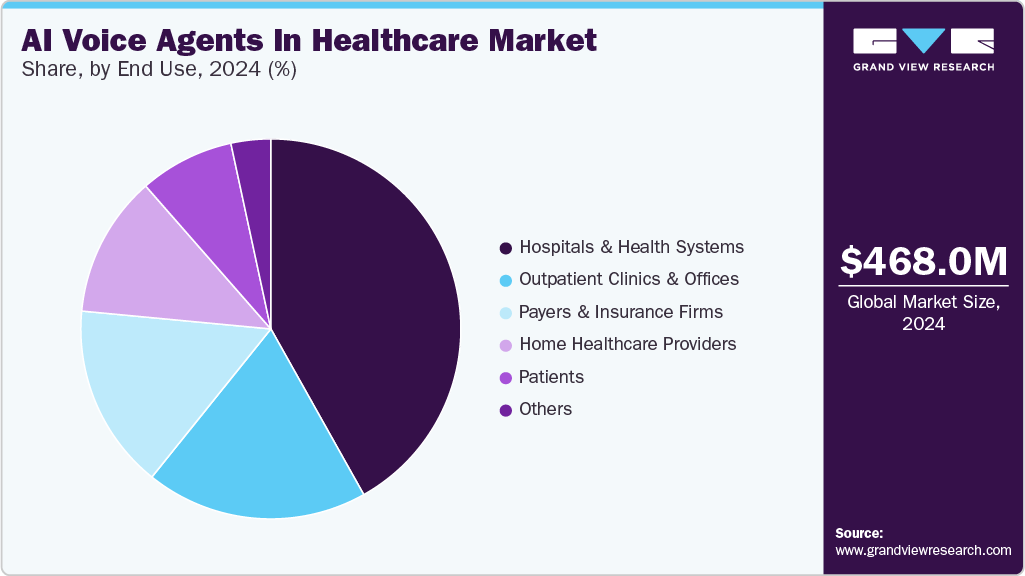
  • Based on end use, the hospitals & health systems segment dominated with a revenue share of 41.87% in 2024.

Download a free sample PDF of the AI Voice Agents In Healthcare Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 468.00 Million
  • 2030 Projected Market Size: USD 3,175.9 Million
  • CAGR (2025–2030): 37.79%
  • North America: Largest market in 2024

Competitive Landscape

Leading players in the AI voice agents in healthcare industry are actively adopting strategies such as new product launches, strategic partnerships, and acquisitions to strengthen their market positions and expand product reach. These initiatives are aimed at enhancing technological capabilities, broadening deployment options, and addressing growing demand for AI-driven healthcare automation.

Recent Developments

  • April 2025: Infinitus launched voice AI agents for healthcare, featuring a proprietary architecture designed to eliminate hallucinations. The enterprise-scale platform aims to automate calls, reduce administrative burdens, and improve access to healthcare services, while ensuring patient and provider safety.
  • April 2025: Cedar introduced Kora, an AI voice agent created to automate patient billing inquiries. Offering 24/7 support and personalized assistance, Kora helps reduce operational costs and call handling times by resolving routine issues and escalating complex cases to human agents.
  • January 2025: Eleos, a behavioral health company, raised USD 60 million in Series C funding to enhance its AI voice agents. These tools operate in the background during mental health sessions, aiming to improve care delivery and therapeutic outcomes.
  • January 2025: SuperDial acquired MajorBoost, a conversational AI firm specializing in automating calls to health insurers. The acquisition strengthens SuperDial’s voice AI solutions for U.S. healthcare providers, helping organizations achieve greater operational efficiency.

Key Companies

  • Zocdoc
  • eHealth, Inc.
  • Assort Health
  • RevSpring
  • Innovacer
  • Parakeet Health, Inc.
  • Cedar Cares, Inc.
  • Infinitus Systems
  • VOCADS
  • In Touch Now

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The AI voice agents in healthcare market is witnessing rapid expansion, driven by automation in clinical workflows, integration with EHR systems, and advances in NLP technologies. As healthcare organizations increasingly adopt voice-enabled AI tools to improve efficiency, patient experience, and diagnostic accuracy, the market is poised for sustained growth through 2030.

AI Anime Generator Market: Key Collaborations Drive Growth

The global AI anime generator market size was estimated at USD 91.38 billion in 2024 and is expected to reach USD 384.40 billion by 2030, growing at a CAGR of 27.7% from 2025 to 2030. The market growth is primarily driven by advancements in AI models that enable the creation of high-quality, emotionally expressive, and consistent anime-style artwork with minimal technical expertise.

Additionally, the integration of AI anime generators into creative workflows, the rise of user-friendly platforms, and the democratization of anime art production are key trends propelling the expansion of the AI anime generator industry.

A growing focus on addressing copyright infringement, intellectual property rights, and ethical concerns associated with AI-generated content is another major trend shaping the market. The rapid rise of AI art tools has intensified debates around the ownership of AI-generated works and their impact on human artists, encouraging regulators and industry stakeholders to develop transparent and accountable frameworks. These evolving regulatory and ethical guidelines aim to balance innovation with respect for original creators and societal values, influencing how AI anime generation technologies are developed, deployed, and commercialized.

Furthermore, the integration of AI anime generators into broader creative ecosystems is gaining momentum, with tools offering cross-platform compatibility and real-time animation capabilities. Breakthroughs in AI-driven lip sync, procedural animation, and style transfer empower creators to produce dynamic, interactive anime content efficiently. This trend is particularly strong in the gaming and entertainment sectors, where AI-generated characters and scenes can be animated in real time, enhancing user engagement and expanding the role of AI in multimedia storytelling.

Moreover, companies operating in the AI anime generator market are focusing on leveraging advanced AI technologies and customizing platforms to cater to diverse user needs. Many firms emphasize building robust, scalable AI models trained on high-quality anime datasets to deliver unique, high-fidelity outputs. The adoption of subscription-based pricing models—such as Animon.ai’s unlimited content creation approach—is gaining traction, reducing financial barriers and fostering global creator communities. This strategy appeals to both amateurs and professional directors, further fueling market expansion in the coming years.

Key Market Trends & Insights

  • Asia Pacific accounted for the highest revenue share of over 42.6% in 2024.
  • By platform, the web-based segment dominated the market with a revenue share of over 67% in 2024.
  • By technology, the image-to-image transformation models segment held the largest market share in 2024.
  • By end-use, the individual creators segment accounted for the largest market share in 2024.
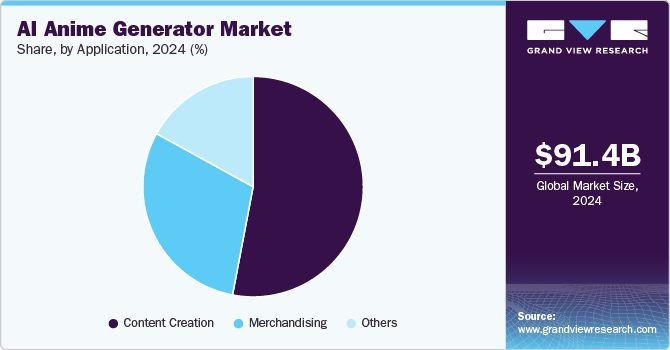
  • By application, the content creation segment held the largest market share in 2024.

Download a free sample PDF of the AI Anime Generator Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2024 Market Size: USD 91.38 Billion
  • 2030 Projected Market Size: USD 384.40 Billion
  • CAGR (2025–2030): 27.7%
  • Asia Pacific: Largest market in 2024

Competitive Landscape

The market features a dynamic competitive landscape, with key players emphasizing innovation, AI integration, and platform scalability to strengthen their presence.

Some of the prominent players in the market include Midjourney and Reallusion, Inc., among others.

  • Midjourney is an AI-powered tool renowned for generating high-quality, stylized images from text prompts. Leveraging a proprietary AI model, it transforms creative inputs into visually compelling anime, fantasy, and artistic styles. Its dedicated “Niji” model specializes in anime-inspired imagery. Since its launch, Midjourney has built a large, active user base of artists and content creators who rely on its tools for both personal and commercial projects.
  • Reallusion, Inc. is a leading name in the animation and 3D character creation industry, offering powerful tools for both amateurs and professionals. Its flagship products—iClone and Character Creator—enable users to design, animate, and render 3D characters with precision. The company increasingly integrates AI-driven features to enhance automation, creativity, and efficiency, empowering users with streamlined workflows for character design and animation production.

Emerging players such as Runway AI and Waifu Labs are also gaining traction in the market.

  • Runway AI offers a creative toolkit that allows users to generate video and image content using advanced AI models. Its platform supports text-to-image, video generation, and real-time editing capabilities. Runway AI enables seamless creation of anime-style animations and videos, catering to digital artists, filmmakers, and content creators. Its collaboration-friendly and integration-ready platform makes it a versatile solution for generative media production.
  • Waifu Labs is an AI-powered platform designed for custom anime character creation. Using machine learning, it generates unique anime characters based on user-defined preferences, including hairstyle, clothing, and facial features. Its intuitive interface allows for easy creation of anime characters in just a few steps. Waifu Labs is popular among anime enthusiasts and digital artists seeking personalized characters for stories, games, or art projects.

Key Companies

  • Midjourney
  • Runway AI
  • Reallusion Inc.
  • Krikey Inc.
  • Artbreeder
  • DeepArt
  • PaintsChainer (Preferred Networks, Inc.)
  • Toonify
  • Waifu Labs
  • Fotor AI (Everimaging Science & Technology Co., Ltd)

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The AI anime generator market is experiencing rapid growth, fueled by technological innovation, ethical framework development, and increasing integration into creative ecosystems. As tools become more accessible and powerful, they are transforming how creators produce, animate, and distribute anime content—reshaping the future of digital art and storytelling.

3D Printed Drones Market: Strategic Collaborations Driving Innovation

The global 3D printed drones market size was estimated at USD 614.3 million in 2023 and is projected to reach USD 2,013.5 million by 2030, growing at a CAGR of 18.9% from 2024 to 2030. The market growth is primarily driven by the advancements in additive manufacturing technologies, which are enabling faster and more cost-efficient drone production.

The increasing adoption of rapid prototyping and production of drones across sectors such as agriculture, logistics, surveillance, and environmental monitoring is expected to fuel market expansion in the coming years.

Technological innovations in additive manufacturing play a significant role in driving growth. The capability to produce complex, lightweight structures at lower costs improves production efficiency and reduces inventory-related expenses. This design flexibility is particularly valuable in military applications, where quick design iterations are essential to meet evolving operational requirements. Additionally, the integration of advanced materials in 3D printing enhances the potential for developing high-performance drone components, thereby creating lucrative opportunities for market expansion.

Moreover, several countries are investing in research and development (R&D) to advance drone technology through additive manufacturing processes. These investments promote innovation and encourage collaboration between public institutions and private enterprises, resulting in improved drone design and manufacturing capabilities. This trend is fueled by the growing need for rapid production and the ability to adapt designs quickly in response to shifting market demands.

The versatility of 3D-printed drones is also driving demand across multiple applications, including surveillance, agriculture, delivery services, and recreational uses. As organizations increasingly recognize the benefits of drones for improving operational efficiency and data collection, the market for 3D-printed drones is anticipated to witness substantial growth. This expansion is further supported by continuous technological advancements that enhance drone functionality, making them more appealing for both commercial and professional applications.

Key Market Trends & Insights

  • North America accounted for the highest revenue share of over 36% in 2023.
  • By component, the airframe segment held the largest market share of over 36% in 2023.
  • By type, the multi-rotor segment accounted for the largest market share in 2023.
  • By technology, the fused deposition modeling (FDM) segment recorded the largest share in 2023.
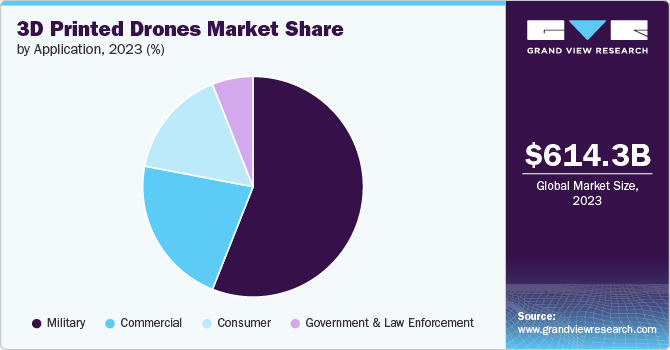
  • By application, the military segment accounted for the largest market share in 2023.

Download a free sample PDF of the 3D Printed Drones Market Intelligence Study, published by Grand View Research.

Market Performance

  • 2023 Market Size: USD 614.3 Million
  • 2030 Projected Market Size: USD 2,013.5 Million
  • CAGR (2024–2030): 18.9%
  • North America: Largest market in 2023

Competitive Landscape

The market is moderately consolidated, with leading players focusing on technological innovation, integration of 3D printing in production, and strategic partnerships to strengthen their market positions.

Some of the key players operating in the market include The Boeing Company and AeroVironment, Inc., among others.

  • The Boeing Company is a major aerospace and defense manufacturer that has made notable advancements in the 3D printed drone market. The company places strong emphasis on integrating 3D printing technologies into its manufacturing operations, enabling the development of lightweight, high-performance drones with enhanced operational capabilities.
  • AeroVironment, Inc. specializes in small Unmanned Aircraft Systems (UAS) and has been a pioneer in utilizing 3D printing technology in drone manufacturing. Its portfolio features various tactical and surveillance drones that benefit from lightweight, durable, and customizable parts produced via additive manufacturing. The company’s focus on rapid prototyping and iterative design allows it to meet evolving requirements across defense and commercial sectors.

Other emerging participants include Lockheed Martin Corporation and Firestorm Labs, Inc.

  • Lockheed Martin Corporation, a leading aerospace, defense, and security firm, has increasingly adopted 3D printing in its drone production processes. The company leverages this technology to develop advanced drone components and prototypes, improving customization and performance across military and commercial applications.
  • Firestorm Labs, Inc. focuses on merging cutting-edge 3D printing technologies with drone design and manufacturing. The company excels in producing customized, high-performance drones through rapid prototyping and the creation of intricate components using advanced additive manufacturing methods.

Key Companies

  • The Boeing Company
  • AeroVironment, Inc.
  • BAE Systems plc
  • Draganfly Innovations, Inc.
  • Thales Group
  • Parrot Drones SAS
  • General Atomics
  • Skydio, Inc.
  • Airbus SE
  • Flyability SA

Explore Horizon Databook – the world’s most comprehensive market intelligence platform by Grand View Research.

Conclusion

The 3D printed drones market is witnessing strong growth, propelled by rapid technological advancements, increasing R&D investments, and the growing adoption of additive manufacturing across industries. As demand for lightweight, cost-efficient, and customizable drones continues to rise, the market is expected to expand significantly over the forecast period.

Oxygen Concentrator Market Outlook: Growth, Regions, Leaders, and Segment Showdowns

Oxygen therapy is moving out of hospitals and into living rooms. As chronic respiratory conditions become more common and populations age, o...