The Demand for Wound Irrigation Systems Market is on the Rise Owing To Increasing Prevalence of Chronic Diseases

Wound Irrigation Systems Industry Overview

The global wound irrigation system market size is expected to reach USD 380.03 million by 2028, according to a new report by Grand View Research, Inc. It is expected to expand at a CAGR of 3.8% from 2021 to 2028. The rising prevalence of chronic wounds, increasing number of surgical procedures, technological advancements, favorable initiatives taken by the private and public sectors, and the increasing cases of burns across the globe are the key factors driving the market.
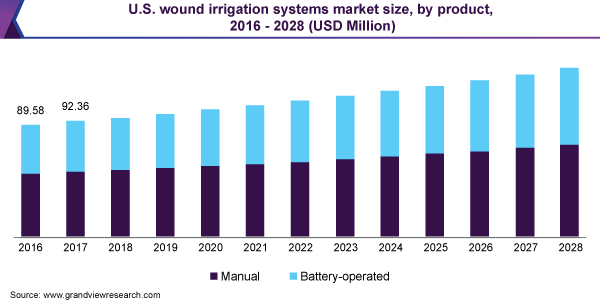
U.S. wound irrigation systems market size, by product, 2016 - 2028 (USD Million)

A wound irrigation system allows rapid healing of deep wounds and surgical site infections. It also allows improved wound cleansing that prevents further complications. The increasing prevalence of chronic wounds and the rising number of surgical procedures are the key factors driving the market. For instance, as per a report published by ScienceDirect in 2018, the surgical infection has the highest prevalence rate of around 4.0%, followed by diabetic foot ulcers of around 3.4%. In addition, the rising number of wound care centers across the globe is expected to surge the demand for wound irrigation systems.

Wound Irrigation Systems Market Segmentation

Grand View Research has segmented the global wound irrigation system market on the basis of the product, application, and region:

Based on the Product Insights, the market is segmented into Manual and Battery-operated

  • The manual wound irrigation system segment accounted for the largest revenue share of 55.45% in 2020.
  • The battery-operated wound irrigation system is anticipated to witness the fastest growth over the forecast period.

Based on the Application Insights, the market is segmented into Chronic Wounds, Burns, Surgical Wounds, and Traumatic Wounds

  • The chronic wounds segment accounted for the largest revenue share of 33.59% in 2020.
  • The chronic wounds segment is anticipated to witness the fastest growth over the forecast period. The increasing cases of chronic diseases, especially diabetes, across the globe are fueling the segment growth.

Wound Irrigation Systems Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key players are adopting various strategies such as mergers & acquisitions, product launches, and partnerships to strengthen their foothold in the market.

Some prominent players in the global Wound Irrigation Systems market include:

  • Zimmer Biomet
  • Stryker Corporation
  • Centurion Medical Products
  • BSN Medical
  • Cooper Surgical Inc.
  • R. Bard, Inc.
  • Bionix
  • Westmed, Inc.

Order a free sample PDF of the Wound Irrigation Systems Market Intelligence Study, published by Grand View Research.
Medical Affairs Outsourcing Market is expected to grow at a Compound Annual Growth Rate of 12.2% by 2028

Medical Affairs Outsourcing Industry Overview

The global medical affairs outsourcing market size is expected to reach USD 3.47 billion by 2028 registering a CAGR of 12.2%, according to a new report by Grand View Research, Inc. Transformation in medical education and the rising number of orphan therapies for the treatment of rare diseases are some of the key factors propelling the market growth. The pharmaceutical companies are looking for assistance to systematically position the therapeutic outcomes of these therapies in the market. According to a report published by IQVIA in 2020, the U.S. FDA has approved 80 orphan indications in 2017 and about 57 in early 2020.

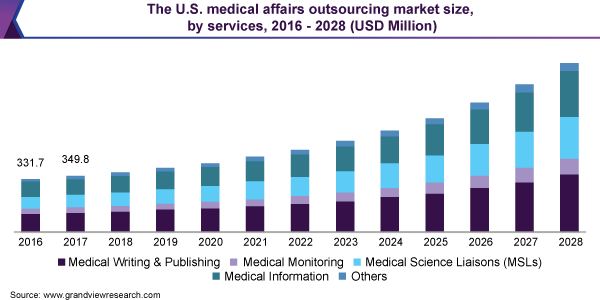
The U.S. medical affairs outsourcing market size, by services, 2016 - 2028 (USD Million)

The market is growing at a significant rate due to the surge in clinical trials. Changes in the reimbursement scenario and pricing pressure are expected to increase the adoption of cost-saving measures by the pharmaceutical and medical device companies. This is anticipated to promote off-shoring of medical affairs outsourcing in countries like India and China. Pharmaceutical companies are outsourcing medical affairs services to get high-quality documents, control the R&D cost, and reduce investment costs required to train the medical affairs team. Furthermore, the pharmaceutical and medical device companies are outsourcing their medical affairs services to diverge their business activities and manage product life cycles.

Medical Affairs Outsourcing Market Segmentation

Grand View Research has segmented the global medical affairs outsourcing market on the basis of services, industry, and region:

Based on the Services Insights, the market is segmented into Medical Writing & Publishing, Medical Monitoring, Medical Science Liaisons (MSLs), Medical Information, and Others

  • Medical writing & publishing was the largest service segment in 2020 and accounted for a revenue share of 35%.
  • The medical science liaisons (MSLs) segment is anticipated to register the fastest CAGR of 12.8% from 2021 to 2028.

Based on the Industry Insights, the market is segmented into Pharmaceutical, Biopharmaceutical, and Medical Devices

  • The pharmaceutical segment held the largest market share of over 52% in 2020 and is estimated to retain its leading position throughout the forecast years.
  • The pharmaceutical industry has been experiencing slow growth, delayed drug approvals, and insufficiency in the pharma production supply chain has anticipated a long-term impact on the pharmaceutical sector due to the global pandemic.
  • The biopharmaceutical segment is anticipated to register the fastest CAGR of over 13.5%. The biopharma industry is focusing more on the core activities related to drug development, which is expected to drive demand for medical affairs outsourcing services in the segment.

Medical Affairs Outsourcing Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Most of the companies are focusing on various growth strategies, such as partnerships, merger & acquisitions, and product portfolio expansion to retain their market position.

Some prominent players in the global Medical Affairs Outsourcing market include:

  • ICON plc
  • IQVIA Holdings, Inc.
  • The Medical Affairs Company
  • Syneos Health, Inc.
  • Pharmaceutical Product Development, LLC
  • Ashfield Healthcare Communications
  • Zeincro Group
  • Wuxi Clinical Development, Inc.
  • SGS S.A.
  • Indegene, Inc.

Order a free sample PDF of the Medical Affairs Outsourcing Market Intelligence Study, published by Grand View Research.
Increasing Awareness Initiatives Is Expected To Boost the Pelvic Floor Electric Stimulator Market Growth

Pelvic Floor Electric Stimulator Industry Overview

The global pelvic floor electric stimulator market size is anticipated to reach USD 427.15 million by 2028, according to a new report by Grand View Research, Inc. It is expected to expand at a CAGR of 11.5% from 2021 to 2028. Increasing prevalence of urinary incontinence, rising investment in research and development by key players, and growing awareness initiatives are some of the major factors anticipated to boost the market growth.

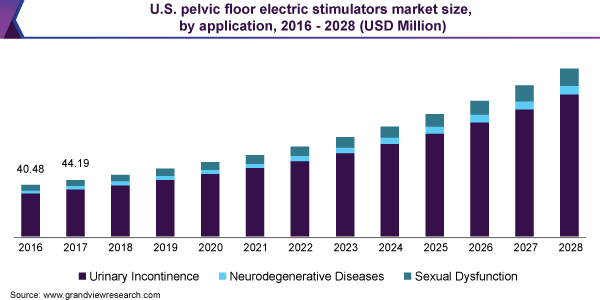
U.S. pelvic floor electric stimulators market size, by application, 2016 - 2028 (USD Million)

The increasing prevalence of chronic diseases and Urinary Incontinence (UI) are primary factors that are expected to drive the market growth. According to the NHS, around 61% of the male population is suffering from lower Urinary Tract Infections (UTI) and around 34% of women are living with some type of UI. This disorder costs around USD 301.40 million per year to the NHS, thereby, contributing to the market growth.

Factors such as the rising prevalence of neurodegenerative disorders, growing geriatric population, rising demand for home healthcare, and increasing use of medical sensors in various treatments are further expected to boost the market growth. The rapid rise in the geriatric population at higher risk of urinary incontinence is also one of the key factors responsible for the increasing demand for pelvic floor electric stimulators.

Pelvic Floor Electric Stimulator Market Segmentation

Grand View Research has segmented the global pelvic floor electric stimulator market based on application and region:

Based on the Application Insights, the market is segmented into Urinary Incontinence, Neurodegenerative Diseases, and Sexual Dysfunction

  • The UI segment led the market with a share of 84.87% in 2020 owing to the increasing prevalence of stress and urge incontinence, and product launches by key players.
  • However, the sexual dysfunction segment is expected to expand at the highest CAGR of 12.0% from 2021 to 2028.
  • Products introduced by the top players in the market, increasing awareness about the treatment of sexual dysfunction through pelvic floor electric stimulator, and rising prevalence of sexual dysfunction are a few factors that may drive market growth in the future.

Pelvic Floor Electric Stimulator Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Several market players engage in mergers and acquisitions to strengthen their market position. This strategy enables companies to increase their capabilities, expand their product portfolios, and improve competencies.

Some prominent players in the global Pelvic Floor Electric Stimulator market include:

  • Zynex Inc.
  • TensCare Ltd.
  • Verity Medical Ltd.
  • InControl Medical
  • The Prometheus Group
  • Laborie, Inc.
  • ActivLife Technologies
  • Athena Feminine Technologies
  • Atlantic Therapeutics
  • Renovia Inc.

Order a free sample PDF of the Pelvic Floor Electric Stimulator Market Intelligence Study, published by Grand View Research.
Key Factor Driving the Growth to Insulin Pump Market is Increasing Awareness about Diabetes Preventive Care

Insulin Pump Industry Overview

The global insulin pump market size is expected to reach USD 8.3 billion, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 8.7% from 2021 to 2028. The key factors driving the growth of the market are the technological advancements and the adoption of pumps over traditional methods. These pumps are very convenient for people who require daily multiple injections of insulin.

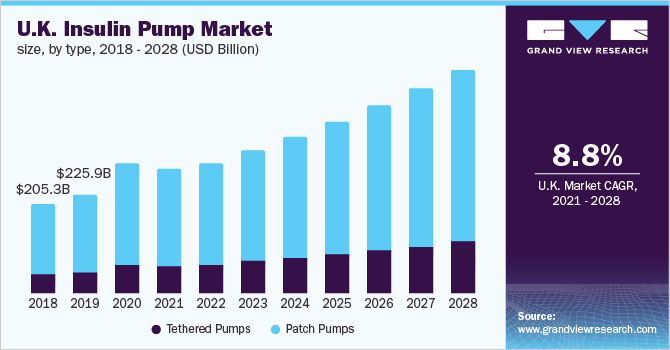
U.K. Insulin Pump Market size, by type

Insulin pump is a machine that enables insulin to be delivered either manually or automatically. These pumps can be programmed to deliver a specific set of doses and can also deliver a larger set of doses of glucose whenever required, such as before a meal. Patients can connect these devices to their smartphones to calibrate blood glucose readings. Technological advancement and new product launches across the globe are also fueling the market during the forecast period. For instance, Medtronic’s MiniMed 670G system is the world’s first hybrid closed loop system that acts as an artificial pancreas. The system provides automated insulin delivery as per the patient’s CGM readings.

Insulin Pump Market Segmentation

Grand View Research has segmented the global insulin pump market on the basis of type, product, accessories, end-use, and region:

Based on the Type Insights, the market is segmented into Patch Pumps and Tethered Pumps

  • The tethered pumps segment dominated the market and accounted for the largest revenue share of 78.5% in 2020. The segment is expected to witness a CAGR of 9.5% during the forecast period.
  • The patch pump segment is expected to witness a robust CAGR of around 10.0% during the forecast period.

Based on the Product Insights, the market is segmented into MiniMed (630G, 670G, and VEO), Accu-Chek (Combo, Insight, and Solo), Tandem (T: slim X2, G4, T: flex Delivery System), Omnipod, My Life Omnipod, and Others

  • Medtronic’s MiniMed insulin pumps segment dominated the market and captured the largest revenue share of around 50.0% in 2020 owing to the high adoption rate and advancement in technology.
  • The tandem pump segment is expected to exhibit the highest CAGR of 11.2% during the forecast period.

Based on the Accessories Insights, the market is segmented into Insulin reservoir or cartridges, Insulin set insertion devices, and Battery

  • The insulin set insertion devices segment dominated the market and accounted for the largest revenue share of 41.3% in 2020.
  • The insulin reservoir or cartridges segment is expected to witness a substantial growth rate of CAGR of 9.01% during the forecast period.

Based on the End-use Insights, the market is segmented into Hospitals & Clinics, Homecare, and Laboratories

  • The hospitals and clinics segment dominated the market and accounted for the largest revenue share of 44.8% in 2020 and is expected to maintain its dominance over the forecast period.
  • The homecare segment is expected to witness the fastest CAGR of 9.17% during the forecast period.

Insulin Pump Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key players are involved in adopting strategies such as mergers and acquisitions, partnerships, and the launch of new technologically advanced products and services to strengthen their foothold in the market. Key players are significantly investing in research and development to manufacture technologically advanced products.

Some prominent players in the global Insulin Pump market include:

  • Medtronic plc
  • Hoffmann-La Roche Ltd.
  • Tandem Diabetic Care, Inc.
  • Insulet Corporation
  • Ypsomed
  • Cellenovo
  • Sooil Development
  • Valeritas, Inc.
  • JingasuDelfu Co., Ltd.

Order a free sample PDF of the Insulin Pump Market Intelligence Study, published by Grand View Research.
Breast Cancer Diagnostics Market Growth Can Be Credited To the Increasing Prevalence of Cancer, 2028

Breast Cancer Diagnostics Industry Overview

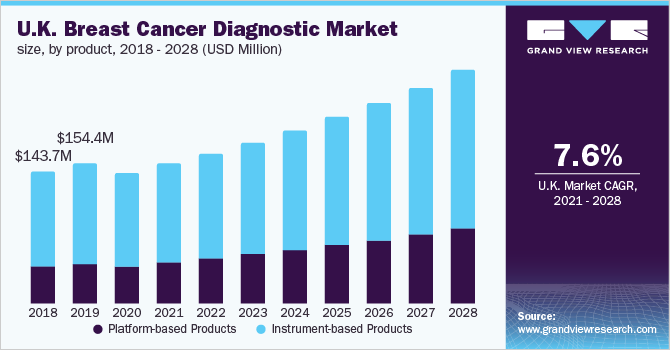
The global breast cancer diagnostics market size is expected to reach USD 6.8 billion by 2028, according to a new study by Grand View Research Inc. The market is expected to expand at a CAGR of 7.0% from 2021 to 2028. The growth is largely attributable to the increasing geriatric population exposed to the risk of breast cancer and early detection coupled with increasing awareness about breast cancer.

U.K. Breast Cancer Diagnostics Market size, by product, 2017 - 2028 (USD Million)

The introduction of 3D mammography or digital breast tomosynthesis, which is more accurate than 2D mammography, supports market growth. This advanced technology can detect 40.0% more cancers than 2D mammograms and reduce patient recalls. Rapid technological advancements are a major factor expected to drive the market over the coming years.

Breast Cancer Diagnostics Market Segmentation

Grand View Research has segmented the global breast cancer diagnostics market on the basis of type, product, application, end-use, and region:

Based on the Type Insights, the market is segmented into Imaging, Biopsy, Genomic Tests, Blood Tests, and Others

  • The imaging segment dominated the market for breast cancer diagnostics and accounted for the largest revenue share of 73.6% in 2020.
  • The blood tests segment is projected to be the fastest-growing segment during the forecast period due to several research studies being carried out globally by the research organizations and major players.

Based on the Product Insights, the market is segmented into Platform-based Products and Instrument-based Products

  • The instrument-based testing segment dominated the market for breast cancer diagnostics and accounted for the largest revenue share of 72.7% in 2020.
  • The platform-based products segment is anticipated to witness the fastest growth over the forecast period, owing to the novelty of products and the higher preference of such products for the targeted therapy.

Based on the Application Insights, the market is segmented into Screening, Diagnostic and Predictive, Prognostic, and Research

  • The diagnostics and predictive application segment dominated the market for breast cancer diagnostics and accounted for the largest revenue share of around 47.6% in 2020.
  • The prognostic segment is expected to witness a significant CAGR over the forecast period.

Based on the End-use Insights, the market is segmented into Hospitals & Clinics, Diagnostic Centers and Medical Laboratories, and Others

  • The hospitals and clinics segment dominated the market for breast cancer diagnostics and accounted for the largest revenue share of around 50.2% in 2020.
  • The diagnostic centers and medical laboratories segment is expected to witness a significant growth rate over the forecast period due to an increase in the number of initiatives undertaken by governments to provide various services, such as reimbursement for diagnostic tests.

Breast Cancer Diagnostics Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The key companies are adopting strategies such as mergers and acquisitions and partnerships, to acquire a larger market share, globally.

Some prominent players in the global Breast Cancer Diagnostics market include:

  • Hologic Inc.
  • Genomic Health (Exact Sciences Corporation)
  • BD
  • Danaher
  • Koninklijke Philips N.V.
  • QIAGEN
  • Thermo Fisher Scientific Inc.
  • Myriad Genetics
  • Argon Medical Devices, Inc.
  • Hoffmann-La Roche Ltd.

Order a free sample PDF of the Breast Cancer Diagnostics Market Intelligence Study, published by Grand View Research.
Key Factor Boosting the Per Diem Nurse Staffing Market Growth include Increasing Number of Healthcare Facilities

Per Diem Nurse Staffing Industry Overview

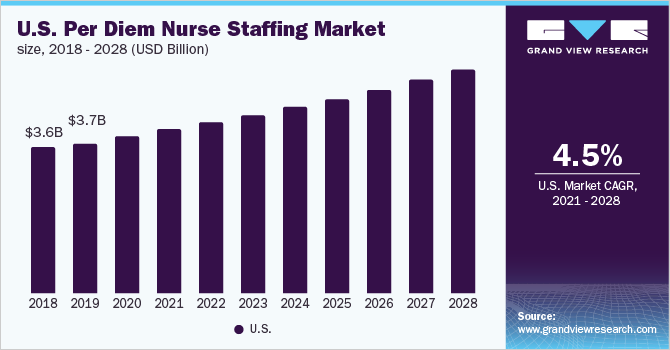
The global per diem nurse staffing market size is expected to reach USD 11.1 billion by 2028, registering a CAGR of 4.9% over the forecast period, according to a new report by Grand View Research, Inc. Higher demand for medical-surgical nurses & increased utilization of staffing agencies, and the rising demand for family nurse practitioners are driving the market. The rising geriatric population leads to an increase in the number of hospital admissions, which is another key factor boosting the market growth.

Moreover, the spread of infectious diseases, especially during flu season, is an important factor resulting in a sudden increase in the number of hospital admissions, thereby creating the need for additional nursing staff. For example, according to the Centers for Disease Control and Prevention (CDC), an estimated 959,000 people were hospitalized because of the 2017-2018 influenza season in the U.S. Similarly, the 2018-2019 flu season accounted for 69,000-84,000 hospital admissions in the U.S.

U.S. per diem nurse staffing market size, 2018 - 2028 (USD Billion)

Such temporary need for an additional nurse workforce can be easily fulfilled by per diem nurses, thereby augmenting the market growth. The COVID-19 pandemic has increased the pressure on the medical workforce. With hospitals being overburdened with COVID-19 patients, the demand for per diem nurse staffing is increasing exponentially. At this point, the main aim of healthcare facilities is to deploy the maximum number of medical staff for the management of COVID-19 patients.

Thus, the pandemic is driving market growth. With more patients being hospitalized, more nurses are required for the care, which is impelling the need for temporary nurses. According to June Pulse Survey by Staffing Industry Analysts (SIA), the demand for pre diem staffing increased by 6% during the COVID-19 pandemic. However, lower job security and stringent regulations are creating negativity in nurses to work as per diem nurses, which is a big challenge to the market.

Per Diem Nurse Staffing Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The market is fragmented with the presence of well-established as well as small-scale players, leading to higher competition among smaller players to sustain their market position. The high demand for nursing services by healthcare facilities leads to the adoption of various strategies, such as mergers & acquisitions, by players to maintain their market stronghold.

Some prominent players in the global Per Diem Nurse Staffing market include:

  • Cross Country Healthcare, Inc.
  • Health trust Workforce Solutions
  • Maxim Healthcare Group
  • Supplemental Healthcare
  • Accountable Healthcare Staffing
  • AMN Healthcare
  • Nurse Staffing LLC
  • GHR Healthcare
  • Interim HealthCare, Inc.
  • CareerStaff Unlimited

Order a free sample PDF of the Per Diem Nurse Staffing Market Intelligence Study, published by Grand View Research.
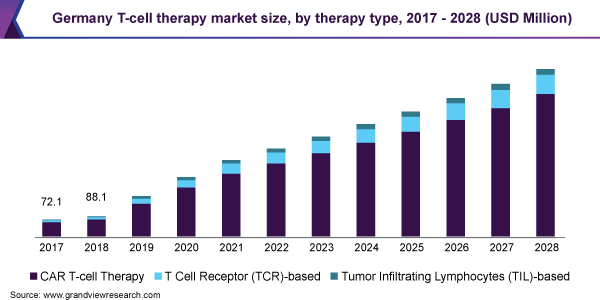
Surgical Snares Market is primarily driven by Increase in the Preference Keyhole Surgeries

Surgical Snares Industry Overview

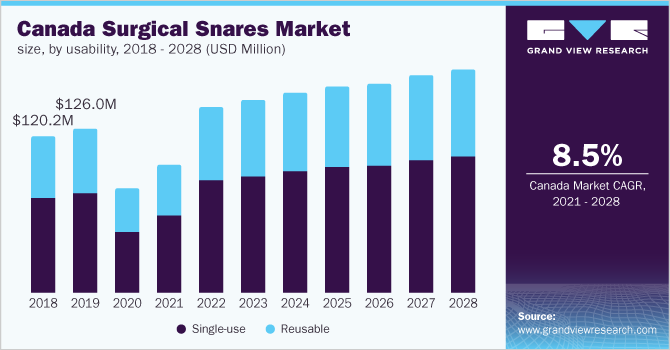
The global surgical snares market size is expected to reach USD 2.1 billion by 2028, according to a new report by Grand View Research, Inc. It is expected to expand at a CAGR of 9.4% from 2021 to 2028. The market is primarily driven by various factors such as an increase in the number of endoscopic ambulatory surgery centers and polypectomy procedures and the growing preference for minimally invasive surgeries. A significant increase in the number of gastrointestinal procedures in the U.S. and other developed economies is anticipated to support the market growth over the forecast period. Moreover, the increasing prevalence of chronic kidney diseases, the growing geriatric population suffering from chronic conditions, and increasing patient awareness are among the factors aiding in the market growth. Favorable reimbursement policies in major markets are promoting demand for surgical snares in various medical procedures.

Canada surgical snares market size, by usability, 2018 - 2028 (USD Million)

A constant rise in the geriatric population is leading to an increase in the financial burden on the healthcare system. According to the Population Reference Bureau, the number of people in the U.S. aged 65 and above is estimated to nearly double from 52 million in 2018 to 95 million by 2060. Such a rise in the elderly population is expected to subsequently result in greater demand for ablation devices for the treatment of tumors, thereby boosting the market growth.

Surgical Snares Market Segmentation

Grand View Research has segmented the global surgical snares market on the basis of usability, application, end use, and region:

Based on the Usability Insights, the market is segmented into Single-use and Reusable

  • The single-use segment accounted for the largest revenue share of over 60.0% in 2020.
  • The reusable segment is expected to witness the fastest growth over the forecast period. Cost-effectiveness offered by disposable devices is expected to be a growth factor.

Based on the Application Insights, the market is segmented into GI Endoscope, Laparoscopy, Urology Endoscopy, Gynecology Endoscopy, Arthroscopy, Bronchoscopy, Mediastinoscopy, Laryngoscopy, and Others

  • GI endoscope held the largest share of over 30.0% in 2020.
  • Arthroscopy is expected to expand at the fastest rate over the forecast period. The adoption of arthroscopic procedures is expected to increase owing to the rising geriatric population at risk of age-related disorders, such as arthritis, and rising incidence of joint injuries such as that of knee and shoulder.
  • Laparoscopy held a significant share in 2020.

Based on the End-use Insights, the market is segmented into Hospitals and Ambulatory Surgical Centers

  • The hospitals segment captured the largest share of over 75.0% in 2020.
  • Ambulatory surgical centers (ASCs) are anticipated to register the highest growth rate over the forecast period.

Surgical Snares Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The competition is highly dynamic with new entrants entering the market with the innovative product portfolio and major players maintaining their market share with mergers and acquisitions.

Some prominent players in the global Surgical Snares market include:

  • Medtronic
  • Boston Scientific Corporation
  • Medline Industries, Inc.
  • Olympus Corporation
  • Cook
  • CONMED Corporation
  • Steris (U.S.)
  • Merit Medical Systems
  • Avalign Technologies
  • Hill-Rom Holdings, Inc.
  • Sklar Surgical Instruments

Order a free sample PDF of the Surgical Snares Market Intelligence Study, published by Grand View Research.
T-cell Therapy Market is expected to Expand at a Compound Annual Growth Rate of 20.2% by 2028

T-cell Therapy Industry Overview

The global T-cell therapy market size is expected to reach USD 20.3 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 20.2% from 2021 to 2028. The milestone approvals of Kymriah and Yescarta along with the recent approval of Tecartus have bolstered the exponential revenue growth in the market.

Germany T-cell therapy market size, by therapy type, 2017 - 2028 (USD Million)

The commercial launch of these innovative therapies across various regions has spurred the investment flow in this arena thereby driving the market. Cancer indications are the major investment targets for the key operating players. However, space is constantly expanding to include other indications such as viral infections, creating lucrative opportunities for the operating players.

T-cell Therapy Market Segmentation

Grand View Research has segmented the T-cell therapy market on the basis of modality, therapy type, indications, and regions:

Based on the Modality Insights, the market is segmented into Research and Commercialized

  • The research segment dominated the market for T-cell therapy and accounted for more than 75.0% of revenue share in 2020 owing to the high number of products in the clinical development phase.
  • The commercial base is expected to witness growth owing to the increasing regulatory approvals for commercial products across various countries as well as a rise in the number of medical centers implementing these therapies

Based on the Type Insights, the market is segmented into CAR T-cell Therapy, T Cell Receptor (TCR)-based, and Tumor-Infiltrating Lymphocytes (TIL)-based

  • In 2020, CAR T-cell therapy segment dominated the market for T-cell therapy and accounted for the largest revenue share of 82.0% in 2020. This is owing to the exponential rise in the number of clinical trials for CAR-T therapies and the increasing involvement of key players in this arena.
  • esides this, T-cell receptor-based therapies pegged the second position in the global space owing to their potential in the treatment of solid tumors. This segment is gaining significant attention for the treatment of melanoma.

Based on the Indication Insights, the market is segmented into Hematologic Malignancies, Solid Tumors, and Others

  • In 2020, the hematologic malignancies segment dominated the market for T-cell therapy and accounted for a 49.0% revenue share.
  • Given the high number of market entities entering the market and high fixed costs of autologous cell manufacturing, the segment is expected to witness high market competition in the near future.

T-cell Therapy Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key companies are undertaking various strategic initiatives to maintain their market position

Some prominent players in the global T-cell Therapy market include:

  • Novartis AG
  • Merck KGaA
  • Gilead Sciences Inc.
  • TCR2 Therapeutics Inc
  • Bluebird Bio Inc.
  • Sorrento Therapeutics
  • Fate Therapeutics
  • Pfizer Inc.
  • Amgen
  • Celgene Corporation

Order a free sample PDF of the T-cell Therapy Market Intelligence Study, published by Grand View Research.
Traditional Wound Management Market Revenue is driven by Rising Number of Ambulatory Surgical Centers

Traditional Wound Management Industry Overview

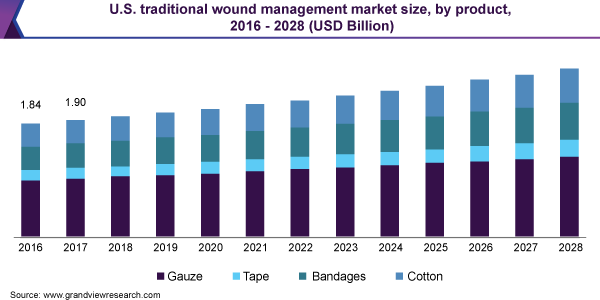
The global traditional wound management market size is expected to reach USD 7.7 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 3.7% from 2021 to 2028. The global increase in the incidence of chronic diseases such as diabetes, cancer, and other autoimmune diseases is one of the key driving factors for market growth. Factors such as the adoption of unhealthy and sedentary lifestyles, alcohol consumption, and smoking are majorly contributing to the rise in the prevalence of non-communicable diseases.

U.S. traditional wound management market size, by product, 2016 - 2028 (USD Billion)

Cancer has been a global healthcare burden as it is one of the leading causes of death. Most surgical wounds post-cancer surgery are relatively large in size and deep, producing exudate that requires regular care. The rising incidence of chronic diseases, increasing number of accidents, and rising number of ambulatory surgery centers (ASCs) are the key driving factors for the market.

Traditional Wound Management Market Segmentation

Grand View Research has segmented the global traditional wound management market on the basis of product, application, end-use, and region:

Based on the Product Insights, the market is segmented into Gauze, Tape, Bandage, and Cotton

  • The gauze segment dominated the market for traditional wound management and accounted for the largest revenue share of around 49.0% in 2020.
  • The tapes segment is anticipated to witness the fastest growth rate over the forecast period.

Based on the Application Insights, the market is segmented into Chronic Wounds and Acute Wounds

  • The acute wounds segment dominated the market and accounted for the largest revenue share of 59.9% in 2020.
  • Chronic wounds are anticipated to witness the fastest growth over the forecast period. The increasing cases of chronic diseases, especially diabetes, and the rising geriatric population across the globe are the major driving factors for the segment growth.

Based on the End-use Insights, the market is segmented into Hospitals, Clinics, Home Healthcare, and Others

  • The hospitals' segment dominated the market and held the largest revenue share of 45.4% in 2020.
  • The home healthcare segment is anticipated to witness the fastest growth over the forecast period.

Traditional Wound Management Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key players are involved in adopting strategies such as mergers and acquisitions, product launches, and partnerships to strengthen their position in the market.

Some prominent players in the global Traditional Wound Management market include:

  • Braun Melsungen AG
  • Johnson & Johnson Pvt. Ltd.
  • Medtronic PLC
  • Smith & Nephew
  • PAUL HARTMANN AG
  • Cardinal Health
  • Mölnlycke Health Care AB
  • Derma Sciences Inc.
  • Medline Industries, Inc.
  • BSN Medical

Order a free sample PDF of the Traditional Wound Management Market Intelligence Study, published by Grand View Research.
Key Players of Ophthalmic Ultrasound Devices Market include Optos, Escalon Medical Corp, and Appasamy associates

Ophthalmic Ultrasound Devices Industry Overview

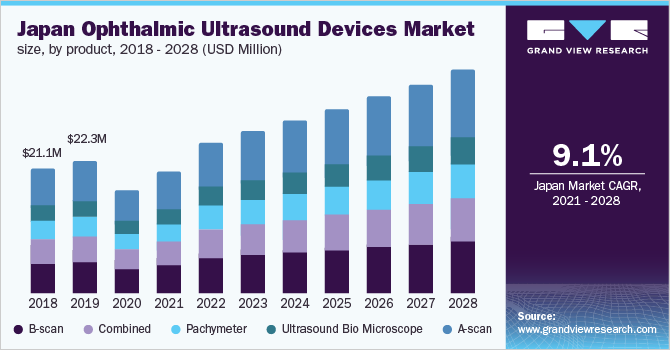
The global ophthalmic ultrasound devices market size is expected to reach USD 787.7 million by 2028, registering a CAGR of 8.36% over the forecast years, according to a new report by Grand View Research, Inc. Increasing incidence of diabetes, rising prevalence of ophthalmic disorders, such as cataract and proliferative diabetic retinopathy, growing awareness about cataract surgeries, and the introduction of technologically advanced ophthalmic ultrasounds are among the major factors anticipated to drive the market during the forecast period.

Japan ophthalmic ultrasound devices market size, by product, 2018 - 2028 (USD Million)

The rising burden of ophthalmic ailments, such as retinal & cataract detachments, and increased demand for effective and efficient imaging tools are further expected to drive the market growth. In addition, numerous novel product launches and technological advancements are expected to contribute to the market growth during the forecast period.

Ophthalmic Ultrasound Devices Market Segmentation

Grand View Research has segmented the global ophthalmic ultrasound devices market on the basis of product, mobility, end-use, and region:

Based on the Product Insights, the market is segmented into A-Scan, B-Scan, Combined, Pachymeter, and Ultrasound Bio Microscope

  • The A-scan product segment held the largest market share of 29.6% in 2020.
  • The B-scan segment is expected to grow at a CAGR of 8.30% during the forecast period. The increasing reach of these compact, affordable, lightweight, and multifunctional devices is expected to fuel the segment growth.

Based on the Mobility Insights, the market is segmented into Standalone and Portable

  • The standalone devices segment held the largest revenue share of more than 54% in 2020 owing to the factors, such as affordability and easy availability & handling.
  • The portable devices segment is anticipated to grow at the fastest CAGR during the forecast period.

Based on the End-use Insights, the market is segmented into Hospitals, Ambulatory Surgical Centers (ASCs), Ophthalmic Clinics, and Others

  • The hospitals segment accounted for the largest market share of more than 35% in 2020. Favorable government policies for the development of eye care facilities in different geographies are one of the major factors responsible for the largest market share of this segment.
  • The ophthalmic clinics segment had a considerable market share in 2020. The growing number of ophthalmologists in developing countries is expected to have a significant impact on the market growth with a steep rise in the number of ophthalmic clinics.

Ophthalmic Ultrasound Devices Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The leading players are focusing on growth strategies, such as innovations in the existing product, frequent product launches, and mergers& acquisitions.

Some prominent players in the global Ophthalmic Ultrasound Devices market include:

  • Halma plc
  • NIDEK CO. Ltd.
  • Quantel Medical
  • Optos
  • Escalon Medical Corp
  • Appasamy Associates
  • MicroMedical Devices
  • DGH Technology
  • Ellex
  • Carl Zeiss Meditech

Order a free sample PDF of the Ophthalmic Ultrasound Devices Market Intelligence Study, published by Grand View Research.
Ophthalmic Perimeters Market Organization Segment Trends, PEST Analysis and Forecast

Ophthalmic Perimeters Industry Overview

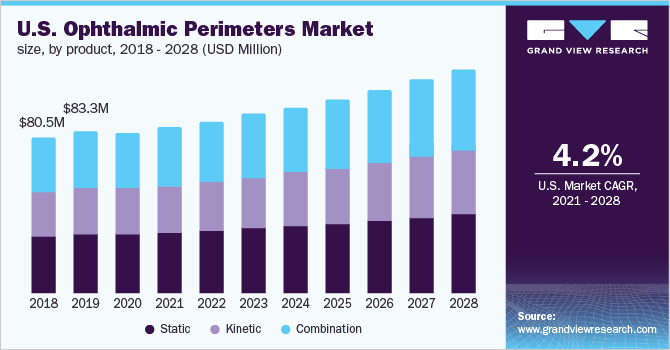
The global ophthalmic perimeters market size is anticipated to reach USD 371.7 million by 2028, according to a new report by Grand View Research, Inc., exhibiting a CAGR of 4.3% over the forecast period. The growing frequency of new product launches and an increasing number of strategic alliances between players & end-users are some of the major factors expected to boost growth.

U.S. Ophthalmic Perimeters Market size, by product

North America is anticipated to dominate the ophthalmic perimeters market during the forecast period owing to rising lifestyle and age-associated ophthalmic conditions such as glaucoma and cataract. An increase in demand for advanced early diagnostic techniques, a high adoption rate for advanced technologies, and favorable reimbursement scenarios are some of the major factors driving the market in the region.

Ophthalmic Perimeters Market Segmentation

Grand View Research has segmented the global ophthalmic perimeters market on the basis of product, application, end-use, and region:

Based on the Product Insights, the market is seagmented into Static, Kinetic, and Combination

  • The static perimeter segment dominated the market for ophthalmic perimeters and held the largest revenue share of 37.2% in 2020.
  • The combination ophthalmic perimeters segment is expected to witness the fastest CAGR of 4.5% over the forecast period.
  • The kinetic perimeter segment is expected to experience significant growth during the forecast period.

Based on the End-use Insights, the market is segmented into Hospital, Ophthalmic Clinic, and Others

  • The hospitals segment dominated the market and held the largest revenue share of 42.0% in 2020.
  • An increasing number of hospitals in developing countries and increasing competition in healthcare service providers are expected to boost the demand for advanced ophthalmic perimeters during the forecast period.
  • The growing prevalence of age and lifestyle associated with eye conditions and the increasing number of ophthalmologists in developing countries are factors expected to fuel the number of ophthalmic clinics. This, in turn, is expected to drive the segment.

Ophthalmic Perimeters Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

A significant number of ophthalmic perimeter manufacturers are in North America. These players are emphasizing on developing user-friendly ophthalmic perimeter devices by developing image processing software. Moreover, key players are conducting workshops and training programs. Such initiatives are expected to boost the overall growth.

Some prominent players in the global Ophthalmic Perimeters market include:

  • Haag-Streit AG
  • Carl Zeiss AG
  • Topcon Corporation
  • Nidek Co., Ltd.
  • Heidelberg Engineering GmbH
  • Optopol Technology Sp. z o.o.
  • Takagi Seiko Co., Ltd.
  • Kowa Company, Ltd.
  • Metrovision
  • Konan Medical USA, Inc.
  • Centervue S.P.A.

Order a free sample PDF of the Ophthalmic Perimeters Market Intelligence Study, published by Grand View Research.
Neurological Biomarkers Market Driver, Restraint, Challenges and Opportunities Study

Neurological Biomarkers Industry Overview

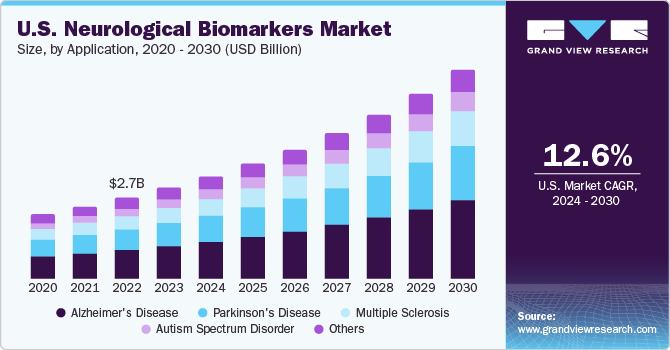
The global neurological biomarkers market size is expected to reach USD 16.14 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to grow at a CAGR of 12.9% from 2020 to 2028. Increasing funding for the R&D of neurological biomarkers to boost the development of new drugs is expected to accelerate market growth. Moreover, the introduction of novel innovative products for the diagnosis of neurological biomarkers is expected to propel market growth over the forecast period.

U.S. neurological biomarkers market size, by application, 2018 - 2028 (USD Billion)

The National Institute of Neurological Disorders and Stroke provides funding, such as development grants & cooperative agreements for researchers conducting studies related to biomarker discovery, analytical validation, & clinical validation. Thus, the presence of organizations offering funds at various stages of research is anticipated to drive market growth. For instance, the University of North Texas Health Science Center (HSC) was awarded around USD 45.5 million funds from the National Institutes of Health (NIH) to support research regarding health disparities in Alzheimer’s and brain aging. NIH is offering additional funds for biomarkers research for the ongoing Health and Aging Brain Among Latino Elders (HABLE) study.

Neurological Biomarkers Market Segmentation

Grand View Research has segmented the global neurological biomarkers market on the basis of type, application, end-use, and region:

Based on the Type Insights, the market is segmented into Genomic, Proteomic, Metabolomic, Imaging, and Others

  • The proteomic segment accounted for the highest revenue share of over 32% in 2020. Genomic biomarkers accounted for the second-largest market share in 2020.
  • The others segment is anticipated to witness significant CAGR over the forecast period due to the increasing adoption of digital biomarkers in clinical trials patient selection for neurological drugs.

Based on the Applications Insights, the market is segmented into Alzheimer’s Disease, Parkinson’s Disease, Multiple Sclerosis, Autism Spectrum Disorder, and Others

  • The Alzheimer’s disease application segment accounted for the largest market share of over 34% in 2020 and is expected to remain dominant during the forecast period.
  • The Parkinson’s disease application segment is expected to grow at a CAGR of 13.2% during the forecast period owing to the growing prevalence of the disease and an increasing number of clinical trials for the disease drugs.

Based on the End-use Insights, the market is segmented into Hospital & Hospital Laboratories, Independent Clinical Diagnostic Centers, and Research Organizations & Others

  • The hospital & hospital laboratories segment accounted for the largest market share of over 38% in 2020. The segment is expected to remain dominant even during the forecast period due to a rise in hospitalization.
  • The research organizations & others segment is expected to grow at the fastest CAGR of more than 13% over the forecast years owing to the increased adoption of biomarkers by pharmaceutical companies and Ambulatory Surgery Centers (ASCs) for drug discovery & development.

Neurological Biomarkers Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Companies are adopting strategies that allow them to use their resources to aid in the development of new products and enhance their supply chain.

Some prominent players in the global Neurological Biomarkers market include:

  • Abbott Laboratories
  • Thermo Fisher Scientific, Inc.
  • Bio-Rad Laboratories, Inc.
  • Merck & Co., Inc.
  • Johnson & Johnson Services, Inc.
  • Banyan Biomarkers, Inc.
  • Myriad Genetics, Inc.
  • DiaGenic ASA
  • Quanterix

Order a free sample PDF of the Neurological Biomarkers Market Intelligence Study, published by Grand View Research.
Consumer Genomics Market Size, Challenges Analysis, Porter’s Five Forces Study and Forecast

Consumer Genomics Industry Overview

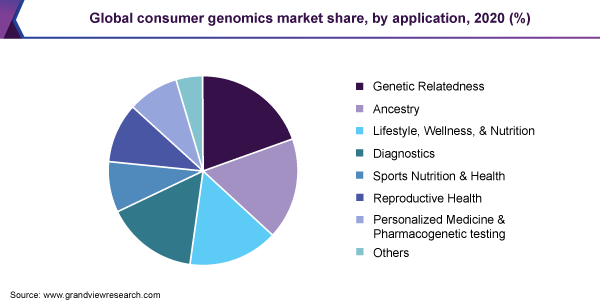
The global consumer genomics market size is projected to reach USD 8.1 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 19.4% from 2021 to 2028. Technological advances in genetic research have helped to raise awareness among physicians as well as consumers pertaining to the use of gene-based testing.

Global consumer genomics market share, by application, 2020 (%)

Genomics testing enables the determination of common traits by studying a DNA molecule, predictions about health, and offers evidence of a person’s ancestry. Several companies are providing DNA tests directly to customers by which they have access to their genetic information without involving the healthcare professional. Rising awareness about DNA testing has driven the adoption rate, which in turn provides healthy growth prospects for the implementation of DNA tests in home settings.

Consumer Genomics Market Segmentation

Grand View Research has segmented the global consumer genomics market on the basis of application and region:

Based on the Application Insights, the market is segmented into Genetic Relatedness, Diagnostics, Lifestyle, Wellness, & Nutrition, Ancestry, Reproductive Health, Personalized Medicine & Pharmacogenetic testing, Sports Nutrition & Health, and Others

  • The genetic relatedness segment led the market for consumer genomics and accounted for the largest revenue share of 19.9% in 2020.
  • The lifestyle, wellness, and nutrition segment is expected to witness the fastest CAGR as consumer genomics tests are claimed to provide personalized nutrition based on an individual’s genotype
  • Growing public interest for personalized health has fueled the adoption of nutrigenetic testing services, specifically for optimizing nutrition
  • Hence, personalized nutrition is employed to maintain or improve health by using genetic, clinical, and dietary information to provide precise and more efficacious personalized healthy recommendations

Consumer Genomics Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Prominent market players have adopted strategic initiatives to establish their market presence through acquisitions, product launches, and other strategies.

Some prominent players in the global Consumer Genomics market include:

  • Ancestry
  • Gene By Gene, Ltd. (FamilyTree DNA)
  • 23andMe, Inc.
  • Color Genomics, Inc
  • Myriad Genetics, Inc
  • Mapmygenome
  • Positive Biosciences, Ltd
  • Futura Genetics
  • Helix OpCo LLC
  • MyHeritage Ltd.
  • Pathway Genomics
  • Veritas

Order a free sample PDF of the Consumer Genomics Market Intelligence Study, published by Grand View Research.
Advanced Wound Dressing Market Distribution Channel Outlook and Regional Trend Study

Advanced Wound Dressing Industry Overview

The global advanced wound dressing market size is expected to reach USD 9.9 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 5.5% from 2021 to 2028. An increasing number of accidents, the impact of COVID-19, and technological advancements are the key driving factors for the market. The increasing incidence of accidents such as road accidents, burns, and trauma events across the globe is anticipated to drive the market. For instance, as per the WHO (2018), around 1,000,000 people are severely or moderately burnt in India per year. In addition, as per NCBI, in 2017, countries such as Bulgaria, Finland, the Netherlands, China, Australia, and the U.K. reported a rise in the incidence of burn injuries.

Furthermore, as per the American Association for the Surgery of Trauma, in 2017, around 1.2 million people died globally, accounting for the deaths of around 3,242 people per day in road accidents every year. Road accidents mostly occur in middle- or low-income countries. The advanced wound dressing is majorly used for the faster healing of all kinds of burns injuries. Moreover, bandages and gauzes are also used for the treatment of minor injuries. Thus, the rising number of accidents is expected to boost the demand for advanced wound dressing, which is expected to lead to considerable market growth over the forecast period.

Advanced Wound Dressing Market Segmentation

Grand View Research has segmented the advanced wound dressing market on the basis of product, application, end-use, and region:

Based on the Products Insights, the market is segmented into Foam, Hydrocolloid, Film, Alginate, Hydrogel, Collagen, and Other Advanced Dressings

  • The foam dressings segment dominated the market for advanced wound dressing and accounted for the largest revenue share of 23.6% in 2020.
  • The hydrocolloid dressings segment is anticipated to witness the fastest growth rate over the forecast period. Hydrocolloid dressings are made up of gel-forming agents such as Carboxy Methylcellulose (CMC) and gelatin.

Based on the Application Insights, the market is segmented into Chronic Wounds and Acute Wounds

  • The acute wounds segment dominated the market for advanced wound dressing and accounted for the largest share of 60.1% in 2020.
  • The chronic wounds segment is anticipated to witness a considerable growth rate over the forecast period. The increasing cases of chronic diseases, especially diabetes, and the rising geriatric population in the country are the major driving factors for the segment growth.

Based on the End-use Insights, the market is segmented into Hospitals, Specialty Clinics, Home Healthcare, and Others

  • The hospitals' segment dominated the market for advanced wound dressing and accounted for the largest revenue share of 44.9% in 2020. The increasing cases of diabetic foot ulcers and venous leg ulcers are the major driving factors for the growth of the segment.
  • Home Healthcare is expected to witness the fastest growth over the forecast period.

Advanced Wound Dressing Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key players are involved in adopting strategies such as mergers and acquisitions, partnerships, and launching new products to strengthen their foothold in the market for advanced wound dressing.

Some prominent players in the global Advanced Wound Dressing market include:

  • Smith & Nephew PLC
  • Mölnlycke Health Care AB
  • Convatec Group
  • Baxter
  • Coloplast Corp
  • Medtronic
  • 3M
  • Derma Sciences Inc.
  • Medline Industries, Inc.

Order a free sample PDF of the Advanced Wound Dressing Market Intelligence Study, published by Grand View Research.
U.S. Medical Device Manufacturers Market Profit Margin and Business Environment Study

U.S. Medical Device Manufacturers Industry Overview

The U.S. medical device manufacturers market size is expected to reach USD 262.4 billion by 2028 and is projected to expand at a CAGR of 5.0%, according to a new report by Grand View Research, Inc. The regional market is significantly driven by the high healthcare expenditure of the country. The increasing geriatric population coupled with the rising prevalence of chronic diseases is also expected to augment the market growth over the forecast period.

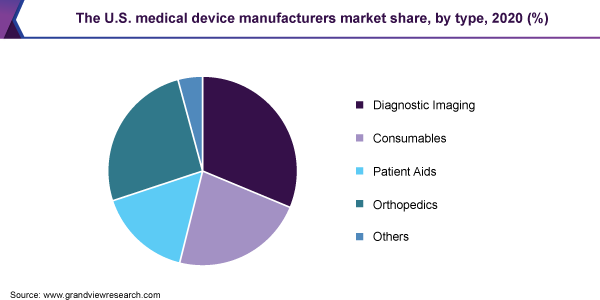
The U.S. medical device manufacturers market size, by type, 2020 (%)

The COVID-19 pandemic triggered a drastic rise in demand for medical consumables and patient aids, such as gloves, syringes, masks, PPE kits, infrared thermometers, pulse oximeter, testing kits, etc. This resulted in an immense opportunity for the existing players as well as new entrants. However, the pandemic also resulted in a massive reduction in elective procedures, such as bariatric surgeries, joint replacement surgeries, cosmetic surgeries, etc., thus restricting the growth of medical devices used in the aforementioned procedures. The market recovery can be expected from mid-2021 onwards with favorable government initiatives to re-launch elective procedures.

U.S. Medical Device Manufacturers Market Segmentation

Grand View Research has segmented the U.S. medical device manufacturers market on the basis of type:

Based on the Type Insights, the market is segmented into Diagnostic Imaging, Consumables, Patient Aids, Orthopedics, and Others

  • The diagnostic imaging segment captured the largest market share of over 31% in 2020 owing to the high demand for accurate diagnostic methods and devices.
  • Chronic diseases accounted for a significant share of the country’s healthcare expenditure, as they require long-term medical care.
  • Furthermore, an increase in the number of sports and trauma injuries is boosting demand for orthopedic devices, leading to market growth.

Key Companies Profile & Market Share Insights

New product launches, technological advancements, and capacity expansion are few strategic initiatives undertaken by key players to achieve competitive advantage. New technologies, such as 3D printing, can be used to increase production to meet the sudden upsurge in product demand due to the global coronavirus pandemic. The U.S. government is spending heavily to overcome the shortfalls in medical devices, such as pulse oximeter and N95 respirators.

Some prominent players in the U.S. Medical Device Manufacturers market include:

  • 3M Healthcare
  • Abbott
  • Baxter International, Inc.
  • Braun Melsungen AG
  • GE Healthcare
  • Johnson & Johnson Services, Inc.
  • Medtronic PLC
  • Boston Scientific Corp.

Order a free sample PDF of the U.S. Medical Device Manufacturers Market Intelligence Study, published by Grand View Research.
Ophthalmic Packaging Market Profit Margin Breakdown and Sales Channels Overview

Ophthalmic Packaging Industry Overview

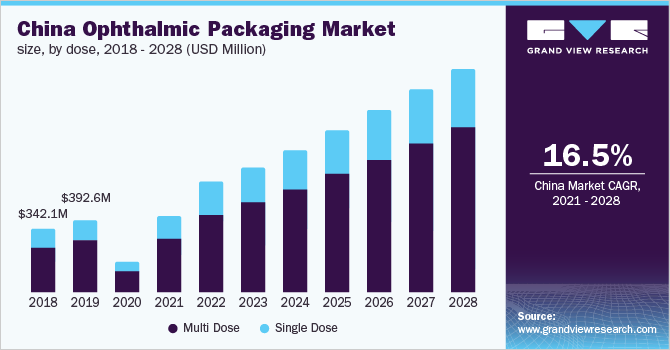
The global ophthalmic packaging market is expected to reach USD 17.7 billion by the end of 2028, according to a new report by Grand View Research, Inc. It is projected to expand at an 11.9% CAGR over the forecast period. The increasing global burden of ocular conditions and a growing number of ophthalmic clinics, hospitals, and ambulatory care centers are the factors driving the market growth. Additionally, the frequent introduction of new drug delivery systems and high demand for advanced packaging solutions is expected to fuel the market during the forecast period.

China ophthalmic packaging market size, by dose, 2018 - 2028 (USD Million)

Increasing healthcare expenditure and rising disposable income are some of the prominent factors that are expected to drive a lot of patients towards advanced ophthalmic care. Furthermore, the growing number of advanced healthcare facilities such as eye hospitals and ophthalmic clinics across several regions and increasing awareness about preventive care, ocular disorders, and self-medications are some of the factors expected to aid the market growth.

Ophthalmic Packaging Market Segmentation

Grand View Research has segmented the ophthalmic packaging market on the basis of dose, type, material, and regions:

Based on the Dose Insights, the market is segmented into Multi Dose and Single Dose

  • The multidose segment dominated the market in 2020 with over 70.0% share. The high penetration index of multidose containers in the OTC market is a key factor fueling the segment growth.
  • The single-dose packaging segment will be driven by the demand for single-dose packaging in eye-related surgeries and improved healthcare manufacturing facilities.

Based on the Type Insights, the market is segmented into OTC and Prescription

  • The prescription segment dominated the market with a revenue share of over 55.0% in 2020 owing to its large-scale use as a first-line treatment.
  • The OTC segment is expected to grow at a healthy rate during the forecast period.

Based on the Material Insights, the market is segmented into Glass, Plastics, and Others

  • Plastic led the market with a revenue share of over 45.0% in 2020 and is expected to witness significant growth during the forecast period.
  • The plastic segment is mainly driven by its lower weight, cost-efficiency, and convenience.

Ophthalmic Packaging Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key market players are adopting strategic initiatives such as M&As, partnerships, product differentiation, product designing, and collaborations to gain a competitive edge in the marketplace.

Some prominent players in the global Ophthalmic Packaging market include:

  • Amcor Ltd.
  • West Pharmaceutical Service Inc.
  • Gerresheimer AG
  • BD
  • Schott AG
  • Aptar Group

Order a free sample PDF of the Ophthalmic Packaging Market Intelligence Study, published by Grand View Research.
Liver Cancer Diagnostics Market Key Company Overview and Financial Performance

Liver Cancer Diagnostics Industry Overview

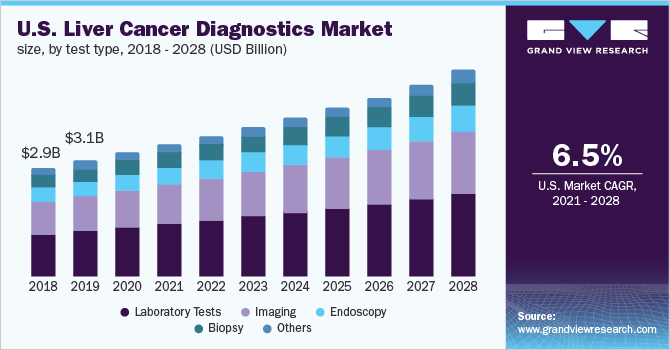
The global liver cancer diagnostics market size is expected to reach USD 17.4 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 7.5% from 2021 to 2028. The rising prevalence of liver cancer and the introduction of innovative diagnosis products are propelling the market growth.

U.S. liver cancer diagnostics market size, by test type, 2018 - 2028 (USD Billion)

According to the data published by Globocan, liver cancer was the 6th most common type of cancer and, in 2020, around 905,677 new cases of this life-threatening disease were diagnosed, globally, which lead to around 830,180 deaths. The most common cause of liver cancer is chronic (long-term) infection with Hepatitis C Virus (HCV) or Hepatitis B Virus (HBV). As per the WHO’s estimates, globally, around 71.0 million people have chronic HCV infection. As per the same source, in 2016, around 399,000 people died from cirrhosis and primary liver cancer related to HCV infection. Such a high prevalence and mortality rate of the disease has significantly upsurged the demand for innovative diagnostic solutions for its timely diagnosis, thus, supporting market growth.

Liver Cancer Diagnostics Market Segmentation

Grand View Research has segmented the global liver cancer diagnostics market based on test type, end-use, and region:

Based on the Test Type Insights, the market is segmented into Laboratory Tests, Imaging Tests, Endoscopy, Biopsy, and Others

  • In 2020, the laboratory tests segment dominated the market for liver cancer diagnostics and accounted for the largest revenue share of 39.5%.
  • The imaging tests segment accounted for the second-largest revenue share and is anticipated to show significant growth throughout the study period.
  • Imaging tests include Computed Tomography (CT) scan, Magnetic Resonance Imaging (MRI) scan, X-ray, ultrasound, and other radiographic tests.

Based on the End-use Insights, the market is segmented into Hospitals & Diagnostic Laboratories, Academic & Research Institutes, and Pharmaceutical & CRO Laboratories

  • The hospitals and diagnostic laboratories segment dominated the market for liver cancer diagnostics in 2020 and accounted for the largest revenue share of 82.4%.
  • The pharmaceutical and CRO laboratories segment is anticipated to witness the fastest CAGR during the forecast period.

Liver Cancer Diagnostics Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Key players are undertaking inorganic growth strategies such as mergers and acquisitions to expand their market share.

Some prominent players in the global Liver Cancer Diagnostics market include:

  • Abbott Laboratories
  • Hoffmann-La Roche Ltd.
  • Qiagen N.V.
  • Thermo Fisher Scientific, Inc.
  • Siemens Healthineers
  • Becton Dickinson & Company
  • Illumina, Inc.
  • Koninklijke Philips N.V
  • Epigenomics AG
  • Fujifilm Medical Systems U.S.A., Inc.

Order a free sample PDF of the Liver Cancer Diagnostics Market Intelligence Study, published by Grand View Research.
Actinic Keratosis Treatment Market Profit Margin Analysis & Growth Prospect Mapping

Actinic Keratosis Treatment Industry Overview

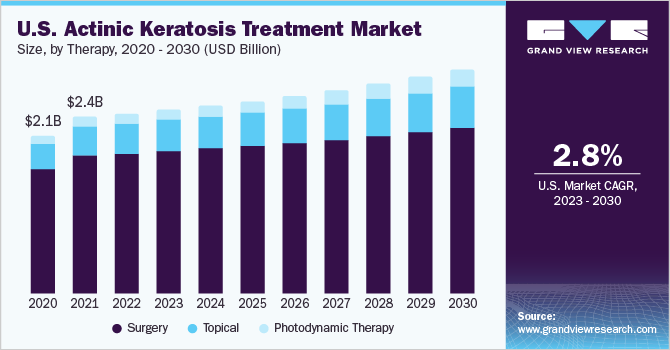
The global actinic keratosis treatment market size is expected to reach USD 8.12 billion by 2028 according to a new report by Grand View Research, Inc. The market is anticipated to grow at a CAGR of 4.3% over the forecast period owing to a rise in demand for AK treatment products, increasing awareness among people, and favorable government initiatives. However, the COVID-19 pandemic has affected the market adversely. A downfall has been observed in the diagnosis and treatment rate of actinic keratosis in 2020, globally.

U.S. actinic keratosis treatment market size, by therapy, 2018 - 2028 (USD Billion)

Key pharmaceutical companies are collaborating to develop novel therapies to treat actinic keratosis. For instance, in December 2017, Almirall, S.A., and Athenex, Inc. collaborated to develop KX2-391(tirbanibulin), an investigational drug for AK treatment. According to the deal, Athenex, Inc. granted the development and commercialization rights to Almirall, S.A. in the U.S. and Europe. Furthermore, in December 2020, Almirall, S.A. received the U.S. FDA approval for Klisyri (tirbanibulin) and was commercialized in February 2021 in the U.S.

Actinic Keratosis Treatment Market Segmentation

Grand View Research has segmented the global actinic keratosis treatment market on the basis of therapy, drug class, end-use, and region:

Based on the Therapy Insights, the market is segmented into Topical, Surgery, and Photodynamic Therapy

  • The surgical therapy segment dominated the global market in 2020 with a revenue share of more than 65%. The segment is anticipated to maintain its dominance over the forecast period.
  • The photodynamic therapy segment is anticipated to grow at a CAGR of 7.4% over the forecast period.

Based on the Drug Class Insights, the market is segmented into Nucleoside Metabolic Inhibitor, NSAIDs, Immune Response Modifiers, Photoenhancers, and Others

  • The nucleoside metabolic inhibitors drug class segment led the global market in 2020 with a revenue share of over 32%.
  • The photo-enhancers segment is estimated to witness the fastest CAGR during the forecast period.

Based on the End-use Insights, the market is segmented into Hospitals, Private Clinics, Homecare, and Others

  • The hospital segment led the global treatment market in 2020 accounting for a revenue share of 30%.
  • The home care segment is anticipated to grow at the fastest CAGR over the forecast period.

Actinic Keratosis Treatment Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Many generic pharmaceutical companies are involved in the manufacturing & distribution of topical drugs, which makes the global market highly competitive.

Some prominent players in the global Actinic Keratosis Treatment market include:

  • Sun Pharmaceutical Industries Ltd.
  • Novartis AG
  • GALDERMA
  • Hill Dermaceuticals, Inc.
  • Viatris Inc.
  • Mylan N.V.
  • Bausch Health Companies Inc.
  • LEO Pharma A/S
  • Almirall, S.A.
  • Biofrontera AG
  • 3M

Order a free sample PDF of the Actinic Keratosis Treatment Market Intelligence Study, published by Grand View Research.

Inflammatory Bowel Disease Treatment Market Driver, Restraint, Challenges and Opportunities Study

Inflammatory Bowel Disease Treatment Industry Overview

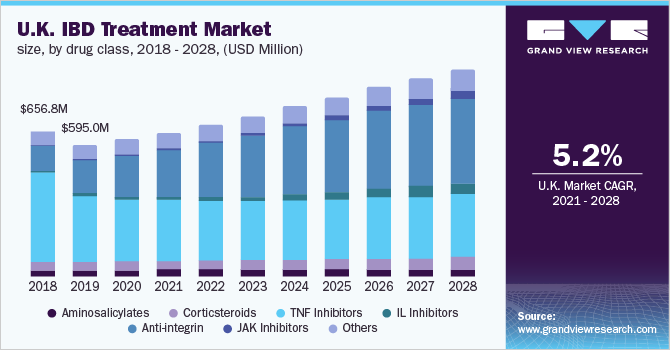
The global inflammatory bowel disease treatment market size is expected to reach USD 27.8 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 4.8% from 2021 to 2028. Increasing awareness about the disease, rise in geriatric population, and favorable initiatives undertaken by regulatory bodies are anticipated to drive the market growth over the forecast period. For instance, in January 2020, the U.S. FDA allowed ABIVAX to conduct a phase 2B clinical trial of ABX464 on U.S. patients living with moderate-to-severe ulcerative colitis.

U.K. IBD treatment market size, by drug class, 2018 - 2028 (USD Million)

Increasing adoption of strategies such as new product development and expansion is expected to drive market growth. For instance, in June 2020, Takeda Pharmaceutical received U.S. FDA approval to manufacture Entyvio (vedolizumab) in its U.S.-based manufacturing facility. The approval is expected to support the growing demand for the drug in the U.S. and nearby countries. Moreover, Takeda pharmaceutical is heavily investing in the development of the market in China.

Inflammatory Bowel Disease Treatment Market Segmentation

Grand View Research has segmented the global inflammatory bowel disease treatment market on the basis of type, drug class, route of administration, distribution channel, and region:

Based on the Type Insights, the market is segmented into Crohn's Disease and Ulcerative Colitis

  • Crohn’s disease dominated the market for inflammatory bowel disease treatment and accounted for the largest revenue share of 61.3% in 2020.
  • The ulcerative colitis segment is anticipated to witness significant growth over the forecast period due to the high patient base and increasing approval of biologics for the treatment of ulcerative colitis.

Based on the Drug Class Insights, the market is segmented into Aminosalicylates, Corticosteroids, TNF inhibitors, IL inhibitors, Anti-integrin, JAK inhibitors, and Others

  • The TNF inhibitors segment dominated the market for inflammatory bowel disease treatment and accounted for the largest revenue share of 47.8% in 2020.
  • JAK inhibitors are expected to grow at the fastest rate over the forecast period. The recent approval of Pfizer’s Xeljanz for the treatment of ulcerative colitis and the presence of late-phase pipeline candidates such as upadacitinib, tofacitinib, and filgotinib are expected to drive the JAK inhibitors segment growth over the forecast period.

Based on the Route of Administration Insights, the market is segmented into Oral and Injectable

  • The injectable segment dominated the market for inflammatory bowel disease treatment and accounted for a revenue share of more than 75.0% in 2020.
  • The oral route of drug administration is estimated to witness the highest growth rate over the forecast period.

Based on the Distribution Channel Insights, the market is segmented into Hospital Pharmacy, Retail Pharmacy, and Online Pharmacy

  • The hospital pharmacy segment dominated the market for inflammatory bowel disease treatment and accounted for the largest revenue share of 46.8% in 2020.
  • The online pharmacy segment is expected to grow at the fastest rate in the next 6 to 8 years.

Inflammatory Bowel Disease Treatment Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Major pharmaceutical companies are largely involved in the development of novel therapies to treat the severe condition of inflammatory bowel disease.

Some prominent players in the global Inflammatory Bowel Disease Treatment market include:

  • AbbVie Inc.
  • Biogen
  • Johnson & Johnson Services, Inc.
  • Amgen Inc.
  • UCB S.A.
  • Novartis AG
  • Takeda Pharmaceutical Company Limited
  • Merck & Co., Inc.
  • Pfizer Inc.
  • Lilly

Order a free sample PDF of the Inflammatory Bowel Disease Treatment Market Intelligence Study, published by Grand View Research.

Anatomic Pathology Market Size Outlook, End Use Estimates and Trend Analysis

Anatomic Pathology Industry Overview

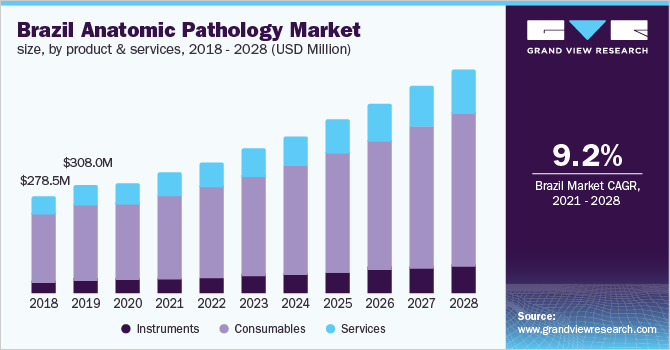
The global anatomic pathology market size is expected to reach USD 34.66 billion by 2028, according to a new report by Grand View Research, Inc. It is expected to expand at a CAGR of 10.08% from 2021 to 2028. The advent of technology in the instruments and the protocols used during the anatomic pathological procedures is anticipated to increase the adoption rate of advanced anatomic pathological instruments.

Brazil anatomic pathology market size, by product & services, 2018 - 2028 (USD Million)a

Market players are collaborating for the refurbishment of pathology products by the incorporation of innovative disease diagnostic models. In April 2021, Leica Biosystems collaborated with Paige, an AI-based diagnostics company, for expanded access to computational pathology products for translational and clinical research. Under this partnership, Paige’s AI-enabled research software and Leica Biosystems’ digital pathology platform were combined. This, in turn, accelerates investments in the up-gradation of pathological equipment.

Anatomic Pathology Market Segmentation

Grand View Research has segmented the global anatomic pathology market on the basis of product and services, application, end-use, and region:

Based on the Product & Services Insights, the market is segmented into Instruments, Consumables, and Services

  • The consumables segment dominated the market in 2020 with a share of over 65.0%.
  • The ongoing technological advancements and focused efforts by the market participants to offer anatomic pathological instruments with an improved design are anticipated to bolster the growth of the instruments segment.

Based on the Application Insights, the market is segmented into Disease Diagnosis, Drug Discovery and Development, and Others

  • The disease diagnosis segment accounted for the largest share of over 55.0% in 2020.
  • The drug discovery and development segment is anticipated to grow at a lucrative pace over the forecast period.

Based on the End-use Insights, the market is segmented into Hospitals, Research Laboratories, Diagnostic Laboratories, and Others

  • The hospitals segment dominated the market with a revenue share of over 45.0% in 2020 owing to the high hospitalization rate of cancer patients, coupled with a substantial number of frequent readmissions in hospitals.
  • The emergence of advanced testing techniques and equipment has led to a lucrative growth of the diagnostic laboratories segment.

Anatomic Pathology Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Anatomic pathology is a mature industry with a large number of key players in it. The advent of new strategic plans to maintain competitiveness stimulates market growth. The market is well equipped with upcoming and innovative instruments and consumables to address the challenges in transforming pathology trends.

Some prominent players in the global Anatomic Pathology market include:

  • Danaher Corporation
  • Laboratory Corporation of America Holdings
  • Quest Diagnostics Incorporated
  • Sakura Finetek USA, Inc.
  • Hoffmann-La Roche AG
  • Agilent Technologies, Inc.
  • PHC Holdings Corporation
  • Cardinal Health
  • Bio SB
  • NeoGenomics Laboratories, Inc.
  • BioGenex

Order a free sample PDF of the Anatomic Pathology Market Intelligence Study, published by Grand View Research.

Why the Catalyst Market Quietly Runs Half of Modern Manufacturing

Catalysts rarely make headlines, but they sit behind much of modern industry. They turn crude oil into cleaner fuels, help make the plastics...