Sinus Dilation Device Market Driver, Restraint, Challenges and Opportunities Study

Sinus Dilation Device Industry Overview

The global sinus dilation device market size is estimated to reach USD 4.6 billion by 2028, registering a CAGR of 11.0%, according to a new report by Grand View Research, Inc. Changes in lifestyle, increasing cases of obesity, and a resultant rise in the incidence of sinus-related conditions are the major factors contributing to the market growth. The introduction of technologically advanced devices is also one of the key factors boosting market growth. Major market players are focusing on R&D activities to introduce minimally invasive procedures creating a positive impact on the adoption of MIS procedures.
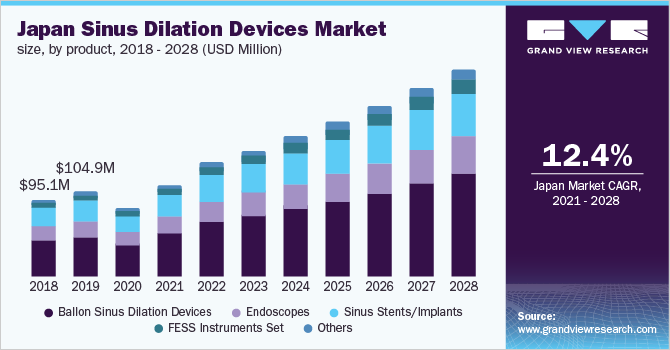
Japan sinus dilation devices market size, by product, 2018 - 2028 (USD Million)

Some of the inventions in the market related to endoscopic approaches include a nasal endoscope, rhinoscopes, and balloon sinus dilation devices. An increase in medical reimbursements across major markets is likely to fuel the market growth. Rising adoption of health insurance and growing per capita expenditure coupled in developed as well as developing countries is predicted to augment the market growth.

Sinus Dilation Device Market Segmentation

Grand View Research has segmented the global sinus dilation device market on the basis of product, procedure, application, end use, and region:

Based on the Product Insights, the market is segmented into Balloon Sinus Dilation Devices, Endoscopes, Functional Endoscopic Sinus Surgery (FESS) Instruments Set, Sinus Stents/Implants, and Others

  • The Balloon Sinus Dilation (BSD) devices segment captured the largest revenue share of more than 47% in 2020.
  • The Functional Endoscopic Sinus Surgery (FESS) Instruments Set segment is anticipated to register the fastest growth rate of more than 14% over the forecast period.

Based on the Procedure Insights, the market is segmented into Standalone and Hybrid

  • The standalone procedure segment captured the highest revenue share of over 68% in 2020.
  • Hybrid functional endoscopic sinus surgery balloon dilation procedure is effective in both pediatric and adult patients. Thus, increasing preference for hybrid procedures for adult and pediatric patients is anticipated to boost the market growth.

Based on the Application Insights, the market is segmented into Adult and Pediatric

  • The adult patient segment accounted for the highest revenue share of more than 68% in 2020 owing to the high prevalence of sinusitis in adults.
  • The pediatric segment is anticipated to register the fastest CAGR during the forecast period. The growth can be attributed to the rise in the occurrence of sinusitis among children.

Based on the End-use Insights, the market is segmented into Hospitals, ENT Clinics/In-office, and Ambulatory Surgical Centers (ASCs)

  • The hospitals segment accounted for the largest revenue share of over 51% in 2020 and is expected to witness considerable growth during the forecast period owing to the high volume of surgical procedures performed in hospitals.
  • The Ambulatory Surgical Centers (ASCs) segment is expected to witness the fastest CAGR during the forecast period.

Sinus Dilation Device Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The market is highly consolidated with a few major companies accounting for a majority of the market share. Product launch, product approval, strategic acquisitions, and innovations are some of the key business strategies adopted by the market players to retain their market share and expand their geographic reach.

Some prominent players in the global Sinus Dilation Device market include:

  • Stryker
  • Smith & Nephew
  • Olympus Corporation
  • Medtronic

Order a free sample PDF of the Sinus Dilation Device Market Intelligence Study, published by Grand View Research.
Clinical Oncology Next Generation Sequencing Market Application Outlook and Research Report

Clinical Oncology Next Generation Sequencing Industry Overview

The global clinical oncology next generation sequencing market size is expected to reach USD 892.61 million by 2028 registering a CAGR of 14.70%, according to a new report by Grand View Research, Inc. Technological advancements in next-generation sequencing coupled with high adoption of companion diagnostics and personalized medicine drive the global market growth.

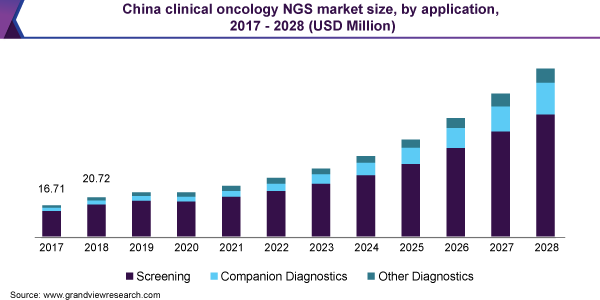
China clinical oncology NGS market size, by application, 2017 - 2028 (USD Million)

In addition, a rise in the utility of next generation sequencing (NGS) for liquid biopsy is expected to increase revenue generation in the market. NGS is employed to sequence circulating tumor DNA (ctDNA) for the analysis of liquid biopsy samples. This leads to efficient molecular profiling of tumors, which, in turn, facilitates real-time, non-invasive monitoring of tumors.

Clinical Oncology Next Generation Sequencing Market Segmentation

Grand View Research has segmented the global clinical oncology next generation sequencing market on the basis of technology, workflow, application, end-use, and region:

Based on the Technology Insights, the market is segmented into Whole Genome Sequencing, Whole Exome Sequencing and Targeted Sequencing & Resequencing Centrifuges

  • The targeted sequencing & resequencing segment dominated the market with a revenue share of over 72% in 2020.
  • Whole-Genome Sequencing (WGS) is projected to be the fastest-growing technology segment from 2021 to 2028 owing to the utility of this technology to differentiate and compare normal tissues from tumor tissues.

Based on the Workflow Insights, the market is segmented into Pre-Sequencing, Sequencing, and Data Analysis

  • Sequencing was the highest revenue-generating workflow segment in 2020 and accounted for a revenue share of over 54%.
  • NGS data analysis is anticipated to grow at a significant rate. Efforts taken by key market participants to develop advanced computational tools propels the segment growth.

Based on the Application Insights, the market is segmented into Screening, Companion Diagnostics, and Other Diagnostics

  • Screening accounted for the largest revenue share of over 79% as NGS is highly employed in cancer screening programs across the globe.
  • The companion diagnostics segment is projected to register the fastest CAGR from 2021 to 2028.

Based on the End-use Insights, the market is segmented into Hospitals, Clinics, and Laboratories

  • The laboratories segment led the market with a revenue share of over 65% in 2020.
  • Clinical laboratories are regulated by several governing bodies in the U.S. The CMSs regulate laboratory testing through Clinical Laboratory Improvement Amendments (CLIA).

Clinical Oncology Next Generation Sequencing Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The market is marked by the presence of several small- and mid-sized entities that have taken substantial efforts to strengthen their market presence.

Some prominent players in the global Clinical Oncology Next Generation Sequencing market include:

  • Illumina, Inc.
  • Thermo Fisher Scientific
  • Hoffmann-La Roche Ltd.
  • Agilent Technologies
  • Myriad Genetics
  • Beijing Genomics Institute (BGI)
  • Perkin Elmer
  • Foundation Medicine
  • Pacific Bioscience
  • Oxford Nanopore Technologies Ltd.
  • Paradigm Diagnostics
  • Caris Life Sciences
  • Partek, Inc.
  • Eurofins Scientific S.E.
  • Qiagen N.V.

Order a free sample PDF of the Clinical Oncology Next Generation Sequencing Market Intelligence Study, published by Grand View Research.
India Large Volume Parenteral Market Size, Challenges Analysis, Porter’s Five Forces Study and Forecast

India Large Volume Parenteral Industry Overview

The India large volume parenteral market size is expected to reach USD 134.0 million by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 6.0% from 2021 to 2028. Large Volume Parenteral (LVP) injections are used for either total or partial nutrition when oral intake is insufficient or challenging. Earlier, these formulations were used for patients undergoing surgical procedures or those admitted to a hospital.

Currently, they are used as substitutes for nutrition obtained from a healthy diet. However, the demand for LVPs has significantly increased due to the growing adoption of parenteral nutrition over enteral nutrition among COVID-19 patients for improving drug absorption, shorter hospital stays, and reduced risk of infections. This is anticipated to drive the market over the forecast period.

India Large Volume Parenteral Market Segmentation

Grand View Research has segmented the India large volume parenteral market on the basis of application, volume, and end use:

Based on the Application Insights, the market is segmented into Therapeutic Injections, Fluid Balance Injections, and Nutritious Injections

  • In 2020, the nutritious injections segment dominated the market for large volume parenteral and held the largest revenue share of 47.1%. This is attributed to the growing adoption of these products in delivering intravenous carbohydrates, amino acids, electrolytes, and minerals to meet adequate nutritional requirements when enteral nutrition mode is insufficient, not possible, or contraindicated.
  • The therapeutic injections application segment is anticipated to register the fastest growth rate during the forecast period owing to the increasing prevalence of life-threatening diseases and growing demand for safer, faster, and effective methods of drug administration in patients undergoing surgical procedures.

Based on the Volume Insights, the market is segmented into 100 ml, 250 ml, 500 ml, 1,000 ml, and 2,000 ml

  • By volume, the 500 ml segment dominated the India large volume parenteral market and accounted for the largest revenue share of 34.2% in 2020.
  • On the other hand, the 100 ml injectable segment is anticipated to register the fastest growth rate during the forecast period.

Based on the End-use Insights, the market is segmented into Hospitals and Other Healthcare Facilities and Home Care

  • The hospitals and other healthcare facilities segment dominated the market for large volume parenteral and accounted for the largest revenue share of 97.7% in 2020.
  • The homecare facilities segment is expected to register significant growth during the forecast period owing to the growing geriatric population and increasing consumer interests in the adoption of at-home care.

Key Companies Profile & Market Share Insights

Increasing investments in R&D, collaborations with other industry players, geographic expansions, and product differentiation are among the key strategies adopted by these companies for gaining a competitive edge in the market for large volume parenteral.

Some prominent players in the India Large Volume Parenteral market include:

  • Braun Melsungen AG
  • Fresenius Kabi AG
  • Baxter
  • Otsuka Pharmaceuticals
  • Sichuan Kelun
  • Albert David Ltd.
  • BML Parenteral Drugs

Order a free sample PDF of the India Large Volume Parenteral Market Intelligence Study, published by Grand View Research.
Cell Lysis & Disruption Market PEST Analysis, Distribution Channel Outlook and Regional Trend

Cell Lysis & Disruption Industry Overview

The global cell lysis & disruption market size is expected to reach USD 8.37 billion by 2028, registering a CAGR of 9.35% over the forecast period, according to a new report by Grand View Research, Inc. The anticipated revenue growth is attributed to accelerating the adoption of cell lysis and disruption methods during downstream processing to manufacture bio-therapeutics and other animal-based recombinant products. Technological developments in procedures involved in releasing cellular organelles have paved the way for the higher adoption of cell disruption methods.

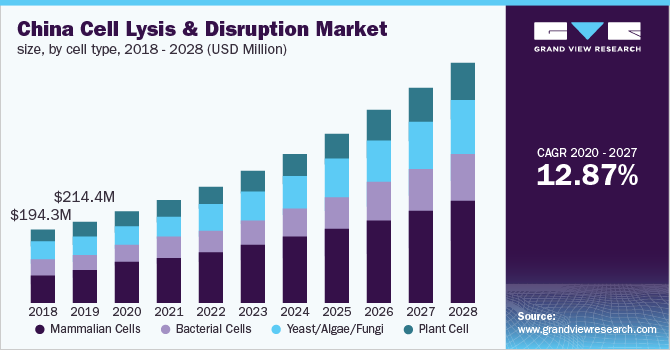
China cell lysis & disruption market size, by cell type, 2018 - 2028 (USD Million)

As retrieval and purification of biopharmaceuticals involve cell disruption, a rise in demand for biopharma would lead to the subsequent growth of the market. In addition, advancements in the field of proteomics, metabolomics, and personalized medicine are expected to fuel progressive changes in this sector. However, the high costs of equipment coupled with the dearth of skilled professionals are expected to restrain revenue generation to a certain extent. The restraint can be addressed as the government organizations are releasing substantial funds to support development in the biotechnology sector.

Cell Lysis & Disruption Market Segmentation

Grand View Research has segmented the global cell lysis & disruption market on the basis of technique, product, cell type, application, end use, and region:

Based on the Technique Insights, the market is segmented into Reagent-based and Physical Disruption

  • In 2020, the reagent-based method segment accounted for the largest revenue share of more than 65%.
  • Physical disruption methods were traditionally adopted by major players operating in this space for the extraction of intracellular contents. However, the adoption of these methods has relatively decreased currently owing to the requirement for expensive and cumbersome equipment.

Based on the Product Insights, the market is segmented into Instruments and Reagents & Consumables

  • The reagents and consumables segment accounted for the largest revenue share of more than 67% in 2020. Enzymes dominated the reagents and consumables segment and are expected to grow a significant CAGR during the forecast period.
  • Factors attributing to the estimated share include an application for the selective product release, and controlled lysis as these provide biological specificity to the process.

Based on the Cell Type Insights, the market is segmented into Mammalian cells Bacterial cells Yeast/Algae/Fungi, and Plant cells

  • The mammalian cells segment accounted for the major revenue share of more than 45% in 2020 and is expected to remain dominant throughout the forecast period.
  • The adoption of 3D mammalian culture systems stem cell and cancer research is anticipated to boost segment growth.

Based on the Application Insights, the market is segmented into Protein Isolation, Downstream Processing, Cell Organelle Isolation, and Nucleic Acid Isolation

  • The protein isolation segment accounted for the highest revenue share of more than 32% in 2020.
  • The rise in demand for industrial biotechnology products, such as hormones, antibodies, enzymes, antibiotics, and vaccines, has driven the market for downstream processing.

Based on the End-use Insights, the market is segmented into Academic & Research Institutes, Hospitals & Diagnostic Labs, Cell Banks, and Pharmaceutical & Biotechnology Companies

  • The pharmaceutical & biotechnology companies segment accounted for the largest market share of more than 35% in 2020.
  • The rise in demand for biopharmaceuticals is expected to significantly drive the segment growth over the years to come.

Cell Lysis & Disruption Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Most of the key companies focus on various business expansion strategies, such as novel product launches, acquisitions, and collaborations, to enhance their market position.

Some prominent players in the global Cell Lysis & Disruption market include:

  • Merck KGaA
  • Hoffmann-La Roche Ltd.
  • Qiagen NV
  • Becton Dickinson & Company (BD)
  • Danaher Corp.
  • Bio-Rad Laboratories, Inc.
  • Miltenyi Biotec GmbH
  • Claremont BioSolutions, LLC
  • Microfluidics International Corp.
  • Parr Instrument Company
  • BioVision, Inc.
  • Covaris, Inc.
  • Qsonica LLC

Order a free sample PDF of the Cell Lysis & Disruption Market Intelligence Study, published by Grand View Research.
Medical Simulation Market Application, Profit Margin Analysis and Business Environment Study

Medical Simulation Industry Overview

The global medical simulation market size is expected to reach a value of USD 5.48 billion by 2028. The market is expected to expand at a CAGR of 16.3% from 2021 to 2028. With recent technological advancements, the use of new medical devices and advanced procedures, such as enhanced mechanical ventilation devices, cardiac assist devices, and intra-cardiac echocardiography technology, is increasing; which drives the need for advanced training solutions, such as simulation, for customer training and internal product development. Certification and regulatory agencies are strictly recommending that physicians and clinicians be trained before the adoption of new, disruptive technologies. Although hands-on learning with real patients cannot be replaced, simulation training offers safe learning conditions. Students and medical residents making mistakes in this phase is an important part of the learning process, as in simulation training patients are not put at risk.

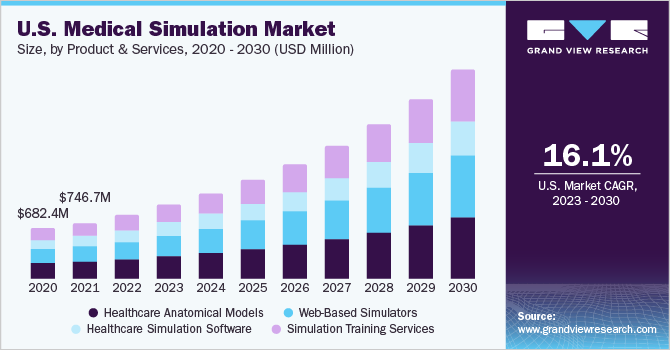
North America medical simulation market size, by product & services, 2018 - 2028 (USD Million)

Education Management Solutions, LLC- a company dealing in medical simulation learning management technology-released workflows that were COVID-19 contingency ready for healthcare education. CAE Healthcare responded to the pandemic by helping with a complimentary webinar, SCE, and outreach toolkit to assist educators. Such factors boosted the demand for medical simulation services during the pandemic.

Medical Simulation Market Segmentation

Grand View Research has segmented the global medical simulation market by products and services, technology, end use, and region:

Based on the Products & Services Insights, the market is segmented into Healthcare Anatomical Models, Web-Based Simulators, Healthcare Simulation Software, and Simulation Training Services

  • Healthcare anatomical model dominated the products and services segment of the overall market in 2020, as these simulators are proving to be beneficial in the manufacturing and research industry for conducting trials
  • The Healthcare anatomical models segment is further classified into task trainers, patient simulators, interventional/surgical simulators, ultrasound simulators, dental simulators, endovascular simulators, and eye simulators.

Based on Technology Insights, the market is segmented into Virtual Patient Simulation, 3D Printing, and Procedure Rehearsal Technology

  • The procedure rehearsal technology segment held the largest share of 40.6% in 2020. The rising number of medical errors leading to increasing demand for patient safety is expected to boost the demand for procedure rehearsal technology.
  • The virtual patient simulation segment is expected to expand at a lucrative CAGR of over 18.9% during the forecast period.

Based on the End-use Insights, the market is segmented into Academic Institutes, Hospitals, Military Organizations, and Research

  • The academic institutes' segment held the largest share of 30.6% in 2020. The academic research institutions segment is likely to witness persistent growth due to the presence of several academic research groups that are involved in the study of complex biological systems using computer models.
  • The hospitals segment is expected to witness the fastest growth rate of around 16.6% during the forecast period

Medical Simulation Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Vendors are investing in product launches, geographical expansions, collaborative agreements, and acquisitions, to sustain in the market. The market is expected to become highly competitive as many startups are seeking opportunities in this sector.

Some prominent players in the global Medical Simulation market include:

  • CAE (Canadian Aviation Electronics, Ltd)
  • Laerdal Medical
  • 3D Systems
  • Simulab Corporation
  • Limbs & Things Ltd
  • Simulaids
  • Kyoto Kagaku Co., Ltd
  • Gaumard Scientific Company
  • Mentice AB
  • Surgical Science Sweden AB

Order a free sample PDF of the Medical Simulation Market Intelligence Study, published by Grand View Research.
Connected Drug Delivery Devices Market Type Estimates, Revenue Drivers and Restraint Analysis

Connected Drug Delivery Devices Industry Overview

The global connected drug delivery devices market size is expected to reach USD 4.07 billion by 2028 registering a CAGR of 46.7%, according to a new report by Grand View Research, Inc. Factors contributing to the growth of this market include a rise in awareness about the adverse effects of non-adherence to medication and increased adoption of IoT, patient connectivity, and engagement. The Covid-19 pandemic has further accentuated the need for “contactless” services, thereby increasing the demand for connected drug delivery devices as well as providing lucrative growth opportunities in the coming years.

Connected drug delivery devices help physicians to monitor the compliance of patients to the therapy prescribed by them as well as to modify the treatment of the patient treatment as required. A growing number of initiatives to create awareness regarding the complexities caused by overdosage or underdosage of medicines is expected to promote the adoption of connected drug delivery devices.

Connected Drug Delivery Devices Market Segmentation

Grand View Research has segmented the global connected drug delivery devices market on the basis of product, end user, technology, and region:

Based on the Product Insights, the market is segmented into Connected Sensors and Integrated Connected Devices

  • The connected sensors segment dominated the market and accounted for the highest revenue share of over 68% in 2020.
  • The integrated connected devices segment is expected to register the fastest CAGR over the forecast period.

Based on the End-user Insights, the market is segmented into Healthcare Providers and Homecare

  • The healthcare providers segment accounted for the largest revenue share of more than 50.0% in 2020 owing to the increased cases of COPD, Cardiovascular Diseases (CVDs), diabetes, and other chronic diseases, which require proper maintenance of health records of the patient.
  • On the other hand, the homecare segment is estimated to register the fastest CAGR from 2021 to 2028 owing to the increasing product acceptance in homecare settings.

Based on Technology Insights, the market is segmented into Bluetooth, NFC, and Other Technologies

  • The Bluetooth technology segment accounted for the largest revenue share of 65.3% in 2020 owing to the high usage of the Bluetooth technology in drug delivery devices.
  • The NFC segment is expected to account for a considerable market share by 2028 as the NFC technology assists in communicating through the internet as well as mobile apps.
  • The others segment is expected to demonstrate the fastest CAGR of 57% from 2021 to 2028 as these are cellular technologies prove to be beneficial in transferring data in the connected drug delivery devices.

Connected Drug Delivery Devices Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

This was the company’s biggest acquisition in 2020 and strengthened its business operations in the U.K. Also, VetPartners Pty. Ltd. acquired National Veterinary Care Ltd. in April 2020, for USD 251.5 million. The two companies would combine their resources to improve veterinary health services across Australia and New Zealand. The initiatives like these are further contributing to the market growth over the forecast period.

Some prominent players in the global Connected Drug Delivery Devices market include:

  • Mars Inc.
  • Greencross Ltd.
  • National Veterinary Care Ltd.
  • Pets at Home Group PLC
  • CVS Group PLC
  • Ethos Veterinary Health
  • Addison Biological Laboratory
  • Armor Animal Health
  • PetIQ, LLC

Order a free sample PDF of the Connected Drug Delivery Devices Market Intelligence Study, published by Grand View Research.
Veterinary Services Market PESTEL Analysis and Key Growth Opportunities

Veterinary Services Industry Overview

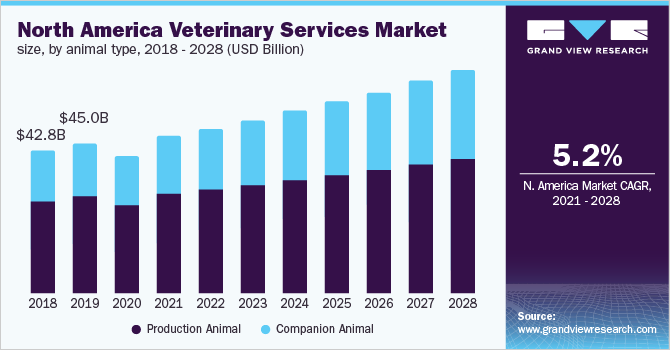
The global veterinary services market size is expected to reach USD 159.5 billion by 2028, registering a CAGR of 5.7% over the forecast years, according to a new report by Grand View Research, Inc. The market is predominantly driven by rising concerns regarding food security and safety thus encouraging the adoption of veterinary services to yield high-quality animal source foods. In addition, increasing pet adoption is a key contributing factor for the overall market growth.

North America veterinary services market size, by animal type, 2018 - 2028 (USD Billion)

The pet adoption rate spiked during the coronavirus pandemic as many individuals have been working from home. Many consider their pet as a family fellow. Thus, veterinary companies announced some new products, services, diagnostic tools, to cater to the demand. For example, in September 2020, Zoetis launched VetscanImagyst, a new diagnostic platform to detect intestinal parasites in pets.

Veterinary Services Market Segmentation

Grand View Research has segmented the global veterinary services market on the basis of animal type and region:

Based on the Animal Type Insights, the market is segmented into Production Animal, and Companion Animal

  • The production animal type segment dominated the market in 2020 with a revenue share of more than 61%. The substantial share captured by the segment can be presumed a consequence of high concern for food safety and sustainability by government healthcare organizations globally.
  • Cattle held the largest share of the production animals segment in 2020 owing to increased penetration of services, such as hoof care and artificial insemination
  • The companion animal type segment is projected to grow at the fastest CAGR from 2021 to 2028 owing to an unprecedented increase in pet adoption due to associated health benefits for humans, such as greater psychological stability, lower blood pressure and reduced anxiety attacks
  • Dogs accounted for the largest share amongst companion animals in 2020 owing to growing awareness amongst pet owners about pet hygiene, thus resulting in increased demand for grooming facilities
  • COVID-19 pandemic is encouraging pet owners, healthcare providers, and even payers to adopt telehealth in veterinary

Veterinary Services Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

This was the company’s biggest acquisition in 2020 and strengthened its business operations in the U.K. Also, VetPartners Pty. Ltd. acquired National Veterinary Care Ltd. in April 2020, for USD 251.5 million. The two companies would combine their resources to improve veterinary health services across Australia and New Zealand. The initiatives like these are further contributing to the market growth over the forecast period.

Some prominent players in the global Veterinary Services market include:

  • Mars Inc.
  • Greencross Ltd.
  • National Veterinary Care Ltd.
  • Pets at Home Group PLC
  • CVS Group PLC
  • Ethos Veterinary Health
  • Addison Biological Laboratory
  • Armor Animal Health
  • PetIQ, LLC

Order a free sample PDF of the Veterinary Services Market Intelligence Study, published by Grand View Research.
Surgical Retractors Market Revenue Opportunities and Gross Margin Analysis

Surgical Retractors Industry Overview

The global surgical retractors market size is estimated to reach USD 2.5 billion by 2028 registering a CAGR of 5.8%, according to a new report by Grand View Research, Inc. Increase in the number of surgical procedures owing to the growing prevalence of chronic diseases, rising adoption of minimally invasive surgeries and development of minimally invasive surgical retractors by major players are the factors expected to contribute to growth. The presence of a large number of players and their growing number of strategic initiatives to enhance their product portfolios is expected to boost growth.

Growing awareness about organ donation and an increasing number of transplantation procedures have a direct impact on the growth. Along with this, open heart surgeries, Kidney procedures, and trauma cases include heavy usage of surgical retractors. The introduction of advanced surgical retractors which include a minimal effort by surgeons is being preferred to reduce turnaround time. Increasing adoption of robotic surgery is also anticipated to play important role in market growth. The market started to normalize after the second wave of the COVID-19 pandemic. Increasing vaccination and resuming elective surgeries under strict guidelines are anticipated to increase the demand in the second semester of 2021.

Surgical Retractors Market Segmentation

Grand View Research has segmented the global surgical retractors market on the basis of type, product, application, end-use, and region:

Based on the Type Insights, the market is segmented into Handheld and Self-retaining

  • The handheld retractors segment dominated the market and accounted for the largest revenue share of 53.9% in 2020.
  • Self-retaining surgical retractors are expected to experience the fastest growth during the forecast period, owing primarily to their ease of use.

Based on the Product Insights, the market is segmented into Abdominal, Finger, Nerve, Orthopedic, Rectal, Thoracic, Ribbon, and Others

  • The orthopedic retractors dominated the market and accounted for the largest revenue share of 18.1% in 2020.
  • The abdominal retractor segment is expected to grow at the fastest rate of 5.2% over the forecast period.
  • Thoracic retractors are used in surgeries such as thoracotomy and sternotomy to provide visualization access to the surgical site.

Based on the Application Insights, the market is segmented into Neurosurgery, Wound closure, Reconstructive surgery, Cardiovascular, Orthopedic, Obstetrics and Gynecology (Ob/Gyn), and Others

  • The Obstetrics and Gynecology (Ob/Gyn) segment dominated the surgical retractors market and accounted for the largest revenue share of 24.3% in 2020.
  • The orthopedic segment is expected to witness a CAGR of 5.4% over the forecast period. The growing number of orthopedic patients is expected to boost segment growth.

Based on the End-use Insights, the market is segmented into Hospitals, Ambulatory Surgical Centers, and Clinics

  • The hospitals segment dominated the market and accounted for the largest revenue share of50.1% in 2020.
  • Ambulatory Surgical Centers (ASCs) are anticipated to register the highest growth rate over the forecast period. This can be attributed to lower out-of-pocket costs, better patient accessibility, and decreased facility costs.

Surgical Retractors Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The market is fragmented with high competition at global as well local level. Availability of raw materials and advanced manufacturing technology are some of the major factors deciding final product prices.

Some prominent players in the global Surgical Retractors market include:

  • Medtronic
  • Becton, Dickinson and Company (BD)A
  • Medical Devices Business Services, Inc.
  • Teleflex Incorporated
  • Medline Industries, Inc.
  • Braun Melsungen AG
  • Applied Medical Resources Corporation
  • Thompson Surgical
  • Innomed, Inc.
  • LiNA Medical ApS

Order a free sample PDF of the Surgical Retractors Market Intelligence Study, published by Grand View Research.
U.S. Intravenous Immunoglobulin Market Analysis Report by Type, Material, Application, Region and Segment Forecasts

U.S. Intravenous Immunoglobulin Industry Overview

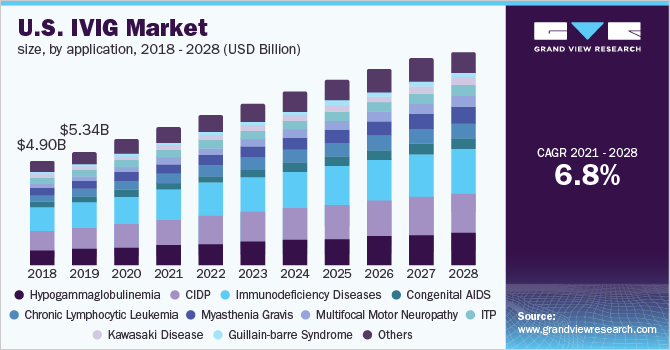
The U.S. intravenous immunoglobulin market size is expected to reach USD 10.24 billion by 2028, according to a new report by Grand View Research, Inc. It is expected to expand at a CAGR of 6.8% from 2021 to 2028. Robust pipeline, approval and launch of novel products, and increasing government initiatives are expected to be the major factors driving the market.

U.S. IVIG market size, by application, 2018 - 2028 (USD Billion)

Robust pipeline and increasing approvals and launches of novel products are anticipated to support the market growth over the forecast period. For instance, in April 2019, U.S.-based ADMA Biologics, Inc. received U.S. FDA approval for its new drug Asceniv. It is an IVIG drug indicated for the treatment of primary humoral immunodeficiency disease. Similarly, in December 2019, CSL Behring announced receiving orphan drug exclusivity for Hizentra from the U.S. FDA to treat Chronic Inflammatory Demyelinating Polyradiculoneuropathy (CIDP). In another instance, in February 2021, Biotest AG announced that it was the first in Germany to manufacture an investigational hyper immunoglobulin from plasma protein for the COVID-19 treatment.

U.S. Intravenous Immunoglobulin Market Segmentation

Grand View Research has segmented the U.S. intravenous immunoglobulin market on the basis of application and distribution channel:

Based on the Application Insights, the market is segmented into Hypogammaglobulinemia, CIDP, Immunodeficiency Diseases, Congenital AIDS, Chronic Lymphocytic Leukemia, Myasthenia Gravis, Multifocal Motor Neuropathy, ITP, Kawasaki Disease, Guillain-barre Syndrome, and Others

  • The immunodeficiency diseases segment dominated the market with a share of over 22.0% in 2020 owing to the existing patient base, coupled with the long-term therapy requirement associated with these diseases.
  • The CIDP segment is anticipated to grow at a lucrative rate during the forecast period due to its user-friendly application and minimally invasive technique as compared to other treatment options.
  • The multifocal motor neuropathy application segment is expected to register the fastest growth rate over the forecast period due to the high effectivity of IVIG in its treatment

Based on the Distribution Channel Insights, the market is segmented into Hospital Pharmacy, Specialty Pharmacy, and Others

  • Hospital pharmacy held the largest share of over 58.0% in 2020 owing to a large number of hospitals and the easy availability of products. Hospital pharmacies include both in-patient and out-patient hospital pharmacies.
  • The specialty pharmacy segment is expected to witness lucrative growth over the forecast period as specialty pharmacies facilitate easy treatment at home.

Key Companies Profile & Market Share Insights

Key players hold a major share in the market owing to their significant presence in the country. Emerging players are adopting organic growth strategies, such as novel drug development and product launches, to gain a significant market share.

Some prominent players in the U.S. Intravenous Immunoglobulin market include:

  • Biotest AG
  • Octapharma AG
  • LFB Biotechnologies S.A.S
  • China Biologics Products Holdings, Inc.
  • Grifols, S.A.
  • Kedrion Biopharma, Inc.
  • CSL Behring
  • McKesson Corporation
  • Takeda Pharmaceutical Company Limited
  • Bio Products Laboratory Ltd.
  • Pfizer, Inc.
  • ADMA Biologics, Inc.

Order a free sample PDF of the U.S. Intravenous Immunoglobulin Market Intelligence Study, published by Grand View Research.
In Situ Hybridization Market Growth Drivers, Vendor Landscape and Raw Material Outlook

In Situ Hybridization Industry Overview

The global in situ hybridization market size is expected to reach USD 2.6 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 8.9% from 2021 to 2028. The growing popularity of in-vitro diagnostics over conventional disease diagnostic methods has majorly driven the ISH market over the past years.

The market is gaining momentum in breast cancer with the FISH test. For instance, Roche offers a comprehensive ISH workflow solution with automated assay and digital pathology for breast cancer. Thus, increasing the scope of application is expected to drive the market to a major extend. In addition, technological advancements in instruments have fueled the market growth.

In Situ Hybridization Market Segmentation

Grand View Research has segmented the global in situ hybridization market based on technology type, probe, product, application, end-use, and region:

Based on Technology Insights, the market is segmented into Fluorescent In Situ Hybridization (FISH), and Chromogenic In Situ Hybridization (CISH).

  • FISH segment dominated the market for in situ hybridization and accounted for the largest revenue share of 53.9% in 2020. This can be attributed to the wide range of applications such as diagnosing congenital diseases including Edward's Syndrome and Down's Syndrome.
  • The CISH segment also captured a significant share of in situ hybridization over time as it is a cost-effective, reliable, and practical alternative for FISH.

Based on the Probe Type Insights, the market is segmented into DNA and RNA.

  • The DNA probe segment dominated the market for in situ hybridization and accounted for the largest revenue share of 51.1% in 2020.
  • However, the RNA probe showcased a better growth rate in the forecasted period, owing to the development of new nucleic acid-based diagnostic assays and tools for analyzing DNA and RNA molecules.

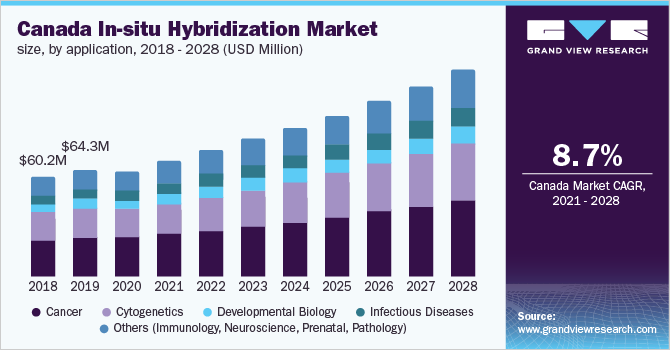
Canada in-situ hybridization market size, by application, 2018 - 2028 (USD Million)

Based on the Application Insights, the market is segmented into Cancer, Cytogenetics, Developmental Biology, Infectious Diseases, and Others

  • The cancer segment dominated the market for in situ hybridization and accounted for the largest revenue share of 36.4% in 2020.
  • The increase in the incidence rate of cancer cases is anticipated to drive the growth.

Based on Product Insights, the market is segmented into Instruments, Kits and Probes, Software, and Services.

  • The instruments segment dominated the market for in situ hybridization and accounted for the largest revenue share of 36.3% in 2020.
  • On the other hand, the services segment is anticipated to witness significant growth in the market for in situ hybridization.

Based on the End-use Insights, the market is segmented into Hospitals & Diagnostic Laboratories, Contract Research Organizations (CROs), Academic & Research Institutions, and Others

  • The hospitals and diagnostic laboratories segment dominated the market for in situ hybridization and accounted for the largest revenue share of 48.8% in 2020.
  • The ongoing pandemic can be the key driver for the laboratories as understanding the pathogen can offer a competitive advantage to the laboratories and assist to lead the industry.
  • Likewise, the Contract Research Organizations segment is growing at a faster pace, although the absolute value of revenue is less compared to the other segments.

In Situ Hybridization Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The in-situ hybridization market is competitive in nature and some of the key players accounted for the largest market share owing to their extensive product portfolios and geographic presence across the world.

Some prominent players in the global In Situ Hybridization market include:

  • Thermo Fisher Scientific
  • Leica Biosystems Nussloch GmbH
  • BIO VIEW
  • Agilent Technologies
  • Merck KGaA
  • PerkinElmer, Inc.
  • Bio-Rad Laboratories, Inc.
  • NeoGenomics Laboratories, Inc.
  • Advanced Cell Diagnostics, Inc.
  • Oxford Gene Technology

Order a free sample PDF of the In Situ Hybridization Market Intelligence Study, published by Grand View Research.
Restorative Dentistry Market Application Outlook and Research Report

Restorative Dentistry Industry Overview

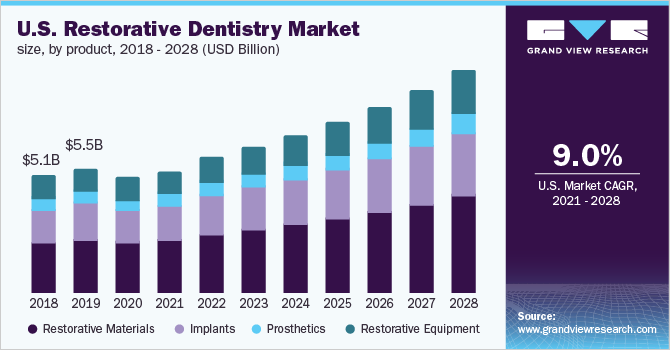
The global restorative dentistry market size is expected to reach USD 30.02 billion by 2028, according to the new report by Grand View Research, Inc. It is expected to expand at a CAGR of 8.6% from 2021 to 2028. The growth of the market is attributed to the improved quality of services provided in dentistry for the large patient pool. The transmission of COVID-19 by the generation of aerosol produced by dental handpieces is possible. To avoid this, the correct clinical protocols must be followed during the COVID-19 pandemic.

U.S. restorative dentistry market size, by product, 2018 - 2028 (USD Billion) 

The COVID-19 pandemic adversely affected the dental market in 2020. According to the WHO guidelines, viral infection mainly spreads through the eyes, nose, and mouth that makes it difficult for the dentist to operate on patients during such times. The routine cleaning, orthodontic procedures, preventive therapies, and oral examinations that do not involve pain management were postponed during the COVID-19 pandemic, thus negatively impacting the market.

Restorative Dentistry Market Segmentation

Grand View Research has segmented the global restorative dentistry market on the basis of product, end-use, and region:

Based on the Product Insights, the market is segmented into Restorative Materials, Implants, Prosthetics, and Restorative Equipment

  • The restorative materials segment accounted for the largest share of over 40.0% in 2020. The rapid growth of the segment is attributed to the increasing importance of aesthetics, which is resulting in cosmetic dentistry
  • In addition, a large number of tooth repairs is growing the adoption of biomaterials in dentistry and the widespread of these materials in fabricating dental restorations.
  • Furthermore, new technologies in the equipment have increased the precision and the quality of the restoration. These are the factors anticipated to propel the segment growth.

Based on the End-use Insights, the market is segmented into Dental Hospitals and Clinics, Dental Labs, and Research and Teaching Institutes

  • The dental hospitals and clinics segment accounted for the largest share of over 50.0% in 2020. The growth of the segment is attributed to the increasing number of hospitals and dental clinics in emerging regions, such as the Asia Pacific and Europe.
  • Oral health diseases are growing due to health conditions, such as diabetes and smoking, which are anticipated to fuel the market growth.

Restorative Dentistry Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Major market players are strengthening their service quality and expertise in carrying out complicated restorative dentistry procedures. There are very few companies manufacturing transplant devices and others offer topical products like gels, serums, and lotions.

Some prominent players in the global Restorative Dentistry market include:

  • 3M Company
  • Dentsply Sirona
  • Danaher Corporation
  • Septodont Holding
  • Ivoclar Vivadent AG
  • COLTENE Holding Ag
  • GC Corporation
  • Mitsui Chemicals, Inc.
  • Institut Straumann AG
  • Zimmer Biomet Holdings, Inc.

Order a free sample PDF of the Restorative Dentistry Market Intelligence Study, published by Grand View Research.
Minimally Invasive Thoracic Surgery Market Analysis By Size, Share, Product Type, Device, Vertical and Technology

Minimally Invasive Thoracic Surgery Industry Overview

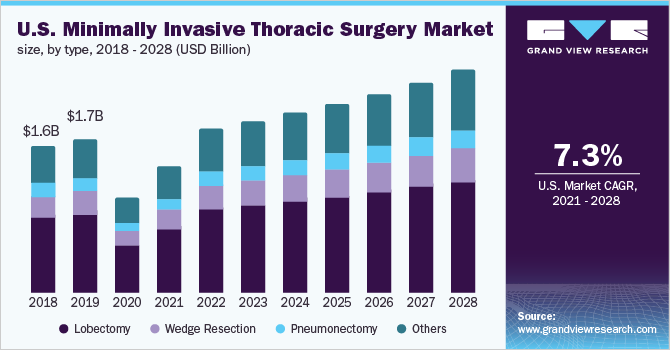
The global minimally invasive thoracic surgery market size is expected to reach USD 5.5 billion by 2028, according to a new report by Grand View Research, Inc. It is expected to expand at a CAGR of 8.7% from 2021 to 2028. Minimally Invasive Surgery (MIS) is gaining popularity owing to the reduced risk and trauma associated with these procedures as small incisions decrease post-operative pain that facilitates a speedy recovery.

U.S. minimally invasive thoracic surgery market size, by type, 2018 - 2028 (USD Billion)

Increasing research and development in this field is another high-impact rendering driver of the market. The introduction of novel technologies and devices by the market players has been observed in recent years. In the U.S., lung cancer is the second leading cancer form. According to the American Cancer Society, about 235,760 new lung cancer cases are estimated in 2021. A high number of smokers in the U.S. is a leading cause of cancer prevalence in the region.

Minimally Invasive Thoracic Surgery Market Segmentation

Grand View Research has segmented the global minimally invasive thoracic surgery market by type and region:

Based on the Type Insights, the market is segmented into Lobectomy, Wedge Resection, Pneumonectomy, and Others

  • Lobectomy captured the largest revenue share of over 50.0% in 2020 as it is the most commonly used operation for treating lung cancer.
  • There is a trend of increasing the adoption of minimally invasive techniques in other types of thoracic surgeries, such as sleeve lobectomy, segmentectomy, and thoracic sympathectomy. Technological advancements such as better imaging technology through improved optics for video thoracoscopes are fueling the growth
  • Around 524 patients opted for lobectomy, about 128 of them opted for pneumonectomy, and 209 patients had opted for wedge resection, segmentectomy, sleeve lobectomy, and laser excision.

Minimally Invasive Thoracic Surgery Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Continuous R&D activities by the industry players are significantly driving the market. In 2017, Intuitive Surgical announced da Vinci X, which is a new version of the technology that is a median between the da Vinci Si and the da Vinci Xi surgical system. Such initiatives by the company help in improving the penetration of the technology in the surgical market.

Some prominent players in the global Minimally Invasive Thoracic Surgery market include:

  • Medtronic plc
  • Cardio medical GmbH
  • Intuitive Surgical
  • Richard Wolf GmbH
  • Grena Ltd.
  • Dextera Surgical Inc.
  • Teleflex Incorporated
  • Medela Healthcare
  • LivaNovaplc
  • Sklar Surgical Instruments

Order a free sample PDF of the Minimally Invasive Thoracic Surgery Market Intelligence Study, published by Grand View Research.

Medical Flexible Packaging Market Overview By Product, Application, Regional Demand and Prominent Players

Medical Flexible Packaging Industry Overview

The global medical flexible packaging market size is expected to reach USD 26.3 billion by 2028, according to a new report by Grand View Research, Inc., expanding at a CAGR of 6.5% from 2021 to 2028. Increasing demand for pharmaceutical products in emerging economies as well as growing demand for drug delivery systems in developed countries are driving the growth of the market. The use of flexible packaging is increasing in the healthcare industry as the companies operating in the industry are opting for sustainable functions and materials, such as paper. Paper-based packaging is included in green packaging as it is highly recyclable and economical.

The flexible packaging is well suitable for single-time use. This is especially beneficial in the packaging of single-use products, which are becoming increasingly popular to avoid the risk of cross-contamination. The products can be sterilized along with the packaging, which has reduced the chance of contamination while manufacturing the products.

Medical Flexible Packaging Market Segmentation

Grand View Research has segmented the global medical flexible packaging market on the basis of material, product, end-use, and region:

Based on the Material Insights, the market is segmented into Plastics, Paper, Aluminum, and Bioplastics

  • The plastics segment led the market and accounted for more than 74% share of the global revenue in 2020. Plastics offer a wide variety of options and higher tensile strength than their metal counterparts, which is expected to drive the segment growth over the forecast period.
  • Paper material segment is estimated to register the fastest CAGR from 2021 to 2028. Innovations in the paper industry and the development of eco-friendly paper are expected to drive the segment over the forecast period.

Based on the Product Insights, the market is segmented into Seals, High Barrier Films, Wraps, Pouches & Bags, Lids & Labels, and Others

  • The pouches & bags segment led the market and accounted for more than 35% share of the global revenue in 2020. Pouches & bags are used for packaging a wide range of medical products.
  • The high-barrier films segment is estimated to register the fastest CAGR from 2021 to 2028.

Based on the End-use Insights, the market is segmented into Pharmaceutical Manufacturing, Medical Device Manufacturing, Implant Manufacturing, Contract Packaging, and Clinics

  • The pharmaceutical manufacturing segment accounted for the largest revenue share of more than 29% in 2020.
  • Medical device manufacturing is the second-largest end-use segment as the product demand in this segment has spiked especially after the pandemic.
  • Contract packaging is projected to be the fastest-growing end-use segment from 2021 to 2028.

Medical Flexible Packaging Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Central & South America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Major companies exhibit strong control over the entire value chain. Companies in the market have been exploring data services and other allied businesses to attract more customers. The diversification strategy aimed at providing data services along with the current portfolio of products is expected to increase the market competition.

Some prominent players in the global Medical Flexible Packaging market include:

  • Bemis Company, Inc.
  • WestRock, Aptar, Inc.
  • Dätwyler Holding, Inc.
  • Becton, Dickinson & Company
  • Berry Global
  • Catalent Pharma Solutions
  • Coveris S.A.
  • Winpak Ltd.
  • Sealed Air
  • Amcor
  • Mondi
  • Huhtamäki Oyj
  • CCL Industries, Inc.
  • Gerresheimer

Order a free sample PDF of the Medical Flexible Packaging Market Intelligence Study, published by Grand View Research.

Surgical Drainage Devices Market Business Drivers, Top Companies and Competitive Analysis

Surgical Drainage Devices Industry Overview

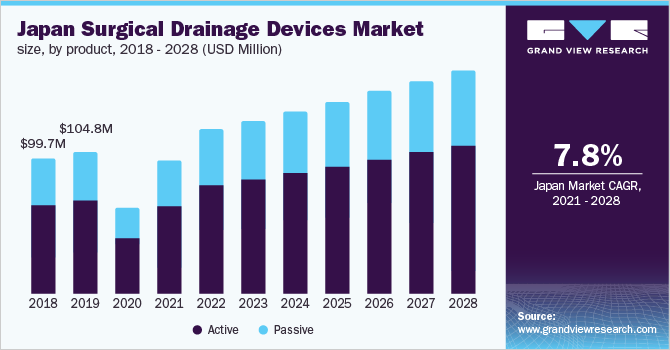
The global surgical drainage devices market size is anticipated to reach USD 2.57 billion by 2028, expanding at a CAGR of 5.6% over the forecast period, according to a new report by Grand View Research, Inc. The growth of this market is catapulted by the increasing incidence of chronic diseases, the need to curb healthcare expenditure, and the additional benefits associated with surgical drain devices. The majority of the time, these devices are used for the prevention of fluid accumulation and in post-surgical treatment & care.

Japan surgical drainage devices market size, by product, 2018 - 2028 (USD Million)

With the escalating number of diseases that require surgical intervention, these devices are now being used in hospitals, clinics, and ambulatory surgical centers. Active surgical drain devices make use of negative pressure or vacuum to remove fluid buildup and are preferred over conventional passive drain devices as they help in healing the wound quickly.

Surgical Drainage Devices Market Segmentation

Grand View Research has segmented the global surgical drainage devices market on the basis of product, application, end-use, and region:

Based on the Product Insights, the market is segmented into Active and Passive

  • In 2020, the active surgical drainage devices accounted for the largest share of over 75.0%. These devices evacuate fluid and prevent the buildup of air at the surgical site with the use of suction, usually vacuum or wall suction.
  • The majority of the time, active surgical drainage devices make use of negative pressure therapy to drain fluid from the surgical site.

Based on the Application Insights, the market is segmented into Thoracic and Cardiovascular Surgeries, Neurosurgical Procedures, Abdominal Surgery, Orthopedics, and Others

  • In 2020, thoracic and cardiovascular surgeries accounted for the largest share of over 25.0% owing to an increase in the prevalence of cardiovascular diseases.
  • Drains are used in orthopedic surgeries for the removal of any sort of abscess and to reduce the risk of contamination by bacterial growth in the fluid buildup. The rise in musculoskeletal diseases as well as orthopedic trauma, globally, can be attributed to the increase in the number of surgeries being performed.

Based on the End-use Insights, the market is segmented into Hospitals, Ambulatory Surgical Centers, and Clinics

  • Hospitals held the largest share of over 45.0% in 2020 due to a large number of surgeries being conducted. A global increase in the number of ambulatory surgical centers is another crucial factor contributing to the market growth.
  • Specialty clinics have witnessed immense growth as they offer customized services according to the requirements of patients. Therefore, the growing usage of surgical drainage devices has allowed the growth of this segment.

Surgical Drainage Devices Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The market is highly fragmented with the presence of many large-, small-, and medium-sized players. These leading players face competition from local players. New product launches, mergers and acquisitions, partnerships, and collaborations are the key strategies adopted by the leading companies for sustainable sector growth.

Some prominent players in the global Surgical Drainage Devices market include:

  • Acelity
  • Teleflex Incorporated
  • Cardinal Health
  • Medtronic
  • Cook Medical
  • Stryker

Order a free sample PDF of the Surgical Drainage Devices Market Intelligence Study, published by Grand View Research.

Gene Expression Market Summary, Key Buying Criteria, Revenue Growth Prospects and PESTEL Analysis

Gene Expression Industry Overview

The global gene expression market size is anticipated to reach USD 19.4 billion by 2028 registering a CAGR of 9.96% from 2021 to 2028, according to a new report by Grand View Research, Inc. Rise in investments for the development of alternative drug discovery approaches coupled with an increase in research activities for genetic studies is expected to drive the global market.

A rise in awareness about the potential application of genetic studies has led to an increase in investments for the development and launch of novel products. For instance, in August 2020, Lexogen GmbH launched the QuantSeq-Pool Sample-Barcoded 3’ mRNA-Seq Library Prep Kit to expedite multiplexing capacities during gene expression profiling. The company’s new QuantSeq-Pool kit also facilitates the sequencing of up to 36,864 RNA samples in parallel, thereby reducing cost and time.

Gene Expression Market Segmentation

Grand View Research has segmented the global gene expression market on the basis of process, product, capacity, technique, application, and region:

Based on the Process Insights, the market is segmented into Sample Collection, Purification, cDNA Synthesis & Conversion, PCR Analysis, and Data Analysis & Interpretation

  • The cDNA synthesis & conversion process segment led the market with a revenue share of 27.06% in 2020 owing to the availability of a wide range of kits for cDNA synthesis to match the research needs pertaining to optimal reaction temperature, the number of reactions, and sample size.
  • The data analysis & interpretation segment is expected to register the fastest CAGR over the forecast period.

Based on the Product Insights, the market is segmented into Kits & Reagents, DNA Chip/Microarray, and Others

  • The kits & reagents product segment dominated the global gene expression market in 2020 with a revenue share of over 74%.
  • The DNA chip/microarray segment is estimated to register the fastest CAGR from 2021 to 2028 owing to the rise in utilization of DNA microarrays for analysis of gene exp.

Based on the Capacity Insights, the market is segmented into Low- to Mid-Plex and High-Plex

  • The High-Plex capacity segment accounted for the largest revenue share of 64.2% in 2020 and is projected to retain the dominant position by growing at the fastest CAGR over the forecast period.
  • A rise in the adoption of gene exp. analysis for multiple genomic studies is a key factor driving the segment growth.

Based on the Technique Insights, the market is segmented into RNA Exp., Promoter Analysis, and Protein Exp. & Posttranslational Modification Analysis

  • DNA microarrays and PCR techniques are the major contributors to the large share of this segment as these techniques have a significant adoption rate and have helped researchers and biologists to study expressions of various genes and microorganisms.
  • The RNA exp. technique segment dominated the market with a revenue share of over 41% in 2020.

Based on the Application Insights, the market is segmented into Drug Discovery & Development, Clinical Diagnostics, Biotechnology & Microbiology, and Others

  • The drug discovery & development segment accounted for the largest revenue share of over 41% in 2020.
  • A rise in demand for early and accurate diagnostic tests for complex disorders is expected to drive the clinical diagnostics application segment with the fastest CAGR from 2021 to 2028.

Gene Expression Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Most of the market leaders follow organic growth strategies to reinforce their market presence. For instance, in September 2020, 10x Genomics commercialized its Chromium Single Cell Multiome ATAC + Gene Expression solutions. In March 2020, Thermo Fisher Scientific, Inc. launched the PowerTrack SYBR Green PCR Master Mix for real-time PCR workflow to amplify targets for precise gene exp. analysis.

Some prominent players in the global Gene Expression market include:

  • QIAGEN
  • Quest Diagnostics, Inc.
  • Hoffmann-La Roche Ltd.
  • Illumina, Inc.
  • PerkinElmer, Inc.
  • Bio-Rad Laboratories
  • Thermo Fisher Scientific, Inc.
  • Agilent Technologies
  • GE Healthcare
  • Promega Corp.
  • Luminex Corp.
  • Takara Bio, Inc.

Order a free sample PDF of the Gene Expression Market Intelligence Study, published by Grand View Research.

Presence of Strong Pipeline Drugs to Bode Well for Central Nervous System Therapeutic Market Growth by 2028

Central Nervous System Therapeutic Industry Overview

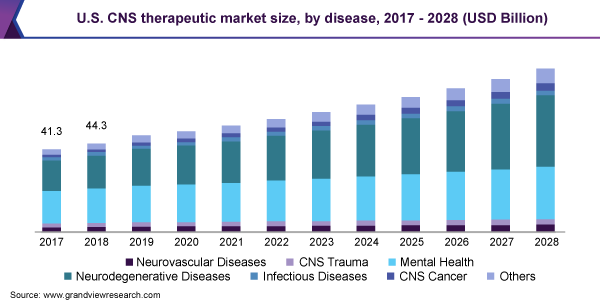
The global central nervous system therapeutic market size is expected to reach USD 205.0 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 7.4% from 2021 to 2028. High unmet medical needs and government initiatives to reduce the disease burden are driving the market for central nervous system (CNS) therapeutic over the forecast period. According to WHO, the global economy loses due to depression and anxiety is more than USD 1 trillion per year and rising patient base of mental health globally is expected to increase the economy loses by USD 16 trillion in 2030.

U.S. CNS therapeutic market size, by disease, 2017 - 2028 (USD Billion)

The market holds strong future growth opportunities and major players are adopting different marketing strategies such as new product development, collaborations, geographic expansion, mergers and acquisitions, and new product approval, to strengthen their positions. In February 2020, Biogen announced the investment in Sangamo’s zinc finger platform to develop therapies for Alzheimer’s disease and other neurological diseases. Similarly, the company has an agreement with Ionis Pharmaceutical for the development of drug candidates applicable across a wide range of neurological diseases.

Rising approval of generic products owing to patent expiration of key products, such as Copaxone and Invega, has led to an increase in treatment rate, especially in low- and middle-income countries. For instance, in 2018, the FDA approved two new generic forms of Copaxone, which is further expected to increase competitive rivalry in the market for central nervous system therapeutic. Regulatory guidelines and critical clinical trials are encouraging the entry of new products into the market for central nervous system therapeutic. These drugs are monitored for their efficacy, dosage, formulation, and aftereffects. For instance, the U.S. FDA has designated CNS Pharmaceuticals’ berubicin as an orphan drug for the treatment of patients with malignant gliomas.

Central Nervous System Therapeutic Market Segmentation

Grand View Research has segmented the global central nervous system therapeutic market on the basis of disease and region:

Based on the Disease Insights, the market is segmented into Neurovascular Diseases, CNS Trauma, Mental Health, Neurodegenerative Diseases, Infectious Diseases, CNS Cancer, and Others.

  • The neurodegenerative disease segment dominated the market for central nervous system therapeutic and accounted for the largest revenue share of 39.4% in 2020. The segment is expected to continue its dominance over the forecast period.
  • Mental health was estimated to be the second-largest segment in the central nervous system therapeutic market. High patient base of anxiety disorder and epilepsy are the major growth contributors.
  • CNS cancer is expected to be the fastest-growing segment over the forecast period and is projected to exhibit a CAGR of 10.1%. Its high growth rate can be attributed to increasing prevalence and mortality and growing demand for treatment.

Central Nervous System Therapeutic Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

Large pharmaceutical companies are highly investing in the development of novel therapies to treat central nervous system diseases. In February 2020, Biogen announced USD 2.72 billion deal with Sangamo Therapeutics to develop gene regulation therapies to treat Alzheimer’s disease.

Some prominent players in the global Central Nervous System Therapeutic market include:

  • Biogen
  • Otsuka Pharmaceutical Co., Ltd.
  • Eli Lilly and Company
  • Merck & Co.
  • Astra Zeneca
  • Shire PLC
  • Novartis AG
  • Teva Pharmaceutical Industries Ltd.
  • Johnson & Johnson Services, Inc.
  • Pfizer, Inc.

Order a free sample PDF of the Central Nervous System Therapeutic Market Intelligence Study, published by Grand View Research.

Increasing Outsourcing of R&D Activities to drive Oncology Based In-vivo CRO Market by 2028

Oncology Based In-vivo CRO Industry Overview

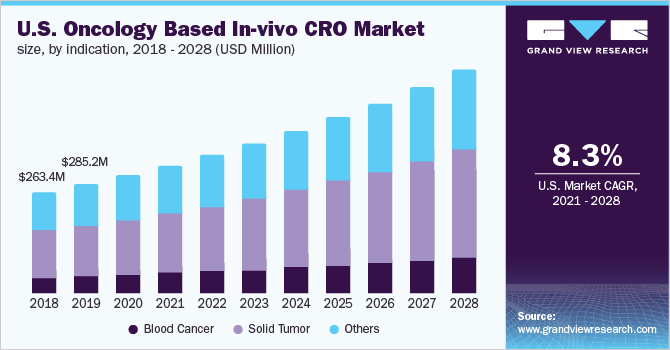
The global oncology based in-vivo CRO market is expected to reach USD 1.9 billion by 2028, according to a new study by Grand View Research, Inc. It is expected to expand at a CAGR of 8.2% from 2021 to 2028. The use of Contract Research Organization (CRO) oncology services helps the manufacturers/sponsors to provide complete attention on the production capacity and at enhancing their in-house processes.

U.S. oncology based in-vivo CRO market size, by indication, 2018 - 2028 (USD Million)

Furthermore, the pressure from the increasing competition due to patent expirations, rapid growth of generics, and introduction of biosimilar equivalents are propelling the pharmaceutical companies to take the aid of such organizations. Hence, it can be predicted that the oncology based in-vivo CRO market may witness lucrative growth over the forecast period.

Oncology Based In-vivo CRO Market Segmentation

Grand View Research has segmented the global oncology based in-vivo CRO market on the basis of indication, and region:

Based on the Indication Insights, the market is segmented into Blood cancer, Solid tumors, and Others.

  • The solid tumors dominated the market for oncology based in-vivo CRO and accounted for the largest revenue share of 46.5% in 2020.
  • The factors responsible for higher research in the field of solid tumors are the presence of over 800 new molecules that are under pipeline by large pharmaceutical companies, availability of grants from institutes such as NIH and NCI, and the existing gap between demand and supply of therapeutic treatments for solid cancer.

Oncology Based In-vivo CRO Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The augmenting rate at which outsourcing of activities is growing within the healthcare industry results in the entry of various new players coupled with collaborative efforts by existing players is expected to be witnessed over the forecast period. For instance, in January 2020, Charles River Laboratories collaborated with Takeda Pharmaceutical Company to identify & develop preclinical candidates and acquired HemaCare Corporation for USD 380.0 million. HemaCare Corporation is likely to become a part of the company’s research models and services segment.

Some prominent players in the global Oncology Based In-vivo CRO market include:

  • Charles River Laboratory
  • ICON Plc
  • Covance
  • Eurofins Scientific
  • Taconic Biosciences
  • Crown Bioscience
  • Toxikon, Inc.
  • WuXi AppTec
  • EVOTEC
  • The Jackson Laboratory

Order a free sample PDF of the Oncology Based In-vivo CRO Market Intelligence Study, published by Grand View Research.

Demand For Ostomy Care And Accessories Is Anticipated To Upsurge Owing To the Rise in Geriatric Population

Ostomy Care And Accessories Industry Overview

The global ostomy care and accessories market size is anticipated to reach USD 4.8 billion by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 5.1% from 2021 to 2028. The increasing prevalence of bladder and colorectal cancer coupled with the rise in the geriatric population is a key contributor to market growth.

The high prevalence of colorectal cancer and urinary bladder cancer has increased the demand for ostomy care products globally. For instance, as per the estimates of the American Cancer Society, in the U.S., in 2021, around 149,500 people are expected to be diagnosed with colorectal cancer, and approximately 52,980 people are expected to die due to colorectal cancer. This is expected to drive the market over the forecast period.

Ostomy Care And Accessories Market Segmentation

Grand View Research has segmented the global ostomy care and accessories market on the basis of product, application, end-user, and region:

Based on the Product Insights, the market is segmented into Bags and Accessories.

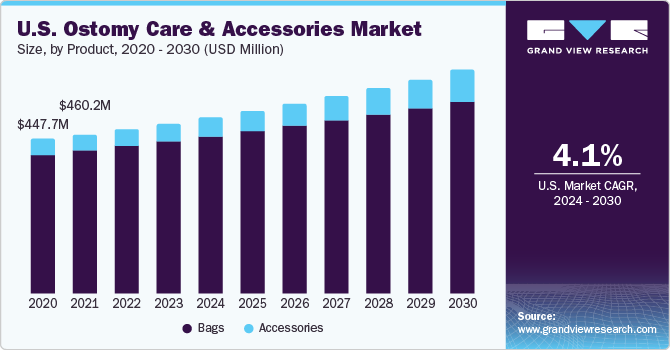
  • In 2020, the bags segment dominated the market for ostomy care and accessories and accounted for the largest revenue share of around 85.0%. Ostomy bags are further sub-segmented into one-piece and two-piece bags. Ostomy bags are medical devices used to collect stool or urine.
  • The accessories segment is expected to witness the highest CAGR of 6.6% from 2021 to 2028. It includes seals/barrier rings, pouch closures, pouch covers, stoma caps, and others. They help to prevent leakage, odor, and skin rashes

U.S. ostomy care & accessories market size, by product, 2018 - 2028 (USD Million)

Based on the Application Insights, the market is segmented into Colostomy, Ileostomy, and Urostomy.

  • In 2020, the colostomy segment dominated the market for ostomy care and accessories and accounted for the largest revenue share of 45.9% owing to an increase in the geriatric population and the high prevalence of colon cancer as well as associated colostomy procedures.
  • The ileostomy segment is expected to witness the highest CAGR of 5.6% from 2021 to 2028 owing to a high prevalence of Inflammatory Bowel Diseases (IBDs), such as Crohn’s disease and ulcerative colitis.

Based on the End-use Insights, the market is segmented into Home Care Settings, Hospitals, and Others.

  • The home care settings segment dominated the market and held the largest revenue share of 45.4% in 2020 and is expected to witness the highest CAGR over the forecast period. The rise in demand for home healthcare services is expected to drive this segment growth.
  • Growing preference for home care and availability of trained nurses in developed as well as emerging countries are expected to drive the segment over the forecast period.

Ostomy Care And Accessories Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The competitors in the market for ostomy care and accessories are either adding more features to their existing products or launching new product lines to gain a larger share of the market. Key market players are constantly incorporating technologies that can meet the specific requirements of patients.

Some prominent players in the global Ostomy Care And Accessories market include:

  • Coloplast Corp.
  • Braun Melsungen AG
  • Hollister Incorporated
  • ConvaTec Group Plc
  • Welland Medical Ltd.
  • Salts Healthcare Ltd.

Order a free sample PDF of the Ostomy Care And Accessories Market Intelligence Study, published by Grand View Research.

Rising Medical Tourism for Cosmetic Surgeries to make way for Smoke Evacuation Systems Market Growth by 2028

Smoke Evacuation Systems Industry Overview

The global smoke evacuation systems market size is expected to reach USD 285.5 million by 2028, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 7.4% from 2021 to 2028. Factors contributing to the growth of this market include an increase in medical tourism for cosmetic surgeries, electrosurgery procedures, and increased product availability.

Currently, elective and endoscopic procedures are delayed due to the outbreak of COVID-19 to reduce the risk of transmission to other patients with chronic conditions. According to the Society of American Gastrointestinal and Endoscopic Surgeons, it is recommended to use electrosurgery pencils with attached smoke evacuators instead of monopolar electrosurgical and advanced bipolar devices and ultrasonic dissectors. Moreover, high-flow vacuum sources or filtration units are recommended during laparoscopic procedures. The market is thus anticipated to experience gradual growth post-COVID-19 revival.

Smoke Evacuation Systems Market Segmentation

Grand View Research has segmented the global smoke evacuation system market on the basis of product, application, end-use, and region:

Based on the Product Insights, the market is segmented into Smoke Evacuating Systems, Smoke Evacuation Filters, Smoke Evacuation Pencils & Wands, Smoke-Evac Fusion Products (Shrouds), Smoke Evacuation Tubings and Accessories.

  • The smoke evacuating systems segment dominated the market and accounted for the largest revenue share of more than 39.0% in 2020. The smoke evacuation system detects smoke and activates fans for channeling the smoke away from occupied areas in the facility.
  • The smoke evacuation filters segment is expected to hold the second-largest market share owing to their applications in cauterizing vessels and vaporizing blood, tissues, and fluid created as smoke, a byproduct of laser surgeries and electrosurgeries.

Based on the Application Insights, the market is segmented into Laparoscopic Surgeries, Orthopedic, Medical Aesthetic Surgeries, and Others.

  • The laparoscopic surgeries segment dominated the smoke evacuation system market and accounted for the largest revenue share of around 37.0% in 2020. A rising number of laparoscopic surgeries is anticipated to fuel the market growth.
  • The medical aesthetic surgeries segment is expected to grow at the fastest growth rate of 7.8% owing to the increasing number of aesthetic surgeries.

Based on the End-use Insights, the market is segmented into Hospitals, Ambulatory Surgical Centers, Cosmetic Surgery Centers, Dental Clinics, and Veterinary Healthcare Providers.

  • The hospitals' segment dominated the market and accounted for the largest revenue share of 42.9% in 2020. This segment is expected to hold the largest market share during the forecast period owing to the high number of surgeries being performed such as cosmetic and orthopedic surgeries.
  • Cosmetic surgery centers segment is estimated to register the fastest CAGR of around 7.7% owing to the rise in the number of cosmetic laser surgeries, which produce smoke.

Smoke Evacuation Systems Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Latin America
  • Middle East & Africa (MEA)

Key Companies Profile & Market Share Insights

The market leaders are involved in acquisitions, strategic collaborations, and new product launches to withstand the competition. Major market players are investing in acquisitions and launching new products to enhance their position in the market. For instance, in May 2020, KLS Martin Group acquired major business operations of Stuckenbrock Medizintechnik. This strategy focused on expanding the OEM operations of the company.

Some prominent players in the global Smoke Evacuation Systems market include:

  • Medtronic
  • CONMED Corporation
  • Zimmer Biomet
  • Stryker
  • Ethicon Inc.
  • Erbe Elektromedizin GmbH
  • Symmetry Surgical Inc.
  • Pall Corporation
  • KLS Martin Group
  • Olympus Corporation

Order a free sample PDF of the Smoke Evacuation Systems Market Intelligence Study, published by Grand View Research.

$33.4 Billion Today, $328 Billion by 2033: Inside the Edge Computing Market's Great Sprint

Enterprises are moving compute closer to where data is created. Factories, hospitals, retail stores, telecom towers, and vehicles all produc...