Beyond the Bin: Innovations Driving the Garbage Bags Market Forward

Garbage Bags Market Growth & Trends

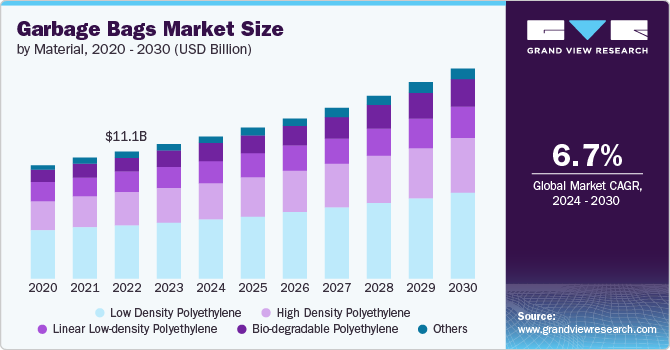
The global Garbage Bags Market is on a significant upward trajectory, projected to hit USD 18.27 billion by 2030. This growth, at a compound annual growth rate (CAGR) of 6.7% from 2024 to 2030, is detailed in a new report by Grand View Research, Inc. Several key factors are fueling this expansion.

Driving Forces behind Market Growth

A primary catalyst for the increasing demand for garbage bags is the surging global population combined with rapid urbanization. The world's population is expected to reach 9.7 billion by 2050, with the majority residing in urban centers. This shift leads to higher per capita waste generation due to evolving consumption patterns and more disposable lifestyles. As cities expand, efficient waste management, which includes the widespread use of garbage bags, becomes crucial.

Environmental Awareness and Regulations

Heightened environmental awareness and stricter regulatory measures worldwide are compelling consumers, businesses, and governments to adopt more sustainable waste management practices. The pressing issue of plastic pollution is driving a shift towards eco-friendly alternatives across various industries, including packaging. Consequently, there's a growing preference for biodegradable or recyclable trash bags among environmentally conscious consumers. Regulatory frameworks designed to reduce single-use plastics and promote recycling further accelerate the adoption of sustainable garbage bag solutions.

Material Science Innovations

Advancements in material science are revolutionizing the market by enhancing product performance, durability, and sustainability. While traditional garbage bags were typically made from polyethylene (PE) variants like HDPE or LDPE, innovations now allow for the development of garbage bags using biodegradable polymers derived from renewable resources or recycled materials. These advanced materials not only meet regulatory requirements but also cater to consumer demand for environmentally friendly products that minimize environmental impact.
Regional Market Dynamics

The demand for garbage bags varies considerably by region, influenced by economic development, cultural practices, regulatory frameworks, and environmental awareness.

  • North America sees strong demand for high-quality and sustainable garbage bags, driven by stringent waste management regulations and a robust consumer market.
  • Europe emphasizes sustainability and recycling initiatives, fostering a preference for eco-friendly trash bag options.
  • In contrast, rapid urbanization and industrialization in Asia-Pacific countries are boosting demand for efficient waste management solutions, including durable and cost-effective garbage bags.

Key Market Players and Product Innovation

Major players in the garbage bags market, such as Glad, Hefty, and Reynolds Consumer Products, are continuously innovating their product lines to meet evolving consumer preferences and regulatory standards. Innovations include scented garbage bags for odor control, tear-resistant materials for durability, and eco-friendly options made from recycled or biodegradable materials. Product differentiation through advanced features and sustainability credentials enables brands to capture market share and meet the growing demand for high-performance trash bag solutions.

Curious about the Garbage Bags Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

Garbage Bags Market Report Highlights

  • Based on material, low density polyethylene material dominated the market due to its flexibility, durability, and resistance to tearing and puncturing, making it ideal for various uses.

  • Household end use held a largest market share due to the growing urbanization and smaller living spaces drive the need for efficient waste management solutions.

  • The Asia Pacific market held the largest revenue share and is expected to retain its dominance over the forecast period. The increasing environmental awareness and regulatory initiatives are driving the adoption of eco-friendly and biodegradable garbage bags in the region.

Garbage Bags Market Segmentation

Grand View Research has segmented the global garbage bags market on the basis of material, size, end-use, distribution channel, and region:

Garbage Bags Material Outlook (Revenue, USD Billion, 2018 - 2030)

  • Low Density Polyethylene
  • High Density Polyethylene
  • Linear Low-density Polyethylene
  • Bio-degradable Polyethylene
  • Others

Garbage Bags Size Outlook (Revenue, USD Billion, 2018 - 2030)

  • 3-13 Gallons
  • 14-50 Gallons
  • Above 50 Gallons

Garbage Bags End-use Channel Outlook (Revenue, USD Billion, 2018 - 2030)

  • Household
  • Commercial
    • Hospitality & Food Service
    • Institutional
    • Retail
    • Others

Garbage Bags Distribution Channel Outlook (Revenue, USD Billion, 2018 - 2030)

  • B2B
  • B2C
    • Hypermarkets/ Supermarkets
    • Convenience Stores
    • Departmental Stores
    • Online
    • Others

Garbage Bags Regional Outlook (Revenue, USD Billion, 2018 - 2030)

  • North America
    • U.S.
    • Canada
    • Mexico
  • Europe
    • UK
    • Germany
    • France
    • Italy
    • Spain
  • Asia Pacific
    • China
    • India
    • Japan
    • Australia & New Zealand
    • South Korea
  • Central & South America
    • Brazil
  • Middle East & Africa (MEA)
    • South Africa

Download your FREE sample PDF copy of the Garbage Bags Market today and explore key data and trends.
U.S. Digestive Health Products Market: Innovations in Digestive Supplements

U.S. Digestive Health Products Market Growth & Trends

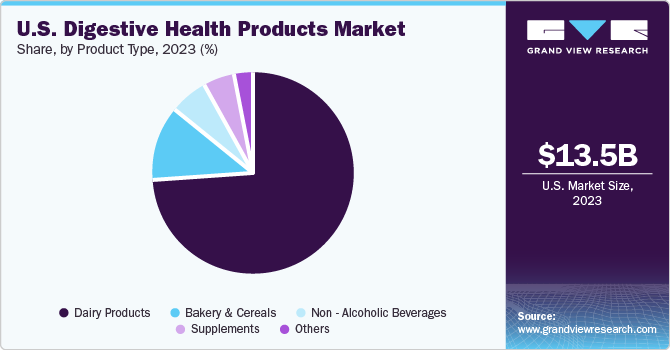
The U.S. Digestive Health Products Market was valued at an estimated USD 13.53 billion in 2023 and is anticipated to expand at a Compound Annual Growth Rate (CAGR) of 8.3% from 2024 to 2030. This growth is primarily fueled by a heightened focus on overall health and the increasing demand for nutritional and fortifying food additives. Key factors contributing to this market expansion include the strong presence of major industry players within the country, government support for new product development, and ongoing technological advancements in the fields of probiotics and prebiotics.

In 2023, the U.S. digestive health products market accounted for a significant 26.21% share of the global digestive health products market. The market's growth is further attributed to the rising consumption of protein-enriched functional foods and dietary supplements in the region. The strong manufacturing presence of key global market players in the U.S., coupled with an increasing number of new protein source start-ups, will continue to drive the demand for functional foods. These functional foods, which contain beneficial phytochemicals, are advantageous for both human and animal health. Consequently, the rising demand for nutraceutical products is expected to positively impact functional foods such as digestive health products, which are a subset of the broader nutraceuticals and functional foods industry.

A significant and growing trend in the U.S. is the utilization of digestive health products, particularly probiotics, for the treatment of mental illness, a factor actively driving the probiotics market in the country. Additionally, the incorporation of probiotics into fitness modules is contributing to market growth in the U.S., as more consumers seek products that can support their overall health. This trend is particularly relevant given the increasing prevalence of obesity and stress disorders in the country.

The high prevalence of obesity, digestive disorders, and lifestyle-related diseases, often resulting from poor eating habits and high consumption of processed, high-sodium, and ready-to-eat foods, is likely to boost the demand for digestive health products in the country.

Curious about the U.S. Digestive Health Products Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Digestive Health Products Market Report Highlights

  • U.S. digestive health supplements market is expected to grow at a CAGR of 8.5% over the forecast period.The aging population and growing concerns about gut health are also major driving forces for the demand for digestive health supplements.
  • The food enzymes segment is projected to grow at a CAGR of 9.2% from 2024 to 2030. The growing awareness of the importance of healthy eating and the demand for natural, organic, and clean-label products has further driven the growth of the enzymes market, as consumers seek alternatives to synthetic ingredients and chemical additives.

U.S. Digestive Health Products Market Segmentation

Grand View Research has segmented the U.S. Digestive Health Products market based on product, ingredient, and distribution channel:

  • Product Outlook (Revenue, USD Million, 2018 - 2030)
    • Dairy Products
    • Bakery & Cereals
    • Non - Alcoholic Beverages
    • Supplements
    • Others
  • Ingredient Outlook (Revenue, USD Million, 2018 - 2030)
    • Prebiotics
    • Probiotics
    • Food Enzymes
      • Animal Based
      • Plant Based
      • Microbial Based

Download your FREE sample PDF copy of the U.S. Digestive Health Products Market today and explore key data and trends.
U.S. Environment Health and Safety Market: How Technology Enhances Safety

U.S. Environment Health and Safety Market Growth & Trends

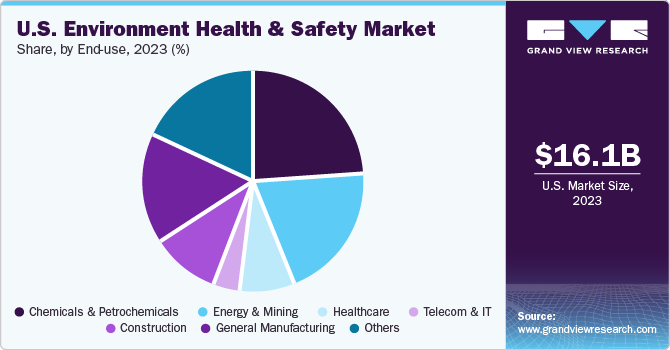
The U.S. Environment Health and Safety Market was estimated at USD 16.08 billion in 2023 and is projected to expand at a Compound Annual Growth Rate (CAGR) of 6.3% from 2024 to 2030. The U.S. commanded a significant 32.6% share of the global environment health & safety market. This growth trajectory is primarily driven by the stringent EHS standards imposed on companies, which necessitate substantial investment in EHS practices to avoid significant fines and penalties associated with non-compliance.

Regulatory Landscape and Key Players

Government agencies, including the U.S. Environmental Protection Agency (EPA), Occupational Safety and Health Administration (OSHA), and the U.S. Department of Labor, are responsible for establishing EHS norms and regulations. Companies like Trane Technologies exemplify a commitment to a safety-focused culture, striving for zero accidents and injuries across their organization.

Major market participants in the U.S. include Jacobs; AECOM; Enablon; Tetra Tech, Inc.; and VelocityEHS. These companies offer a broad spectrum of EHS software and services, encompassing ergonomics, engineering and construction, risk assessment, EHS software solutions, and management consulting and compliance.

Impact of Regulations and Public Awareness

Regulations play a pivotal role in shaping the U.S. environmental health & safety market. Government authorities such as OSHA, the EPA, and the Department of Justice (DOJ) mandate that organizations adhere to specific workforce safety and environmental regulations and standards, including the Toxics Release Inventory (TRI). These rigorous norms are anticipated to propel industry growth. Furthermore, rising public awareness regarding environmental issues has led to the development of environmental protection laws, which are expected to further drive market expansion. The high scrutiny and stringent regulations exert economic pressure on organizations to optimize their business processes and make them environmentally friendly. Consequently, management teams are compelled to deploy EHS software solutions in the workplace to reduce the occurrence of incidents.

Demand for EHS Services and Technological Integration

The escalating concern about the environmental footprint of business operations has significantly spurred demand for EHS services. Moreover, the advent and adoption of sophisticated EHS software solutions have streamlined the monitoring and management of EHS practices. Notably, 84% of companies utilizing EHS software have reported an ability to identify and fix potential safety issues before they occur. Beyond regulatory compliance, societal expectations for sustainable business operations have also fueled the EHS market's expansion. Growing consumer consciousness about companies' environmental practices often translates into greater support for those prioritizing EHS.

Curious about the U.S. Environment Health and Safety Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Environment Health and Safety Market Report Highlights

  • Chemicals & petrochemicals segment dominated the U.S. market share in 2023. It is also expected to be the fastest growing from 2024 to 2030.

  • The software product segment, while currently smaller in size, is projected to be the fastest-growing segment in the U.S. EHS market. It is expected to register a significant CAGR from 2024 to 2030.

  • The on-premises deployment type dominated the U.S. market in 2023. This dominance can be attributed to the control, security, and customization that on-premises solutions offer.

U.S. Environment Health and Safety Market Segmentation

Grand View Research has segmented the U.S. Environment Health and Safety market based on product, deployment mode, end-use:

  • U.S. Environment Health & Safety Market Product Outlook (Revenue, USD Billion, 2018 - 2030)
    • Software
    • Services
      • Analytics
      • Project Deployment & Implementation
      • Business Consulting & Advisory
      • Audit, Assessment, & Regulatory Compliance
      • Certification
      • Others
  • U.S. Environment Health & Safety Market Deployment Mode Outlook (Revenue, USD Billion, 2018 - 2030)
    • Cloud
    • On-Premises
  • U.S. Environment Health & Safety Market End-use Outlook (Revenue, USD Billion, 2018 - 2030)
    • Chemicals & petrochemicals
    • Energy & Mining
    • Healthcare
    • Telecom & IT
    • Construction
    • General Manufacturing
    • Others

Download your FREE sample PDF copy of the U.S. Environment Health and Safety Market today and explore key data and trends.
U.S. Freestanding Emergency Department Market: Trends Shaping Emergency Care

U.S. Freestanding Emergency Department Market Growth & Trends

The U.S. Freestanding Emergency Department Market was valued at an estimated USD 16.55 billion in 2024 and is projected to expand at a Compound Annual Growth Rate (CAGR) of 5.9% from 2025 to 2030. A primary driver of this market growth is the escalating overcrowding in traditional hospital emergency departments. In 2021, approximately 140 million visits to emergency departments highlighted the urgent need for alternative care options. With an expanding elderly population and an increasing prevalence of chronic diseases, the demand for urgent care services is expected to rise further, underscoring the critical role of FSEDs in alleviating congestion in conventional hospital settings.

Accessibility and Convenience Driving FSED Expansion

Accessibility and convenience are key factors fueling the growth of FSEDs. Approximately 70% of these facilities operate 24/7, enabling patients, particularly in underserved rural areas, to receive prompt urgent care without the extended wait times often encountered in hospital emergency departments. This immediate access to care is crucial for addressing health emergencies, especially as the incidence of injuries and acute conditions such as chest pain or strokes increases, demanding swift medical attention to improve survival rates and patient outcomes.

Favorable Regulatory Environment and Investment Opportunities

The favorable regulatory environment in the U.S. further bolsters FSED market growth. Higher reimbursement rates compared to traditional urgent care centers enhance their financial viability. Federal support and consumer-driven health plans are anticipated to encourage the establishment of more FSEDs in 2024, presenting an attractive investment opportunity for healthcare providers. This supportive landscape allows FSEDs to effectively meet the rising demand for accessible emergency care, thereby strengthening their position within the healthcare ecosystem.

Innovations and Future Outlook

Innovations such as telemedicine and enhanced diagnostic tools are optimizing operational efficiency and significantly improving patient outcomes within FSEDs. As patients increasingly seek immediate care coupled with high-quality treatment, the integration of such technologies becomes essential for meeting these expectations. Collectively, these drivers position the U.S. FSED market for sustained growth, effectively addressing critical gaps in emergency care delivery and reshaping the broader healthcare landscape.

Curious about the U.S. Freestanding Emergency Department Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Freestanding Emergency Department Market Report Highlights

  • In 2019, Hospital-based off-campus emergency department (OCED) held the largest share in the ownership segment of the U.S. FSED market and is expected to witness lucrative growth during the forecast period. This was attributed to the overcrowding of the hospital emergency department, and availability of high reimbursement for the treatment at OCED when compared with independent freestanding emergency department (IFSED), where no reimbursement is available

  • In 2019, Emergency department (ED) held the largest share in the service segment owing to a wide variety of services being provided for immediate care. It includes common medical services, such as treatment for stomach and abdominal pain, fever, headache, cough, back symptoms, and shortness of breath among others

  • The imaging service segment is expected to witness the highest growth during the forecast period. Majority of FSEDs offer basic imaging services, such as X-ray, ultrasound, and Computed Tomography (CT) scans. Freestanding emergency departments are either large facilities serving as many as 100 patients per day or small facilities serving 20 or fewer patients per day. Larger FSEDs can also offer MRI and primary care

  • Imaging services are expected to register the fastest CAGR of 6.3% over the forecast period, owing to their essential role in the rapid and accurate diagnosis of medical conditions

U.S. Freestanding Emergency Department Market Segmentation

Grand View Research has segmented the U.S. Freestanding Emergency Department market based on ownership and services:

U.S. Freestanding Emergency Department Ownership Outlook (Revenue, USD Million, 2018 - 2030)

  • Off-campus Emergency Department (OCED)
  • Independent Freestanding Emergency Department (IFSED)

U.S. Freestanding Emergency Department Services Outlook (Revenue, USD Million, 2018 - 2030)

  • Emergency Department (ED) Services
  • Laboratory Services
  • Imaging Services

Download your FREE sample PDF copy of the U.S. Freestanding Emergency Department Market today and explore key data and trends.
U.S. Cat Litter Products Market: How Clumping Litters Dominate Sales

U.S. Cat Litter Products Market Growth & Trends

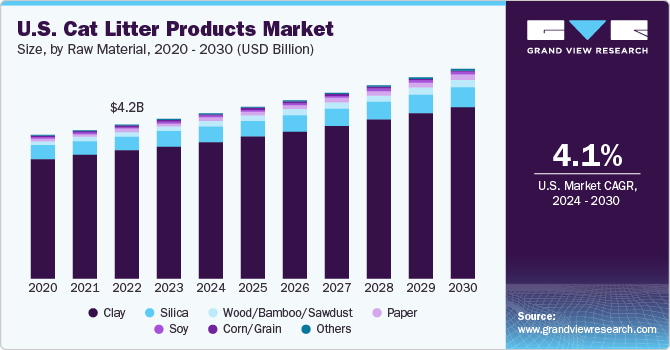
The U.S. Cat Litter Products Market was valued at an estimated USD 4.36 billion in 2023 and is projected to exhibit a CAGR of 4.1% from 2024 to 2030. This expansion is largely attributed to the rising rates of cat ownership and increasing pet expenditures within the U.S. A 2022 survey by the American Pet Products Association (APPA) revealed that two-thirds of pet owners consider their animals when setting financial objectives, demonstrating a strong commitment to providing necessary care, including food (75%) and exhibiting brand loyalty (56%).

Surging Pet Ownership and Prioritizing Pet Welfare

The adoption of pets in the U.S. surged in popularity, particularly during the pandemic as people spent more time at home. APPA data indicates that the percentage of homes with pets increased from 67% in 2019 to 70% in 2020. As pet owners increasingly prioritize the health, cleanliness, and welfare of their animals, the demand for cat litter in the U.S. is expected to continue rising. This trend creates a favorable environment for businesses offering premium, environmentally friendly cat litter products to anticipate steady growth and success.

Increased Spending and Product Preferences

Consumer spending on pets has reached unprecedented levels. The APPA reported that U.S. pet owners spent a record USD 103.6 billion on high-quality items for their cats in 2020. Additionally, as cats age, they can become more prone to allergies from scented cat litter products. Consequently, consumers are increasingly opting for odor-reducing and artificially odorless products.

Market Expansion and Distribution Strategies

U.S. enterprises are effectively reaching a broader global audience by supplying cat litter products through partnerships with online and offline distribution channels. For instance, in November 2020, Purina Tidy Cats introduced LightWeight Free & Clean cat litter on Loop, a global marketplace for household goods and consumables. The product was initially available for sale in ten states: New York, New Jersey, Maryland, Pennsylvania, Connecticut, Vermont, Rhode Island, Massachusetts, Delaware, and the District of Columbia, via Loop's online store.

The industry's growth is also fueled by the increasing number of people worldwide choosing cats as their preferred pets. According to APPA data, 42.7 million cats were owned in the U.S. in both 2019 and 2020. The rising demand is further driven by a growing segment of millennial pet owners who are well-informed about various pet products available in the market. For example, the American Veterinary Medical Association announced in May 2019 that millennials account for over 80% of pet owners in the U.S.

Environmental Concerns as a Restraint

Despite these positive trends, the market's expansion is being impeded by the use of ecologically unfavorable raw materials in cat litter production. For example, silica-based crystal cat litter has been identified as detrimental to the environment.

Curious about the U.S. Cat Litter Products Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Cat Litter Products Market Report Highlights

  • The U.S. conventional cat litter products market is projected to grow at a CAGR of 3.1% from 2024 to 2030. Growing customer preference for completely eliminating the smell of cat poop and pee is driving demand for traditional litter products.

  • The demand for wood/bamboo/sawdust-based cat litter products is anticipated to grow at a CAGR of 7.1% from 2024 to 2030. The market for wood-based cat litter products is expanding as customers place a higher value on eco-friendly and sustainable options.

  • Cat litter sales through supermarkets and hypermarkets channels accounted to the market share of 40.1% in 2023. Due to numerous retail discounts and offers, pet owners choose to buy pet care, food, and grooming supplies through these channels because they are less expensive than prescription-based products.

U.S. Cat Litter Products Market Segmentation

Grand View Research has segmented the U.S. Cat Litter Products market based on product type, raw materials, and distribution channel:

  • Product Type Outlook (Revenue, USD Billion, 2018 - 2030)
    • Clumping
    • Conventional
  • Raw Material Outlook (Revenue, USD Billion, 2018 - 2030)
    • Clay
    • Silica
    • Wood/Bamboo/Sawdust
    • Paper
    • Soy
    • Corn/Grain
    • Others
  • Distribution Channel Outlook (Revenue, USD Billion, 2018 - 2030)
    • Supermarkets and Hypermarkets
    • Specialty Retail Stores
    • Convenience Stores
    • Online/E-commerce

Download your FREE sample PDF copy of the U.S. Cat Litter Products Market today and explore key data and trends.
U.S. Earphone and Headphone Market: The Rise of True Wireless Earbuds

U.S. Earphone and Headphone Market Growth & Trends

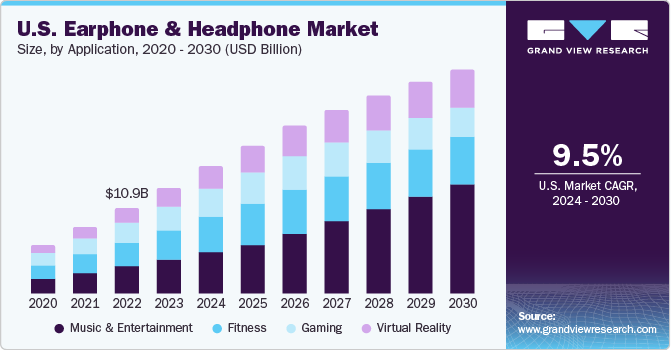
The U.S. Earphone and Headphone Market was valued at USD 13.17 billion in 2023 and is anticipated to experience a compound annual growth rate (CAGR) of 9.5% from 2024 to 2030. The U.S. market notably accounted for 18.4% of the global earphone and headphone market. The proliferation of portable music systems, including smartphones, tablets, and dedicated music players, is a primary driver for the earphone and headphone industry in the United States. Continuous advancements and innovations, particularly the development of sophisticated noise-cancellation features, have further enhanced their appeal. The market dynamics are rapidly evolving, characterized by a trend towards more affordable and compact earphones/headphones. Shifting consumer preferences towards wireless headphones have led to a significant surge in sales within the U.S. market.

Wireless Dominance and Technological Integration

The rising popularity of wireless products has spurred the introduction of true wireless earbuds, which eliminate the inconvenience of tangled wires. All leading brands have launched their versions of true wireless earbuds, incorporating advanced features. Notably, Apple Inc.'s AirPods currently dominate the true wireless earbuds segment in the U.S. market.

Recent technological breakthroughs in various wireless technologies, such as Wi-Fi, Bluetooth, SKAA, artificial intelligence (AI), and augmented reality (AR), are expected to fuel demand in the wireless segment over the next few years. The integration of AI and AR into earphones and headphones has enabled manufacturers to innovate and introduce advanced functionalities like noise cancellation, gesture recognition, and adaptive hearing features in their products. This is anticipated to positively impact market growth during the forecast period.

Health & Fitness Focus and Market Challenges

Furthermore, manufacturers are increasingly targeting health and fitness-conscious consumers by offering innovative features such as fitness monitoring and tracking in headphones. Such devices assist consumers in monitoring heart activity and other biometrics. Additionally, embedded software allows users to plan, monitor, and execute fitness activities through mobile applications. Consequently, the increasing adoption of earphones/headphones during workouts is expected to be a primary driver for the U.S. earphones & headphones market growth in the coming years.

However, the increasing availability of counterfeit products poses a potential challenge to the growth of the U.S. earphones & headphones market over the forecast period. The growing manufacture of low-cost, fraudulent products that offer similar features and benefits is expected to restrain market growth. Consumers often opt for products offering comparable features at a considerably lower price, which may further impede the U.S. earphones & headphones market's expansion.

Curious about the U.S. Earphone And Headphone Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Earphone And Headphone Market Report Highlights

  • The headphone segment is anticipated to witness a low CAGR of 1.4% from 2024 to 2030 in the U.S. market. The market for headphones in the USA might have reached a saturation point, with most consumers already owning a pair of headphones or wireless earphones.

  • The less than USD 50 segment is anticipated to witness a significant CAGR of 8.0% from 2024 to 2030.

  • Wired is anticipated to witness a low CAGR of 6.1% from 2024 to 2030 in the U.S. market. Increased demand for wireless Bluetooth earphones is causing a lower demand for wired earphones.

  • Virtual reality segment is expected to register the fastest CAGR of 8.8% during the forecast periodVirtual Reality (VR) and Augmented Reality (AR) technologies are gaining traction in the entertainment industry.

U.S. Earphone And Headphone Market Segmentation

Grand View Research has segmented the U.S. Earphone And Headphone market based on product, price band, technology, and application:

  • Product Outlook (Revenue, USD Million, 2018 - 2030)
    • Earphones
    • Headphones
  • Price Band Outlook (Revenue, USD Million, 2018 - 2030)
    • <USD 50
    • USD 50-100
    • >USD 100
  • Technology Outlook (Revenue, USD Million, 2018 - 2030)
    • Wired
      • ANC
      • Others
    • Wireless
      • ANC
      • Bluetooth
      • NFMI
      • Smart Headphones
      • Others
  • Application Outlook (Revenue, USD Million, 2018 - 2030)
    • Fitness
    • Gaming
    • Virtual Reality
    • Music & Entertainment

Download your FREE sample PDF copy of the U.S. Earphone and Headphone Market today and explore key data and trends.
U.S. Agricultural Tractor Market: Trends Driving Modern Agriculture

U.S. Agricultural Tractor Market Growth & Trends

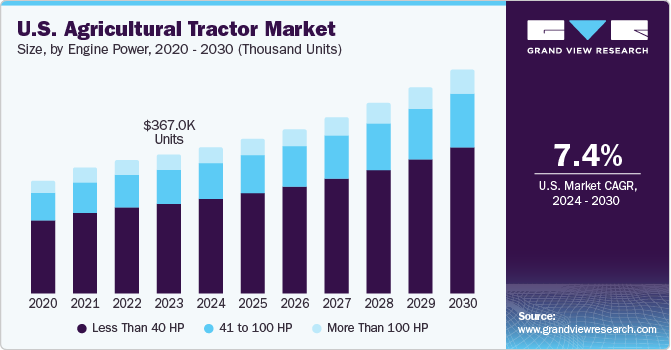
The U.S. Agricultural Tractor Market reached 367.04 thousand units in 2023 and is projected to expand at a Compound Annual Growth Rate (CAGR) of 7.4% from 2024 to 2030. In 2023, the U.S. market constituted a significant 11.8% share of the global agricultural tractors market. This growth is primarily driven by the increasing mechanization within the farm industry, which has boosted the demand for versatile compact tractors that can be customized to specific customer needs. Furthermore, technological advancements, including the integration of telematics and automation into agricultural tractors, are expected to further propel market expansion.

Factors Driving Market Growth

A critical factor contributing to the increased adoption of agricultural tractors is the shortage of skilled farm labor, which necessitates greater mechanization in farming operations. The overall productivity of farming is improving due to the rising integration of mechanization and other farming equipment. This rapid adoption is further enhanced by the technological advancements offered by AI, Big Data, and Machine Learning (ML). Agricultural tractors are an indispensable part of modern farming equipment, playing a vital role in mechanizing numerous farming activities and thereby significantly increasing agricultural productivity. This has directly led to a surge in demand for tractors, consequently fueling market growth.

Government Support and Cost Considerations

Given that farm equipment such as combines, tractors, and harvesters represent substantial investments, farmers often face challenges in acquiring them due to limited financing options. To address this, the government provides various monetary and non-monetary benefits to farmers, including subsidies for the purchase of seeds, fertilizers, and farm equipment. For instance, the U.S. Farm Service Agency (FSA) offers guaranteed and direct farm ownership and operating loans to family-size farmers who may not qualify for commercial credit from traditional lenders. These FSA loans can also be utilized for purchasing livestock, equipment, land, feed, seed, and supplies.

Despite these supportive measures, farm power, equipment, and machinery constitute significant agricultural costs. The introduction of larger machines, technological advancements, increased costs of parts and new machinery, and a substantial rise in energy prices over the years have all contributed to an escalation in power and machinery costs in recent years. Moreover, the use of tractors inherently involves timely repair and maintenance expenses due to routine wear and tear, along with additional costs stemming from accidents. Consequently, these high costs associated with agricultural tractors can act as a restraint on market growth.

Curious about the U.S. Agricultural Tractor Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Agricultural Tractor Market Report Highlights

  • The less than 40 HP segment held more than 64% of the market share in terms of volume in 2023. This large share is due to the low cost, compact size, and greater convenience offered by less than 40HP tractors to perform all basic farming operations.

  • The 2WD segment held more than 80% market share in terms of volume in 2023. The segment is also anticipated to register the fastest CAGR from 2024 to 2030.
  • Electric tractors offer high compatibility with evolving regulatory standards and present a cost-effective solution with lower maintenance requirements. This shift reflects the industry's commitment to sustainability and aligns with global efforts to reduce carbon emissions and promote greener technologies in the agricultural sector.

U.S. Agricultural Tractor Market Segmentation

Grand View Research has segmented the U.S. Agricultural Tractor market based on engine power, driveline, and propulsion:

  • Engine Power Outlook (Volume, Thousand Units; Revenue, USD Million, 2017 - 2030)
    • Less Than 40 HP
    • 41 to 100 HP
    • More Than 100 HP
  • Driveline Outlook (Volume, Thousand Units; Revenue, USD Million, 2017 - 2030)
    • 2WD
    • 4WD
  • Propulsion Outlook (Volume, Thousand Units, Revenue, USD million 2017 – 2030)
    • Electric
    • ICE

Download your FREE sample PDF copy of the U.S. Agricultural Tractor Market today and explore key data and trends.
U.S. IT Services Market: How AI is Revolutionizing IT Solutions

U.S. IT Services Market Growth & Trends

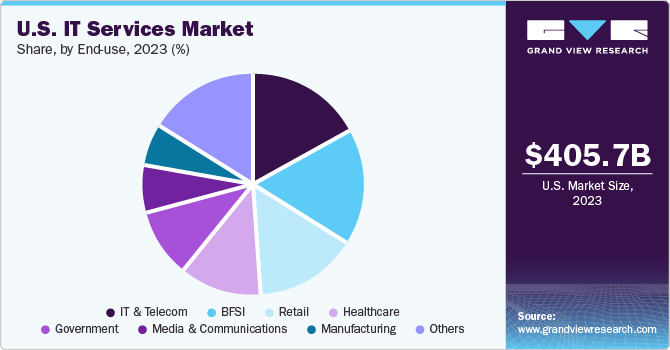
The U.S. IT Services Market was valued at a substantial USD 405.7 billion in 2023, with projections indicating a healthy CAGR of 7.9% from 2024 to 2030. This significant growth is driven by the transformative impact of technologies such as big data analytics, artificial intelligence (AI), the Internet of Things (IoT), and machine learning (ML), which have fundamentally altered the business landscape. Additionally, the escalating demand for robust cybersecurity solutions, fueled by increasing privacy concerns, has encouraged considerable investment in IT services. Established companies are well-positioned to innovate and capitalize on technological advancements and the increasing availability of data.

Cloud Adoption and Digital Transformation

American consumers are increasingly embracing cloud-based solutions and Software-as-a-Service (SaaS). Businesses are actively seeking advanced services to promote automation and streamline supply chains. The adoption of business intelligence and cloud technologies has become particularly prominent across the U.S. Digital tools are gaining traction as a means to achieve cost savings, gain valuable operational insights, and boost overall efficiency. For example, the growing demand for personalization, customization, and mobility from services is prompting stakeholders to explore innovative solutions.

The Rise of Managed Services

Managed services have become a critical component for gaining a competitive advantage within the U.S. IT industry. In the financial sector, for instance, managed services are crucial for navigating complex regulatory environments, implementing the latest security measures, leveraging technological expertise, and adopting secure and scalable infrastructure. Furthermore, the manufacturing industry can leverage managed services to minimize repetitive tasks through automation and effectively manage the ever-increasing volume of data.

Curious about the U.S. IT Services Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. IT Services Market Report Highlights

  • The reactive IT services segment spearheaded the U.S. IT services market, accounting for 55.5% revenue share in 2023. The growth is partly attributed to the trend for cloud-based services for alerting, monitoring and incident management capabilities.

  • The operations & maintenance segment is poised to witness an uptake in light of the rising footprint of AI, ML, and robotic process automation. The design & implementation segment will rise against the backdrop of heightened demand for user-centric solutions and technological advancements.

  • The application management segment is likely to grow in the wake of the need to minimize ownership costs, boost performance and reliability and enhance security. The advanced application management solution helps maintain, optimize and monitor applications.

  • The AI & machine learning segment is forecast to depict a significant uptake during the assessment period. The robust outlook comes against the backdrop of automation trends reshaping the industry verticals.

  • The on-premises segment will grow on the heels of heightened demand to manage data and applications more effectively. Prominently, stakeholders are banking on on-premises IT services for increased security and customization.

  • The large enterprise segment is likely to depict significant uptake during the forecast period. The growth outlook is mainly attributed to the trend for cloud computing.

  • The IT & telecom segment to witness a notable uptick on the back of a bullish adoption of cloud computing and other bespoke solutions. The demand for managed IT services will be pronounced to reinforce customer experience and maintain a competitive edge.

U.S. IT Services Market Segmentation

Grand View Research has segmented the U.S. IT Services market based on approach, type, application, technology, deployment, enterprise size, and end-use:

  • Approach Outlook (Revenue, USD Billion, 2017 - 2030)
    • Reactive IT Services
    • Proactive IT Services
  • Type Outlook (Revenue, USD Billion, 2017 - 2030)
    • Design & Implementation
    • Operations & Maintenance
  • Application Outlook (Revenue, USD Billion, 2017 - 2030)
    • Systems & Network Management
    • Data Management
    • Application Management
    • Security & Compliance Management
    • Others
  • Technology Outlook (Revenue, USD Billion, 2017 - 2030)
    • AI & Machine Learning
    • Big Data Analytics
    • Threat Intelligence
    • Others
  • Deployment Outlook (Revenue, USD Billion, 2017 - 2030)
    • On-premises
    • Cloud
  • Enterprise Size Outlook (Revenue, USD Billion, 2017 - 2030)
    • Large Enterprise
    • Small & Medium Enterprise
  • End-use Outlook (Revenue, USD Billion, 2017 - 2030)
    • BFSI
    • Government
    • Healthcare
    • Manufacturing
    • Media & Communications
    • Retail
    • IT & Telecom
    • Others

Download your FREE sample PDF copy of the U.S. IT Services Market today and explore key data and trends.
U.S. Solar PV Market: How Policy Drives Renewable Growth

U.S. Solar PV Market Growth & Trends

The U.S. Solar Photovoltaic Market is on a significant growth trajectory, projected to hit an impressive USD 96.6 billion by 2030. This expansion represents a robust compound annual growth rate (CAGR) of 13.7% from 2023 to 2030, according to a recent report from Grand View Research, Inc. The increasing adoption of solar PV in the U.S. is largely fueled by the decreasing cost of solar PV systems, making them a more attractive energy solution. Furthermore, a surge in government incentives and diverse financing options is anticipated to further propel the industry's expansion.

Government Initiatives and Utility-Scale Projects

The U.S. government is actively working to lessen the nation's reliance on traditional energy sources, favoring the increased integration of renewables like solar, wind, and hydrogen. A key strategy involves the construction of utility-scale projects designed for large-scale power generation. The utility sector, responsible for providing electricity to entire communities, is seeing substantial investment from the U.S. government. These investments aim to bolster utility-scale solar PV projects and facilitate the phasing out of coal and gas power generation. Recognizing this burgeoning market, many private companies are also investing in utility-scale solar. For example, in April 2022, Primenergy announced plans for the largest solar PV plant in the U.S., located in Nevada, which is set to generate 690MW of electricity and be operational by 2023.

Regional Growth and Market Dynamics

The escalating demand for solar PV across the country is directly linked to the decreasing prices of solar PV technologies, making them increasingly economically viable. States boasting high solar irradiance, such as California, Arizona, and Texas, are expected to experience accelerated growth due to shorter return on investment periods. Conversely, states like New York, New Jersey, and Massachusetts are projected to see growth primarily in the residential segment. This is attributed to their higher population density and relatively limited land availability for large-scale utility projects.

Innovation and Strategic Collaborations

Industry leaders are keenly focused on innovation and technological advancements to drive down the cost of solar PV, making it more competitive with conventional power sources like natural gas and coal. Additionally, market participants are engaging in various strategic initiatives, including joint ventures, partnerships, and mergers & acquisitions, to solidify their market position in the coming years.

Curious about the U.S. Solar PV Market? Download your FREE sample copy now and get a sneak peek into the latest insights and trends.

U.S. Solar PV Market Report Highlights

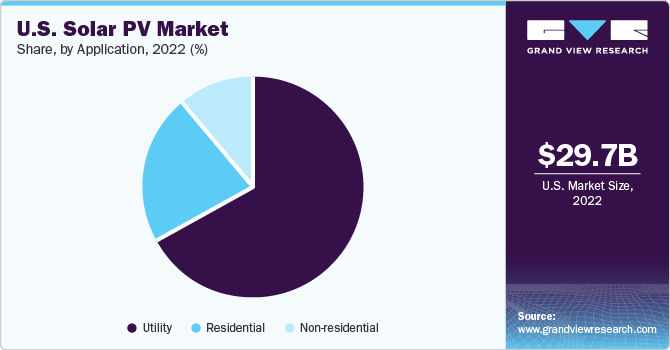
  • In 2022, utility emerged as the largest segment with a revenue share of 66.68%, owing to the utility segment being the most cost-effective and higher investments from the government and private companies

  • Texas held a dominant market in 2021 due to a higher irradiance factor of the state and the increasing demand for sustainable energy is expected to boost the growth during the forecast period

  • New Mexico is estimated to grow at a significant CAGR over the forecast period owing to the lower penetration of renewable energy in the state boosting market demand and the high amount of sunlight in the state

U.S. Solar PV Market Segmentation

Grand View Research has segmented the U.S. Solar PV market based on application & state:

U.S. Solar PV Application Outlook (Volume, MW; Revenue, USD Billion, 2018 - 2030)

  • Residential
  • Non-residential
  • Utility

U.S. Solar PV State Outlook (Volume, MW; Revenue, USD Billion, 2018 - 2030)

  • California
  • Arizona
  • New Jersey
  • North Carolina
  • Nevada
  • Massachusetts
  • Hawaii
  • Colorado
  • New York
  • Texas
  • Florida
  • Georgia
  • Utah
  • Virginia
  • South Carolina
  • Maryland
  • New Mexico
  • Oregon
  • Indiana
  • Minnesota
  • Pennsylvania

Download your FREE sample PDF copy of the U.S. Solar PV Market today and explore key data and trends.
U.S. Railing Market: Beyond Code – Elevating Safety and Style

U.S. Railing Industry Overview

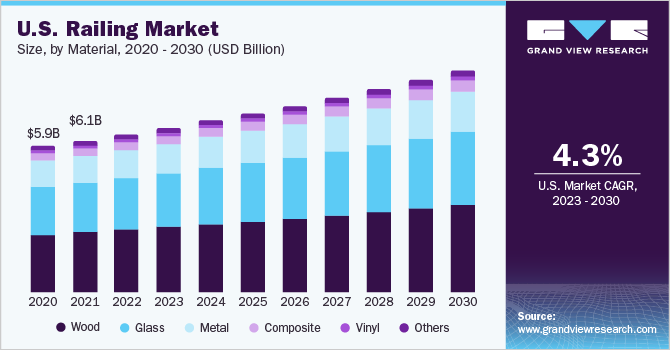
The U.S. Railing Market was valued at USD 5.92 billion in 2022. It is projected to expand at a compound annual growth rate (CAGR) of 3.9% from 2023 to 2030. This growth stems from several key factors, including the increasing demand for affordable housing and rising government investments in residential construction.

Additionally, a growing preference for eco-friendly products, driven by heightened environmental concerns, is contributing to the market's expansion. The rapid growth of the U.S. construction industry, fueled by modernization and the ongoing shift of populations from rural to urban areas for better opportunities, also plays a significant role. Furthermore, the U.S. Administration's announced plans for constructing affordable homes in the coming years are expected to further propel the growth of the railing market.

Detailed Segmentation:

  • Material Insights

The wood railing segment led the market and accounted for the largest revenue share of 41.5% in 2022. The segment is expected to witness growth on account of the excellent aesthetic properties and affordable prices of wood. Due to its high strength, longevity, and ease of maintenance, wood is extensively used in railing applications.

The demand for metal railing is expected to grow at a CAGR of 4.2% throughout the projected period 2023-2030 on account of their high strength and durability. Metal railings are made of stainless steel, aluminum, brass, wrought iron, and cast iron. Metal railings are robust, sturdy, and require minimal maintenance, which, in turn, is expected to lead to the growth of the railing market in the U.S.

  • Application Insights

The residential application segment accounted for the highest market share of 52.0% in 2022 and is anticipated to grow at a CAGR of 4.1% over the forecast year. The majority of the revenue generated by the residential railing market comes from metal and composite railing. The residential sector has been growing significantly and is predicted to rise considerably throughout the projection period. The growth in single-family residential construction and remodeling activities in the U.S. are mainly driving the residential sector. Therefore, the demand for railing in the U.S. is anticipated to increase with the increase in residential construction and remodeling activities.

The non-residential sector accounted for USD 2,848.1 in 2022, and it is growing at a significant rate over the forecast year. The demand for railing in the non-residential sector of the U.S. is expected to increase due to the rebounding of offices and commercial spaces. In addition, corporate buildings, hotels, retail centers, and industrial structures need railing installed across their properties for security purposes. These elements are expected to encourage the expansion of the non-residential railing market in the U.S.

Gather more insights about the market drivers, restraints, and growth of the U.S. Railing Market

Key Companies & Market Share Insights

The U.S. railing market exhibits high competition owing to the presence of established players in this market with vertical integration across the value chain of railing. Some competitors also focus on increasing their innovations through mergers and acquisitions with top manufacturers in order to gain a competitive edge.

Key participants in the market are also focusing on technological developments for improving the quality of raw materials, components, and installation processes, thus, creating strong competition for new entrants. Additionally, the players are fulfilling the demand for eco-friendly railing systems, and hence their market penetration is higher. Some prominent players in the U.S. railing market include:

  • Q-railing
  • VIVA Railing
  • Century Aluminum Railing
  • GRECO Architectural Metals
  • AMERICAN RAILING SYSTEMS, INC.
  • The Wagner Companies
  • ViewRail
  • Fortress Building Products
  • HDI Railing Systems
  • Trex Company, Inc.
  • Barrette Outdoor Living

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

Swine Vaccines Market: Decoding the Latest Trends in Disease Prevention

Swine Vaccines Industry Overview

The global Swine Vaccines Market was estimated at USD 1.75 billion in 2024 and is predicted to expand at a CAGR of 5.51% from 2025 to 2030. This growth is primarily driven by increasing concerns about food security due to rising disease outbreaks and zoonoses, alongside the widespread adoption of antibiotic-free disease prevention methods. Highly contagious diseases like porcine reproductive and respiratory syndrome (PRRS) and swine influenza continue to be prevalent in Asian, European, and American pig herds, causing significant economic losses. Consequently, swine producers are extensively implementing biosecurity measures and vaccination programs to mitigate these impacts.

Detailed Segmentation:

  • Product Insights

The Inactivated (Killed) segment led the market with the largest revenue share of 52.03% in 2024. This is attributed to its easy availability, low cost, and stability advantages over live-attenuated vaccines. They minimize the risk of virulence reversion after vaccination, as it prevents the replication process of pathogens. Moreover, it offers pigs better immunization with a rapid cell-mediated immune response. Immunity obtained from Inactivated (Killed) can be further enhanced with adjuvants such as certain types of oils or aluminum hydroxide. However, considerable care must be taken while preparing, storing, and handling Inactivated (Killed) for effective results.

  • Disease Type Insights

The FMD segment is anticipated to witness at the fastest CAGR of 6.24% over the forecast period. The rising emphasis on FMD prevention, particularly in pig farming areas, is expected to drive the fastest growth. For instance, the launch of the 4th round of the FMD Vaccination Mission in Nagaland is a significant step toward controlling and eradicating FMD in India, particularly among pig, which are highly susceptible to the virus. With the government’s goal to eradicate FMD by 2030 under the National Animal Disease Control Programme (NADCP), the demand for FMD vaccines in the pig sector is poised to grow rapidly.

  • Route of Administration Insights

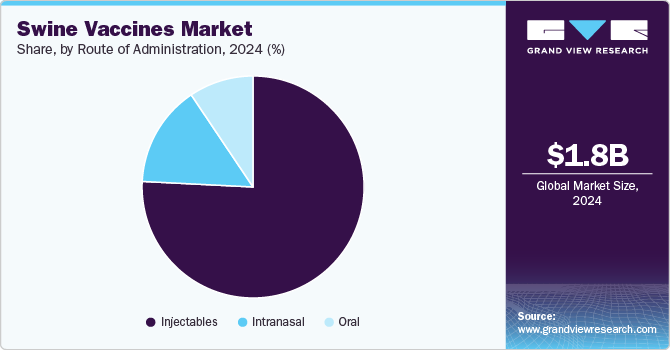
Based on route of administration, the injectable segment led the market with the largest revenue share of 75.79% in 2024, due to its efficiency and effectiveness in providing long-lasting protection against major diseases in pigs. Injectable vaccines, such as those targeting PCV2, Mycoplasma hyopneumoniae, and other common pathogens, offer a convenient and reliable solution for farmers to ensure the health and productivity of their herds. These vaccines typically require fewer doses, often providing extended protection with a single injection, which is both time-efficient and cost-effective for large-scale operations. As the industry focuses on improving disease management and biosecurity, the injectable segment is expected to continue driving growth, catering to the growing demand for effective disease prevention in pig farming.

  • Distribution Channel Insights

The e-commerce segment is projected to grow at the fastest CAGR over the forecast period. This expansion is driven by the increasing adoption of digital platforms by veterinarians and pig producers, seeking convenient access to a broader range of vaccine products. The rise of e-commerce and D2C channels in the pig circovirus vaccine is reshaping traditional distribution models. This shift is expected to enhance market reach and operational efficiency, contributing to the overall market growth.

  • Regional Insights

North America dominated the swine vaccines market with the largest revenue share of 38.46% in 2024. This is attributed to the region's advanced veterinary healthcare infrastructure and the launch of innovative combination vaccines. For instance, in June 2023, Boehringer Ingelheim Animal Health Canada Inc. introduced a unique vaccine that protects pigs against PCV2 and PRRSv in a single dose. This advancement, enabled by a proprietary purification process, allows the seamless mixing of Ingelvac CircoFLEX with Ingelvac PRRS MLV without compromising efficacy. Such offerings address critical health challenges while enhancing operational efficiency, thus driving market growth in the region.

Gather more insights about the market drivers, restraints, and growth of the Swine Vaccines Market

Key Companies & Market Share Insights

The market is relatively competitive and fragmented due to multiple small and large companies. Moreover, companies are increasingly adopting various strategies, such as mergers and acquisitions, geographic expansions, and product launches, to expand their market shares. Owing to constant research initiatives, this industry can be seen as moderate to high in innovation.

Key Swine Vaccines Companies:

The following are the leading companies in the swine vaccines market. These companies collectively hold the largest market share and dictate industry trends.

  • Merck & Co., Inc.
  • Ceva
  • Zoetis
  • Boehringer Ingelheim GmbH
  • Elanco
  • Indian Immunologicals Ltd.
  • BiogénesisBagó
  • Phibro Animal Health
  • KM Biologics
  • HIPRA
  • Virbac

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

Recent Developments

  • In September 2024, Merck & Co., Inc. received marketing authorization from the EMA for PORCILIS PCV M Hyo ID, an intradermal vaccine used in swine. Such milestones support total pig health and contribute to market growth.

  • In July 2024, South Africa took a groundbreaking step in combating African Swine Fever (ASF) with the FDA and DA BAI announcing the approval of the country's first ASF vaccine, aiming to stabilize the pork industry and protect the meat supply chain. 

RNA Targeting Small Molecule Drug Discovery Market: Key Technologies and Breakthroughs

RNA Targeting Small Molecule Drug Discovery Industry Overview

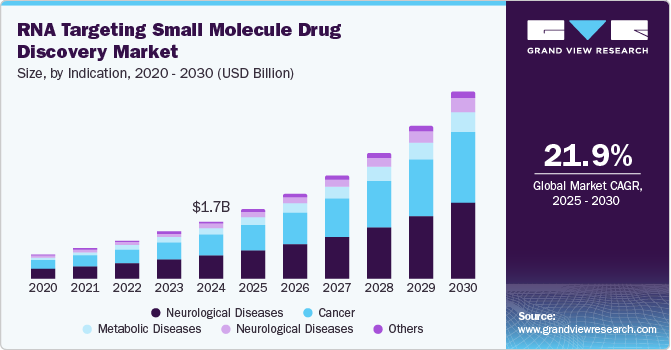
The global RNA Targeting Small Molecule Drug Discovery Market was valued at USD 1.66 billion in 2024. It is projected to reach a CAGR of 21.9% from 2025 to 2030. This market expansion is anticipated due to the increasing demand for RNA-targeted small molecule drugs, which can address a wide array of diseases, including various cancers, neurological disorders, and genetic conditions. Furthermore, continuous advancements in RNA-targeted drug discovery technologies and a rise in government funding dedicated to RNA research are expected to contribute significantly to market growth.

Detailed Segmentation:

  • Indication Insights

The cancer segment is expected to grow at the fastest CAGR of 22.3% over the forecast period. RNA-targeted medications are advantageous for treating cancer as they can target cancer cells only and are made to specifically target cancer-related genetic alterations, which increases their efficacy and minimizes adverse effects. Many pharmaceutical companies are investing heavily in RNA-targeted drug discovery for cancer treatment, which is expected to drive market growth in the coming years. While the cancer segment is expected to witness considerable growth, the market is also expected to diversify as more RNA-targeted drugs are developed for other indications, such as genetic disorders and viral infections.

  • End-use Insights

The pharmaceutical and biopharmaceutical companies segment led the market with a revenue share of 59.4% in 2024. Pharmaceutical companies are driving advancements in RNA-targeting drug discovery through heavy R&D investment, strategic collaborations (such as Evotec and Takeda’s), and technological advancements such as AI integration and advanced sequencing. For instance, in December 2024, Rgenta Therapeutics and GSK announced a strategic alliance to develop RNA-targeted small molecule splice modulators for various diseases, including oncology. Pharmaceutical companies are also developing innovative platforms, exploring diverse RNA targets, and focusing on personalized medicine approaches. Emerging biotech startups and RNA editing technologies are further contributing to this rapidly evolving field.

  • Regional Insights

Asia Pacific RNA targeting small molecule drug discovery market is expected to register the fastest CAGR of 6.1% in the forecast period. Market growth in the region is driven by the growing healthcare sector, increasing investments in research and development, and a rising prevalence of chronic diseases. The large patient pool and unmet medical needs in the region further contribute to the growth of this market. Government initiatives to promote drug discovery and development, coupled with a growing awareness of RNA-targeted therapies, are expected to fuel the market’s growth in the Asia Pacific region.

Gather more insights about the market drivers, restraints, and growth of the RNA Targeting Small Molecule Drug Discovery Market

Key Companies & Market Share Insights

The following are the leading companies in the RNA targeting small molecule drug discovery market. These companies collectively hold the largest market share and dictate industry trends.

  • ACCENT THERAPEUTICS
  • Anima Biotech Inc.
  • Arrakis Therapeutics
  • AstraZeneca
  • Epics Therapeutics
  • Expansion Therapeutics
  • F. Hoffmann-La Roche Ltd

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

Recent Developments

  • In March 2025, Arrakis Therapeutics presented preclinical data for its RNA-targeted small molecule drug program for the treatment of myotonic dystrophy type 1 (DM1) at the Muscular Dystrophy Association (MDA) conference in Dallas, Texas.
  • In October 2024, Anima Biotech announced its machine learning platform, Lightning, which identifies mRNA drug targets and screens for potential small molecule therapies. The company had identified 20 therapeutic candidates across various disease areas.
  • In July 2024, Citeline, in collaboration with the American Society of Gene & Cell Therapy, approved two RNA therapies-Rytelo for myelodysplastic syndrome and mRESVIA for RSV prophylaxis-in the U.S.
  • In April 2024, Ribometrix presented data at the AACR Annual Meeting 2024, validating its RNA-targeting platform and demonstrating the potential of its EIF4E program for cancer treatment.

Pet Shampoo Market: What's Driving the Surge in Organic Products?

Pet Shampoo Industry Overview

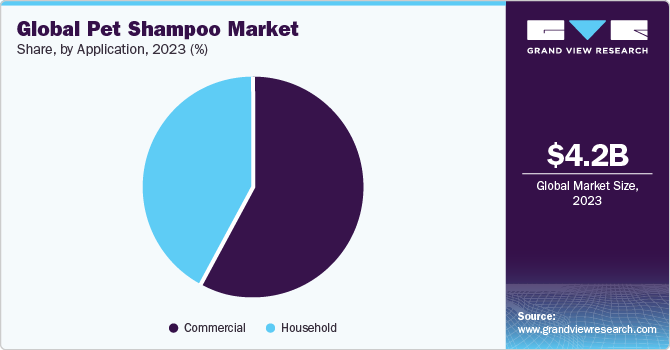
The global Pet Shampoo Market was valued at USD 4.23 billion in 2023. Projections indicate a compound annual growth rate (CAGR) of 5.7% from 2024 to 2030. This expansion is largely fueled by a growing pet population and increased awareness among pet owners about the importance of proper hygiene for their companions. A March 2023 report by the American Pet Products Association (APPA) highlighted that approximately 66% of all American households, or 86.9 million households, own a pet.

Detailed Segmentation:

  • Animal Insights

The cat segment is projected to grow at a CAGR of 5.2% over the forecast period. The increasing availability of shampoos specially formulated for cats and the increasing acceptance of cats as companion animals is favoring the market growth. Cats are increasingly becoming popular as companion animals, contributing to the rise in cat ownership. For instance, according to the RSPCA Australia, there were approximately 28.7 Billion pets in 2022, of which cats (33%) accounted for the second highest pet population after dogs (48%).

  • Distribution Channel Insights

The sales of pet shampoo through online channel is projected to grow at a CAGR of 6.6% from 2024 to 2030. Online platforms offer pet owners the convenience of shopping from the comfort of their homes, with 24/7 accessibility and the option to compare prices and read reviews before making a purchase. Additionally, the availability of specialized pet care products and the ability to cater to specific pet needs, such as sensitive skin or allergies, contribute to the popularity of online channels for pet shampoo sales. In January 2024, The Wires launched its B2B2C platform PawWire at the 2024 Consumer Electronics Show Showstoppers media event in Las Vegas, U.S. This platform offers a range of pet products such as toys, training, grooming, and other products, including shampoos.

  • Application Insights

The household segment is estimated to grow at a CAGR of 6.4% from 2024 to 2030. The adoption of pet shampoo for household application is driven by the increasing awareness of pet hygiene and health among pet owners, who prioritize keeping their furry companions clean and comfortable within the home environment. Additionally, the desire to minimize pet-related odors, reduce allergens, and maintain a clean living space for both pets and their owners further incentivizes the use of pet shampoo as a convenient and effective solution for regular grooming and hygiene routines.

  • Regional Insights

Asia Pacific pet shampoo market is projected to grow at a CAGR of 8.1% from 2024 to 2030. The trend of organic and natural products has also reached the pet care industry. Many pet owners in the region are now looking for pet shampoos that are made from natural and organic ingredients, free from harsh chemicals and artificial fragrances. For instance, the Himalaya Erina-EP Shampoo by Himalaya Wellness Company is gaining popularity in India. This shampoo is specifically formulated for dogs and contains natural ingredients such as neem and eucalyptus, which help in maintaining a healthy coat and skin for cats, dogs, and other pet animals.

Gather more insights about the market drivers, restraints, and growth of the Pet Shampoo Market

Key Companies & Market Share Insights

The market features both established global firms and emerging players. Key industry leaders prioritize product innovation, differentiation, and distinctive designs in line with evolving consumer preferences. Leveraging extensive global distribution networks, these major players effectively reach diverse customer bases and tap into emerging markets.

Key Pet Shampoo Companies:

The following are the leading companies in the pet shampoo market. These companies collectively hold the largest market share and dictate industry trends.

  • GroomersChoice.com
  • SynergyLabs
  • Compana (Vet’s Best)
  • Himalaya Wellness Company
  • Petco Animal Supplies, Inc.
  • LOGIC PRODUCT GROUP LLC
  • Wahl Clipper Corporation
  • 4-Legger
  • Earthwhile Endeavors, Inc.
  • WildWash

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

Recent Developments

  • In June 2023, Earthwhile Endeavors, Inc. announced the launch of a Shea Butter Shampoo. This shampoo is specially formulated for dander care and moisture repair in cats and dogs of all breeds, especially those with sensitive, allergy-prone, and dry skin.
  • In April 2023, Petco Animal Supplies, Inc. announced the launch of Clean Grooming initiatives, which include clean grooming and services for pets across the 1,350 Petco care centers, the company’s website, and the app. The primary products used in grooming services include shampoos, balms, and conditioners.

Quantum Computing Market: The Billion-Dollar Quest for Unprecedented Power

Quantum Computing: A Huge Leap In Technology

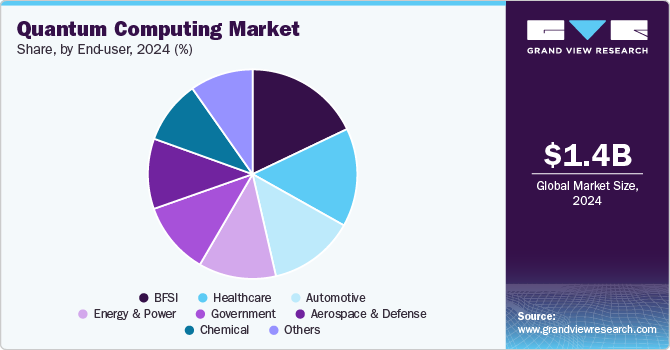
Quantum computing is not a concept of science fiction anymore. As we are currently in a new era of computational capability, the best brains from every field are trying to utilize the power of quantum mechanics to solve problems that classical computers simply cannot handle. Quantum computing is “poised to unlock a new reality,” with impacts spanning chemistry, energy, AI, autonomous navigation, and cybersecurity. With quantum computing, simulating complex molecules in drug discovery to optimizing global supply chains, the practical potential of it is beginning to be realized at scale.

North America, comprising the United States and Canada, is a leader in this transformative field due to heavy public investments, a strong research and development culture, and increasing enterprise engagement. Globally, the Quantum Computing Market is expected to surpass $4 billion by 2030. Major tech firms such as Amazon, IBM, Google, and Microsoft have already launched commercial quantum-computing services, and startups around the world are racing to build quantum processors and software.

Growth Factors and Applications Driving the Quantum Computing Market

Listed below are the primary growth drivers and applications of quantum computing.

Rising Government Investment

Globally, governments are making huge investments in quantum research and hardware infrastructure. The U.S. National Quantum Initiative and Canada’s National Quantum Strategy are prime examples of investments in accelerating innovation and commercialization. This encouragement has created a favorable ground for startups and research institutions to succeed.

Enterprise Adoption Across Industries

Established players in finance, pharmaceuticals, automotive, and logistics are increasingly exploring the possibilities of quantum computing applications. For instance, JPMorgan Chase is using quantum algorithms to optimize portfolio risks. BMW is using quantum computing power in engine and battery integration for optimizing production processes, such as robot route planning at BMW Group plants.

Quantum-as-a-Service (QaaS) via Cloud Platforms

Quantum computing is becoming more accessible without any huge investments in hardware. This has been possible due to the cloud services offered by platforms such as IBM Quantum, Amazon Braket, and Microsoft Azure Quantum, which allow developers and researchers to experiment with quantum systems remotely. This model lowers the barrier to entry and enables quantum computing access at lower costs.

Cybersecurity Demands and Post-Quantum Encryption

With ongoing advancements in the computing capabilities of quantum computers, they pose a threat to current encryption methods. Hence, many companies have started investing in post-quantum cryptography and quantum key distribution (QKD). These technologies are important for securing future communications against quantum threats, making them a potential growth factor.

Cross-Industry Applications

Quantum computing is impacting a variety of sectors. In healthcare, quantum algorithms can help simulate proteins for drug discovery much faster than current conventional computers. In logistics, companies such as DHL and Volkswagen are experimenting with route optimization using quantum-inspired computing. In energy, quantum simulations are being used to model new materials for batteries and solar panels. These quantum computing applications underscore the technology’s wide-reaching potential.

Gather more insights about the market drivers, restraints, and growth of the Quantum Computing Market

Emerging Trends and Innovations in the Global Market

Advancements in Quantum Hardware

Companies globally are trying to develop more powerful and stable (fault-tolerant) quantum processors. IBM's Eagle (127 qubits) and Google's Sycamore (which achieved quantum supremacy) represent significant leaps in quantum hardware. IBM has also unveiled plans for its 1,000+ qubit chip, Condor, aiming for practical quantum advantage within the next few years.

Hybrid Quantum-Classical Systems

Hybrid systems that blend classical and quantum computing are expected to be among the most popular applications. Companies are developing hybrid solutions that integrate classical computing with quantum algorithms. D-Wave’s Leap Quantum Cloud Service and Rigetti Computing’s platforms are examples of this trend, which offer practical solutions for today’s complex computational problems.

Integration of Quantum Computing with Artificial Intelligence

The integration of quantum computing and AI is opening up new opportunities. Companies like Quantinuum are developing quantum natural language processing tools, strengthening AI's ability to process and understand complex data structures. This integration can yield more efficient and powerful AI applications.

Quantum Software and Ecosystems

A rich ecosystem of software tools and partnerships are being developed to enhance application development. For example, Classiq (an Israeli startup) offers a high-level algorithm-design platform that is already used by BMW, Citi, and Deloitte.

The Road Ahead

Quantum computing is not a futuristic curiosity; it is a rapidly evolving technology that is poised to revolutionize industries. For organizations across sectors, now is the time to understand the technology, assess its applications, and consider partnerships with quantum computing companies. As we approach the tipping point where quantum advantage becomes reality, early adopters will gain significant strategic benefits.

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

Packaging Paper Market: The Eco-Friendly Edge in Global Commerce

Packaging Paper Industry Overview 

Sustainability is more than a buzzword. It's a business imperative. As both consumers and brands rally around eco-conscious choices, traditional plastic packaging is giving way to biodegradable and recyclable paper-based alternatives. Once seen as a basic utility, packaging has evolved into a critical component of product identity. This shift is not only changing the materials we use but also how we perceive value, innovation, and responsibility in packaging. 

Government bans and levies on single-use plastics, particularly in the EU and Asia-Pacific regions, are accelerating the shift toward paper alternatives. Companies failing to adapt risk both reputational damage and compliance costs. 

On the other hand, showing a commitment to environmental sustainability can enhance a brand’s image in the market. Companies that follow sustainable practices earn goodwill from customers. A 2023 PwC study reveals that more than 70% of consumers are ready to pay more for sustainably produced goods. 

The push toward sustainable living has unleashed a wave of innovation in the Packaging Paper Industry. Companies are reimagining packaging with materials that not only reduce environmental impact but also enhance product performance and consumer interaction. For example, the global packaging paper industry was estimated at $192.63 billion in 2024, and kraft liner papers held almost half of the industry share. Advancements in recycling technology have improved the performance and quality of such papers, making them a viable option for various industries such as F&B, personal care and cosmetics, and e-commerce & retail. Let’s have a look at some of the examples: 

  • An Australian start-up, Earthodic, is pioneering water-resistant coatings made from lignin, a renewable material derived from wood pulp. This biodegradable coating allows packaging to remain fully recyclable, solving a long-standing challenge in eco-friendly design.

  • UK-based company Notpla is incorporating natural fibers derived from seaweed into molded packaging for food. In November 2023, the Netherlands government officially recognized Notpla's unique material as the first and only one to meet the European Union's Single Use Plastic Directive standards for being truly plastic-free.

  • What is not collected cannot be recycled. So, some companies are also integrating QR codes or NFC tags to educate consumers on recycling or reuse. These smart packaging technologies allow customers to scan products for authenticity and sustainability information, creating a more transparent and connected supply chain. 

Trending Now

  • Reusable and Circular Systems: The reusable packaging market is growing significantly. Companies are investing in circular packaging models where materials are continually reused or recycled.

  • Lightweight, Low-Impact Designs: Companies are coming up with ultra-light paper refill packs, reducing both material use and carbon emissions from transport, offering convenience without compromise. In May 2024, Nescafé introduced its first-ever paper refill pack, designed to be recycled through curbside collection. This packaging reduces the weight of packaging materials by a whopping 97%.

  • Use of Natural Products: Use of mycelium-based materials and agricultural by-products blended with paper pulp is another important trend in the market. Companies such as Ecovative are incorporating natural mushroom fibers into their molded packaging designs.

  • Development of High-strength Products: Companies are also using thinner yet durable corrugated solutions for packaging. It reduces raw material use, energy in transport, and carbon footprint. 

Conclusion 

The packaging industry is no longer confined to wrapping products. With environmental regulations tightening and consumer expectations rising, paper-based packaging is proving to be both a smart business decision and a moral imperative. Businesses that embrace this shift are responding to this demand. They are reshaping it by combining ecological integrity with design innovation, creating packaging that protects products while also protecting the planet. 

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

North America Food Packaging Market: Rise of Ready-to-Eat

North America Food Packaging Industry Overview

The North America Food Packaging Market was valued at $111.8 billion in 2024 and is expected to grow at a CAGR of 4.8% from 2025 to 2030. With approximately 331 million people residing in North America as of 2023, and an increasing number living in urban areas with fast-paced lifestyles, there's been a significant rise in the consumption of packaged foods, especially ready-to-eat meals. Recent trends indicate that nearly 60% of consumers choose convenient food options due to their busy schedules. This growing dependence on packaged products is further amplified by the expansion of foodservice suppliers and digital platforms that simplify food ordering, ultimately making these meals more accessible.

Detailed Segmentation:

  • Type Insights

Flexible packaging is expected to grow at the fastest CAGR of 5.2% over the forecast period. The increasing demand for convenience foods and on-the-go meals has driven the popularity of flexible options that provide resealability and portion control. Moreover, technological advancements have enhanced barrier properties, ensuring product freshness and shelf life, appealing particularly to health-conscious consumers.

  • Material Insights

Plastic packaging is expected to register the fastest growth of 5.4% over the forecast period. The convenience of plastic containers aligns with consumer lifestyles seeking quick meal solutions. Moreover, innovations in plastic materials, featuring enhanced barrier properties and increased recyclability, are facilitating adoption as manufacturers address sustainability trends while meeting consumer expectations for quality and safety.

  • Application Insights

The household sector is projected to grow at the fastest rate of 5.5% over the forecast period as consumers increasingly prioritize efficiency and convenience in daily routines. With a shift toward home meal preparation, households are turning to packaged food solutions that simplify cooking processes while ensuring quality. Furthermore, rising disposable incomes are enabling consumers to invest in premium packaged products that enrich their culinary experiences at home.

  • Country Insights

U.S. Food Packaging Market Trends

The U.S. food packaging market dominated North America with a revenue share of 78.0% in 2024. The diverse food industry, particularly in dairy and beverages, drives demand for innovative packaging that ensures product safety and freshness. Growth in e-commerce and meal delivery services enhances the need for efficient packaging solutions.

Mexico Food Packaging Market Trends

The food packaging market in Mexico is projected to grow at the fastest rate of 6.6% over the forecast period. Rising disposable incomes are prompting consumers to prefer convenient, high-quality packaged foods. The rise of modern retail and e-commerce platforms, coupled with government initiatives promoting sustainable packaging practices, positions Mexico as a significant player in North America market.

Gather more insights about the market drivers, restraints, and growth of the North America Food Packaging Market

Key Companies & Market Share Insights

Organizations are undertaking strategic initiatives in product innovation, sustainability, and technology advancements to enhance packaging solutions, driven by consumer demand for convenient and eco-friendly options.

Key North America Food Packaging Companies:

  • Amcor plc
  • Sealed Air
  • Sonoco
  • Berry Global Inc.
  • WestRock Company
  • Mondi
  • Genpak LLC
  • Pactiv Evergreen Inc.

Order a free sample PDF of the Market Intelligence Study, published by Grand View Research.

Recent Developments

  • In December 2024, Berry Global and VOID Technologies successfully collaborated to launch a high-performance, recyclable polyethylene film for pet food packaging, enhancing sustainability while improving strength and puncture resistance.
  • In August 2024, Pactiv Evergreen Inc. launched Recycleware Reduced-Density Polypropylene meat trays, offering a sustainable alternative to foam polystyrene, recognized by the Association of Plastic Recyclers for recyclability and environmental impact. 
  • In July 2024, Mondi launched FlexiBag Reinforced, a recyclable, mono-PE-based packaging solution with enhanced mechanical properties, enabling cost-effective customization for pet food while incorporating post-consumer recycled content to promote sustainability.

Oxygen Concentrator Market Outlook: Growth, Regions, Leaders, and Segment Showdowns

Oxygen therapy is moving out of hospitals and into living rooms. As chronic respiratory conditions become more common and populations age, o...